Private Lender for Construction Finance
Finance that moves at the pace of the worksite, not the certifier
Experts in strategic, short-term secured finance
Secured Lending is a private, non-bank lender for builders, contractors and trades. Construction had more companies enter external administration or receivership than any other industry in 2025-26, about one in four, according to ASIC. Wages, materials and subcontractors fall due every week, while progress claims and retentions are often paid late. We top up working capital, clear ATO debt and refinance lenders, with loans from $250,000 secured by a first or second mortgage over property your business or a director owns. If your company needs cash between claims, we would be glad to help.
Who We Help
- Residential builders carrying a job from one certified stage to the next
- Commercial builders funding trades and materials ahead of a certified claim
- Civil and infrastructure contractors mobilising on government and tier-one contracts
- Subcontractors and trades waiting 60 or 90 days on a head contractor
- Fit-out and refurbishment companies fronting materials on a fixed-price contract
- Construction businesses bridging a deposit, a land settlement, or a retention release
- Builders carrying an ATO debt that is compounding while claims sit uncertified
- Builders and contractors topping up working capital while progress claims and retentions are paid late
- Land-rich operators declined by a bank on servicing, despite owning the yard, the site or their home
How We Can Help You
- We assess the property and the exit, so lumpy progress-payment cash flow does not decide the outcome
- Our own valuers assess construction security directly, including part-built sites, industrial yards and land holdings
- We hold our own funds and our own credit authority, so a decision takes hours and settlement can happen within 24 hours
- We take a first or second mortgage, so an existing facility does not need to be broken to release capital
- Terms run from 1 to 24 months, and most borrowers are with us for 3 to 6 while the claim, the sale or the refinance completes
- Rates start from 9.7% p.a., interest only for the term
Construction Finance Scenarios We Fund
Construction brings us one of the biggest volumes of enquiry we take, and it is not one product. A subcontractor chasing a head contractor needs a different structure to a civil contractor mobilising on a new contract. Below are the scenarios we are asked for most often.
Topping up working capital between claims
Progress claims are often paid weeks after they are lodged, and retentions months after practical completion. Wages and subcontractors are paid every week and suppliers expect payment on their own terms, so a profitable builder can still run short of cash between payments.
A working capital loan tops up the business bank account, so payroll runs, suppliers are paid and the crew stays on site. It is a short facility, repaid from the claims and retentions once they are paid, or from a refinance.
- Wages and subcontractors paid every week while a claim is unpaid
- Supplier accounts kept within terms, so materials keep arriving
- Plant hire and site costs covered through a slow payment run
- A late retention release no longer holds up the next job
- Second mortgage keeps the existing first facility intact
- Exit is the next paid claim, a retention release or a refinance
Residential builders
A fixed-price contract, a frame stage signed off but not yet paid, and a slab going down on the next job. The money leaves the business at the start of a stage and comes back at the end of it.
The stage gets built and the next slab still goes down on schedule, whatever the certifier is doing with the last claim. The facility carries the job through the stage and is retired by the certified claim or the settlement, so the repayment is already funded by work that has been done.
- Slab, frame, lock-up and fit-out costs are met before the claim is certified
- Suppliers and trades are paid on the stage, not on the certifier's calendar
- The next job starts on time instead of waiting on the last one to pay out
- Works where the last stage payment is late and the next stage has already begun
- A fixed-price contract is held to without stopping work to wait for money
- Exit is the certified progress claim or a settlement
Commercial builders
A commercial job runs on a certified claim cycle, and the certifier works to their own calendar. Trades, materials and site costs fall due in the meantime, and the next project wants a deposit before the last one has paid out.
The claim cycle stops deciding what you can take on. The trades stay paid, the site stays staffed, and the deposit on the next project goes down while the last claim is still sitting with the certifier. The facility is retired when that claim is paid.
- The deposit on the next project is paid before the last claim is certified
- Trades, materials and site costs are covered through the certification cycle
- Retention held after practical completion is bridged rather than waited out
- An uneven claim book and an uneven trading year do not decide the file
- Lending to Pty Ltd companies, trusts and SMSFs
- Exit is a certified claim, a retention release, or a refinance
Civil and infrastructure contractors
Mobilising on a civil contract puts plant, crews and materials on the ground before a single claim is submitted. Government and tier-one payment runs then take 45, 60 or 90 days from the date of that claim.
Plant, crews and materials are on the ground from day one, so the contract is never at risk before it has started. The facility is retired from the payment run, and retention held back at practical completion can be bridged the same way.
- Mobilisation is funded before the first claim is even submitted
- Bridges 45, 60 and 90 day government and tier-one payment cycles
- Retention held at practical completion is bridged instead of waited out
- A slow payment run stops being a reason to turn down the next contract
- Mobilisation costs do not have to come out of the last job's margin
- Exit is the contract payment run or a retention release
Subcontractors and trades
Concreters, formworkers, steel fixers, electricians and plumbers carry wages and materials across a whole job, then get paid when the head contractor decides to pay. One slow payer can stall an entire crew.
The crew stays on site and the wages are paid on Friday, whatever the head contractor decides to do. The invoice can then be chased on its own timeline rather than yours, and the facility is retired when the payment is made.
- The crew is paid on Friday while the head contractor's invoice sits unpaid
- Covers wages, materials and plant hire so the job keeps moving
- One slow payer stops holding up every other job you have on
- Second mortgage keeps the existing home loan intact
- The invoice is chased on your terms rather than under pressure
- Exit is the head contractor payment or a refinance
Bridging finance for construction
A site comes up and the deposit falls due before the last project settles. A retention sits with the principal for months after practical completion. A land purchase has an unconditional date that will not move.
The deposit is paid, the land settles on the date that was never going to move, and the site ends up yours rather than the next builder's. The facility is short by design and retired by the settlement, the retention, or the claim that was always going to fund it.
- The deposit is paid and the site is not lost to another builder
- An unconditional settlement date is met when it will not be extended
- Retention sitting with the principal is bridged instead of waited out
- Caveat loan available where the window is genuinely urgent
- The last project settles on its own timeline, not the next one's deadline
- Exit is the settlement, the retention, or a certified claim
ATO tax debt
Penalty interest compounds on the balance, a broken payment plan escalates quickly, and a director penalty notice can follow while the claims that would clear it are still with the certifier. The ATO says that where a business does not pay or does not engage with it, it may take firmer action, including garnishee notices to your bank or customers and director penalty notices.
The position is cleared in a single payment and the escalation stops, so the ATO no longer sets the pace of your business. You then repay from the claim book on a short, defined facility.
- Clears the ATO position in a single payment
- Stops penalty interest compounding on the balance
- Suitable where a payment plan has already been broken
- Removes the pressure of recovery action while the claims sit with the certifier
- The site keeps running while the debt is dealt with in the background
- Exit is the claim book, a site sale, or a refinance
Refinancing off a bank
Banks have pulled back from construction, and the result lands on builders who have done nothing wrong. A facility is not renewed, a limit is cut, or a review arrives mid-job because the sector itself has been repriced, and the yard and the site underneath it all are still there.
You keep the job, the yard and the crew, and you move to a longer-term lender on your own timeline rather than the bank review timeline. The facility is retired by that refinance.
Some lenders are calling in loans outright, and we can refinance that lender out before or after it issues a default notice or appoints a receiver.
- Refinances an expiring or non-renewed facility
- Removes the deadline a mid-job facility review creates
- A cut limit does not have to mean stopping work or letting the crew go
- The job keeps running while a longer-term lender is arranged properly
- A repricing of the sector stops being your problem to solve this week
- Exit is a refinance to a longer-term lender, or a site sale
Our Loan Products
- First mortgage: the cleanest position, used where the yard, the site or the director's property is unencumbered, or where an existing facility is being refinanced in full
- Second mortgage: sits behind an existing first, so a bank facility and a fixed rate do not have to be broken to release equity from the yard or the home
- Bridging loans: covers the gap between a cost on the worksite and the certified claim, retention or settlement that repays it
- Caveat loans: our fastest product, lodging a caveat rather than registering a full mortgage, for genuinely urgent and short repayment windows such as a payroll run or a deposit deadline
Related Reading
- →Construction lenders in Australia
- →Private lender for commercial builders finance
- →Second mortgage for construction costs
- →Bridging finance for construction equipment
Bad Credit in Construction Is Normal, and Fundable
Retentions, a slow progress claim and one client who did not pay will put arrears on a builder file inside a quarter. Banks treat that as a credit event. We treat it as the cash flow gap it is. Where the security property carries equity inside 70% LVR and there is a settlement, a sale or a refinance ahead, we fund it. Rates from 9.7% p.a.
- →Clearing mortgage arrears before they become a default
- →What a bad credit business loan needs from you
"Construction is one of the biggest categories of enquiry we get, and the pattern is almost always the same. The job is sound, the claim is coming, and the money is three weeks behind the wages. We are not underwriting a claim book. We are funding the gap, so the crew stays on site and the next contract gets taken on rather than declined."
Gino Tabila
Associate Director
Recently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
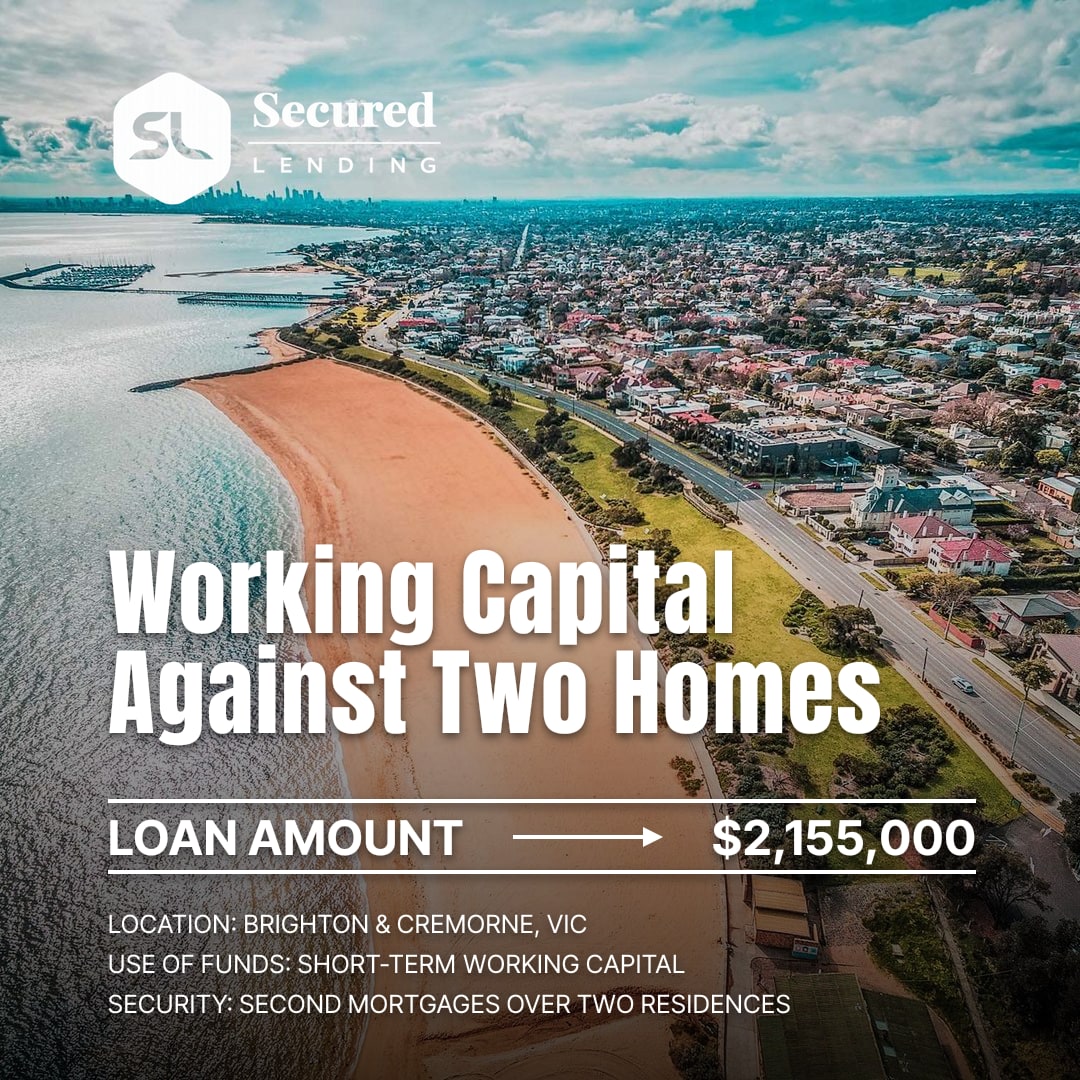
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
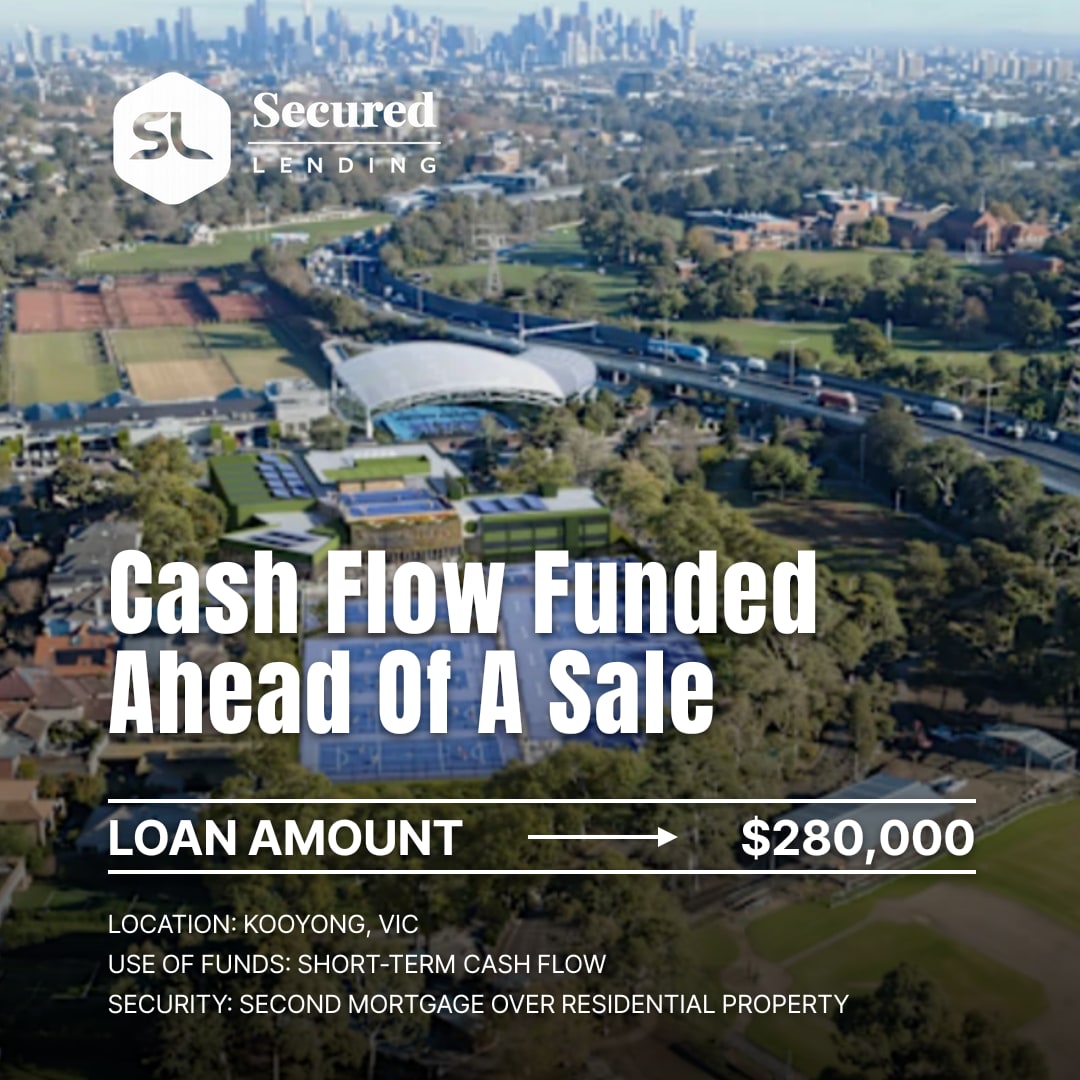
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours