Fast Caveat Loans for Urgent Funding
Fast, caveat-secured cashflow within 24 hours
Experts in strategic, short-term finance
What Is a Caveat Loan?
A caveat loan is a short-term business loan secured by your property. It lets you access capital without refinancing your existing mortgage. Instead, a caveat is lodged on your title, which gives the lender security without affecting your first mortgage.
You can borrow against the equity in a residential, commercial, or investment property, then use the funds however your business needs.
Why Choose a Caveat Loan?
- •Fast Settlement: Most loans are funded within 24 to 48 hours, ideal for urgent business needs
- •Flexible Use: No restrictions on how you use the funds: cash flow, tax debt, equipment, or anything else
- •Minimal Paperwork: No full credit assessments, long delays, or drawn-out applications
- •Keep Your Existing Mortgage: Your first mortgage stays in place; we simply add a caveat on the title
Common Use Cases
Businesses choose caveat loans when time, flexibility, and access to equity matter most:
- •Cover payroll or urgent supplier invoices
- •Bridge cash flow gaps caused by late-paying clients
- •Settle outstanding ATO tax debts
- •Purchase equipment or stock immediately
- •Fund a business expansion or acquisition
- •Manage emergency business operating expenses
- •Avoid foreclosure or refinance short-term debt
- •Seize limited-time opportunities that banks can't fund fast enough
Eligibility Criteria
To qualify, you'll need:
- •Property with sufficient equity (residential or commercial)
- •A clear business purpose for the funds
- •The ability to repay the loan within the short term
Caveat Loan Scenarios We've Funded
These are real situations where a fast, caveat-secured loan kept a business moving. Each links to a client success story where we have funded it.
- •Cleared an ATO debt and operating costs to pull a Sydney café back from insolvency
- •Stopped an ATO wind-up application with funding settled inside 24 hours
- •Met a next-day property settlement with $271,000 funded in 4 hours
- •Released $250,000 in working capital for a Brisbane café within 36 hours
- •Paid out an expensive private lender before default penalties hit
- •Delivered urgent funds in under 2 hours when timing was critical
- •Bridged a supplier payment deadline to protect stock and trade terms
- •Cleared mortgage arrears to halt enforcement while a refinance completed
Caveat Loans for Business Owners With Bad Credit
A caveat loan is the fastest thing we do, and it is often the only thing available to a business owner with a default on file and a deadline this week. We register an interest on the title and lend against the equity in the property, to 70% LVR. Credit history sits well down the list. No full financials, no tax returns, and funds inside 24 hours where the title is clean.
Industries We Service
Caveat loans for builders and contractors
A caveat loan is registered against your title rather than settled as a mortgage, which is why it can be in place in hours rather than weeks. The existing mortgage is not touched and does not need to be refinanced.
It is repaid when the progress payment is made, the job completes, or a longer facility takes over. This is the product for the deadline measured in days, not for a funding need that can wait for a settlement.
A caveat loan can help you:
- Meet a payroll that falls due before a progress claim is paid
- Pay a supplier who has stopped delivering to the site
- Cover a bond or security deposit due before a job starts
- Fund the deposit on a contract that will not be held open
- Act without refinancing or disturbing the existing mortgage
- Have funds in place in as little as 24 hours
Caveat loans for property developers
A caveat loan is lodged on the title of a site or a completed lot rather than settled as a mortgage, so it can be in place in hours. The senior facility is not disturbed.
It is repaid when the stock settles, the senior debt is drawn, or the site is sold. It exists for the deadline a project cannot renegotiate.
A caveat loan can help you:
- Meet a settlement date another lender cannot fund in time
- Pay a council or authority fee that is holding up an approval
- Cover a cost overrun with the certifier days away
- Release funds against a completed lot before it settles
- Act without disturbing the senior construction facility
- Register the caveat the same day the deadline lands
Caveat loans for property investors
A caveat loan is registered on the title of a property you already own, which is why it moves faster than any mortgage can. The existing loan stays where it is.
It is repaid when the outgoing property settles, or when a longer facility takes over. It is built for the deal that will be gone by the time a mortgage could be prepared.
A caveat loan can help you:
- Complete a purchase when settlement is days away
- Cover a shortfall when a buyer falls over at the last minute
- Fund a deposit on an off-market property before it is listed
- Pay stamp duty that has fallen due ahead of a sale
- Act without refinancing your existing mortgage
- Move faster than a mortgage could be prepared and settled
Caveat loans for retailers
A caveat loan is lodged against a director's home or investment property rather than settled as a mortgage, so it can be in place before a supplier deadline passes. Most retailers lease their space, so the director's property is the security.
It is repaid out of the trade it funded, or by a longer facility once the season is banked. It is for the order or the payment that cannot wait a fortnight for a mortgage to settle.
A caveat loan can help you:
- Pay a supplier who will not hold stock any longer
- Secure a lease or a site before another tenant takes it
- Cover rent or outgoings arrears before a landlord acts
- Fund stock for a trading window that is already open
- Act without refinancing the director's home loan
- Draw funds before a supplier's cut-off passes
Caveat loans for wholesalers and importers
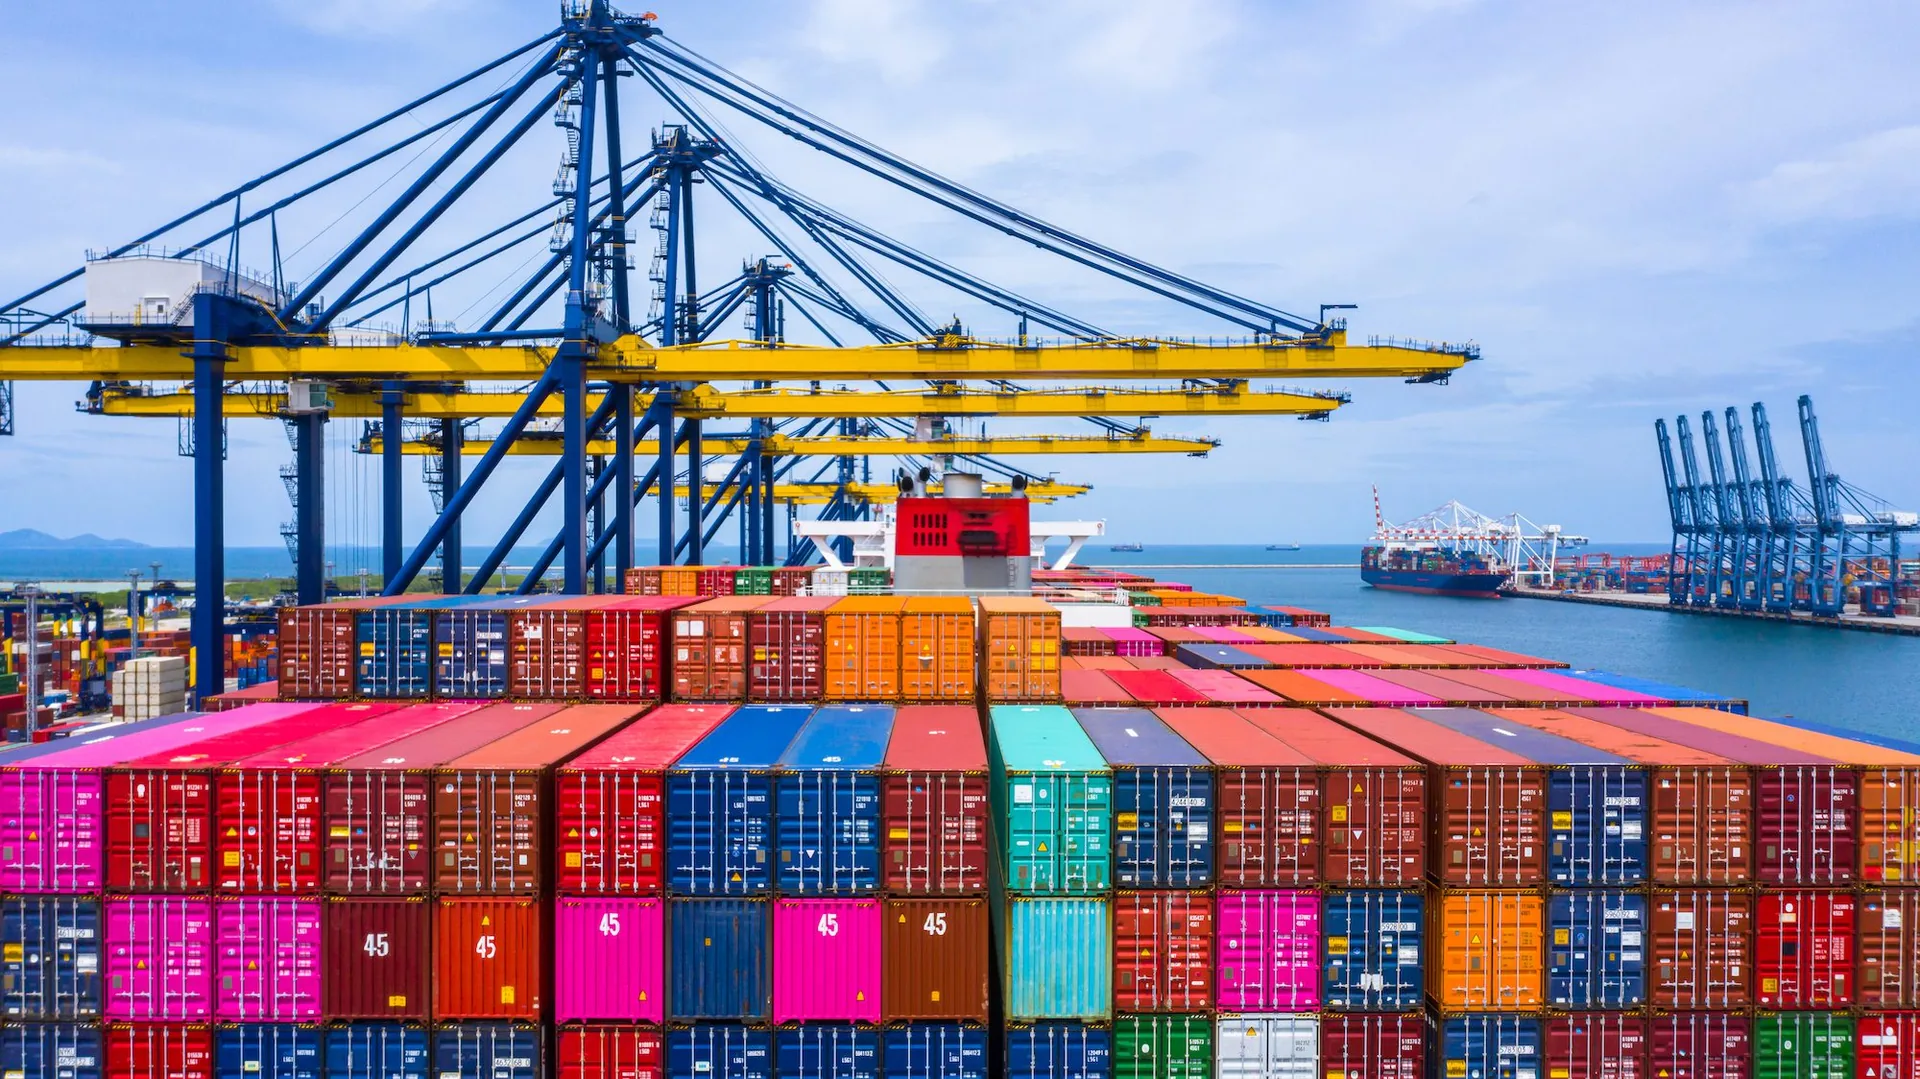
A caveat loan is registered on title rather than settled as a mortgage, which is why it can clear a shipment before demurrage starts running. The existing mortgage is untouched.
It is repaid as the stock sells through, or when a longer facility takes over. It is for the container already sitting at the port, not the one that ships next quarter.
A caveat loan can help you:
- Clear a container before storage and demurrage start running
- Pay a supplier holding a shipment against payment
- Cover a customs or duty bill that has fallen due
- Fund a bulk buy on a deadline the seller will not move
- Act without refinancing the existing mortgage
- Fund before demurrage turns a delay into a cost
Caveat loans for pubs, hotels and venues
A caveat loan is lodged on the title of the venue, or a director's property where the venue is leasehold, rather than settled as a mortgage. It is in place in hours, and the existing facility is not disturbed.
It is repaid from trade, from the sale of an outgoing venue, or by a longer facility. It is for the deadline that arrives mid-season, when there is no time to arrange anything slower.
A caveat loan can help you:
- Meet a payroll or a supplier bill in a quiet trading week
- Pay a deposit on a venue before another buyer takes it
- Cover a licence or compliance cost with a deadline attached
- Fund an urgent repair that would otherwise close the doors
- Act without refinancing the venue's existing mortgage
- Get funds in place before a trading week is lost
Caveat loans for transport and warehousing operators
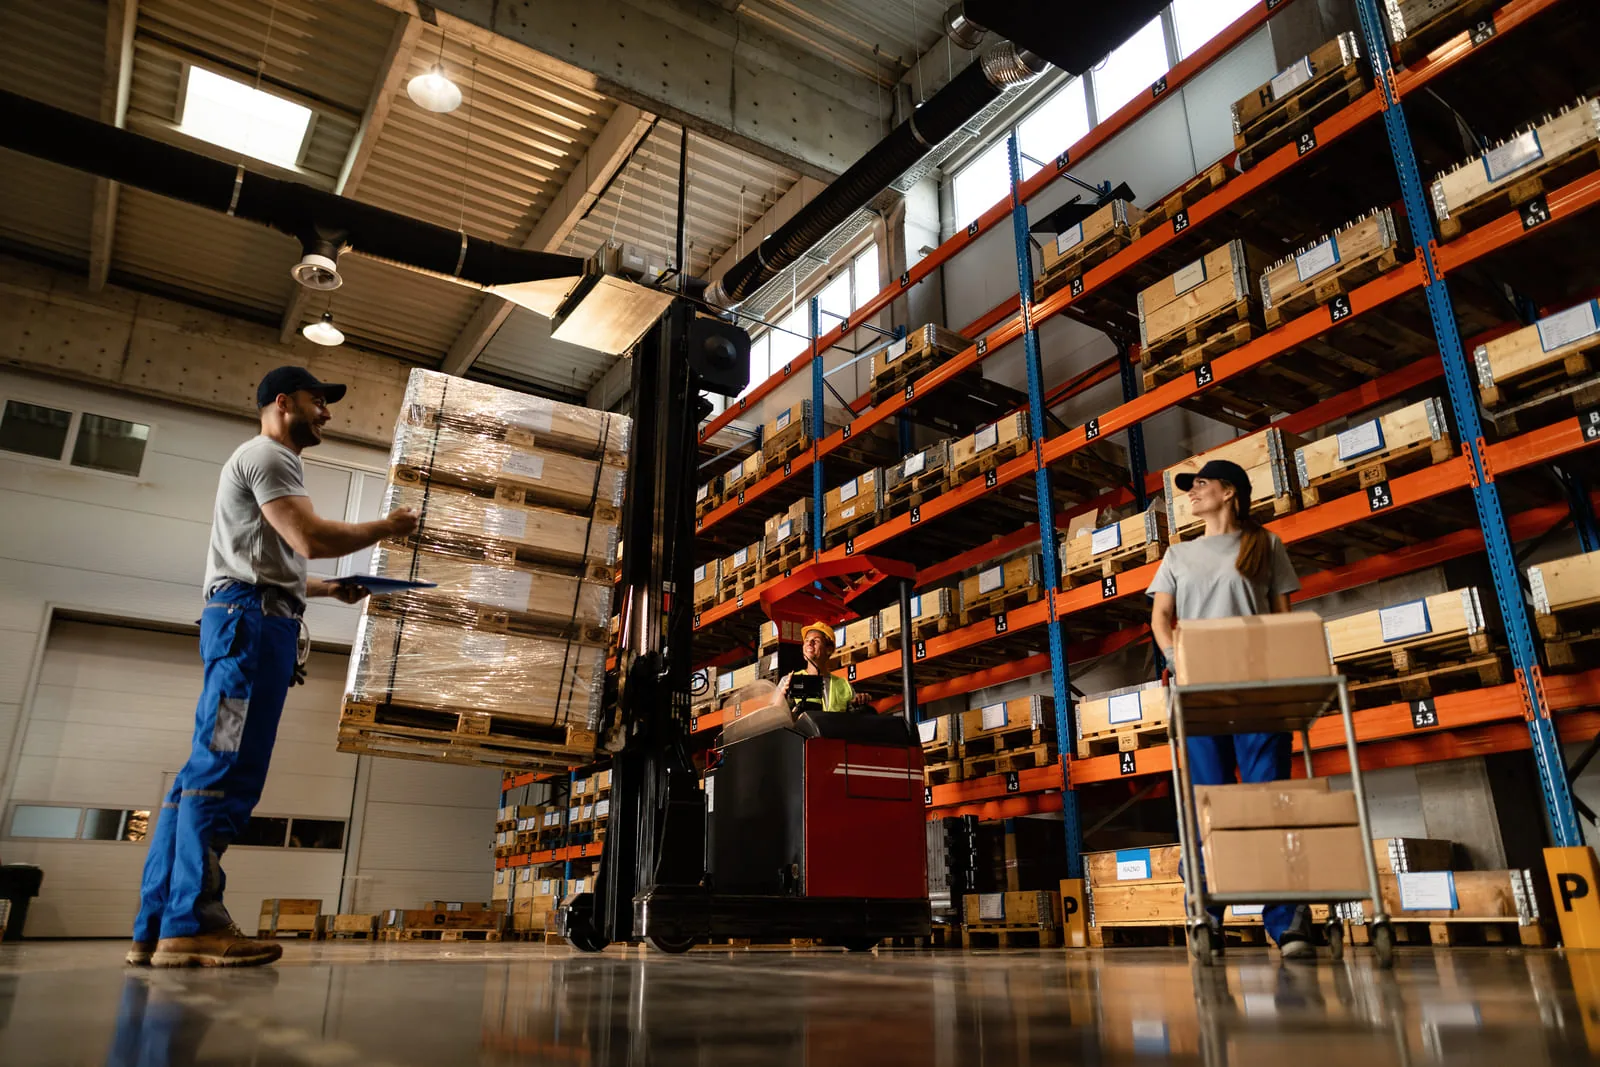
A caveat loan is registered on the depot, the warehouse or a director's property rather than settled as a mortgage, so it is in place in hours.
It is repaid from contract receipts, or by a longer facility once the fleet is earning. It is for the start date that has already been agreed and will not be moved.
A caveat loan can help you:
- Meet a contract start date that has already been agreed
- Pay for fuel, tyres or repairs that cannot wait
- Cover a bond or deposit on a new depot
- Fund a vehicle purchase before the seller moves on
- Leave the depot's mortgage exactly where it is
- Fund before a start date turns into a lost contract
Caveat loans for technology companies
A caveat loan is registered rather than settled as a mortgage, so the funds are available in a day or two rather than in the weeks a mortgage takes to prepare and settle.
It is repaid when the round closes, the invoice settles, or a longer facility takes its place. It is used where a date cannot be moved: a vendor's completion date, an annual licensing renewal, or a payroll that has to be paid on time.
A caveat loan can help you:
- Have the caveat registered in a day or two rather than wait on a mortgage settlement
- Pay an acquisition deposit while the vendor is still taking offers
- Clear an engineering payroll that has to land on its due date
- Renew a cloud or licensing commitment billed annually in advance
- Fund the setup costs on a contract awarded with a short start date
- Fund a cost that falls due before the round completes
Caveat loans for manufacturers
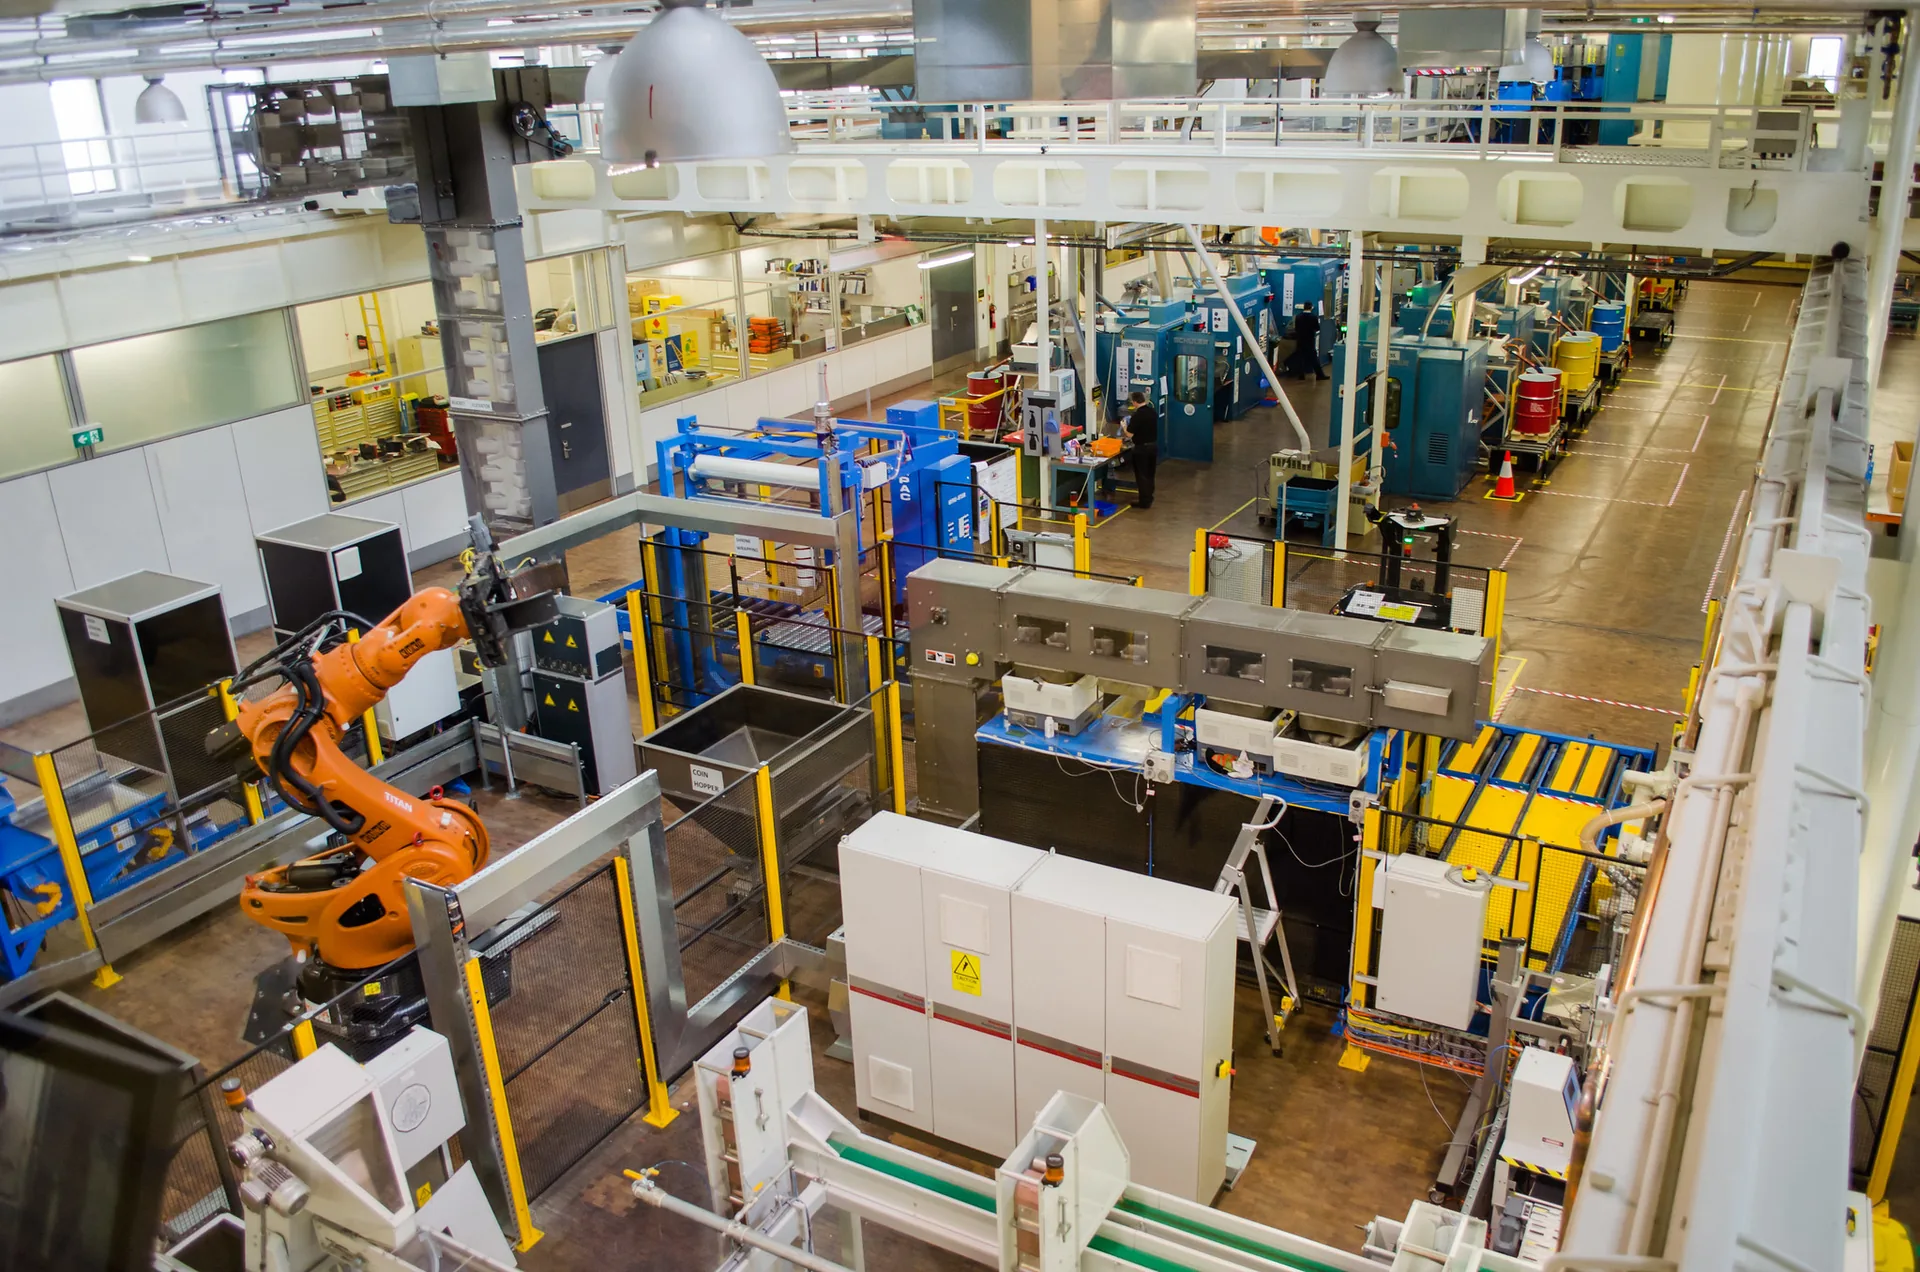
A caveat loan is lodged on the factory title rather than settled as a mortgage, so it can be in place before a production line stops.
It is repaid when the customer pays, or when a longer facility takes over. It is for the material order or the repair that the schedule cannot absorb.
A caveat loan can help you:
- Buy materials for an order the line is already tooled for
- Pay for an urgent repair that would otherwise stop the plant
- Cover a supplier who has put the account on hold
- Fund a deposit on machinery before the seller moves on
- Act without disturbing the existing facility on the site
- Fund before a stopped line becomes a late order
Caveat loans for practices and professional firms
A caveat loan is registered on a director's home or investment property rather than settled as a mortgage, so it is in place well before a practice facility could be.
It is repaid when the long-term practice facility settles. It is for the vendor deadline that will not be extended.
A caveat loan can help you:
- Meet a vendor deadline on a practice acquisition
- Pay a deposit before another buyer is given the chance
- Cover a partner's exit that has to be settled now
- Fund equipment the practice cannot operate without
- Act without refinancing a director's home loan
- Move inside a vendor's deadline, not a lender's
"Caveat lending is one of the fastest tools in private finance, and it is well suited to genuinely urgent situations. By registering an interest against the title, we can move capital quickly based on the equity position. Where the property supports it and there is a clear repayment path, settlement within 24 hours is realistic, and we are always happy to help work out whether it is the right fit."
Gino Tabila
Associate Director
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
Frequently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Caveat Scenarios We Can Help With
Explore the specific situations our caveat loans are built for, from urgent ATO and settlement deadlines to bridging finance, equity release, and credit-impaired scenarios. Find the case that matches yours and see how fast caveat funding can help.