Fast Payday Super Finance for Urgent Deadlines
Pay super on payday, or clear the charge that follows
Experts in strategic, short-term finance
Since 1 July 2026, Payday Super requires employers to pay superannuation at the same time as wages, and the money has to be received by each employee's fund within 7 business days of payday. Miss that window and the unpaid super converts into the Superannuation Guarantee Charge, a liability owed directly to the ATO. At Secured Lending, we provide fast, property-secured finance so a tight payroll never turns into an ATO debt, and so a charge that has already landed can be cleared quickly.
Why Consider a Payday Super Loan?
- •Meet the 7-Business-Day Deadline: Fund super on payday so the charge is never triggered
- •Avoid the Superannuation Guarantee Charge: Stay clear of the shortfall, daily interest, and administrative uplift of up to 60%
- •Protect Your Directors: Reduce exposure to a Director Penalty Notice that makes directors personally liable for unpaid super
- •Free Up Working Capital: Keep every pay run funded on time without draining operating cash
How Missing the Deadline Becomes an ATO Debt
Once super is not received by the fund within 7 business days, the amount becomes a Superannuation Guarantee Charge payable to the Commissioner of Taxation, not to the fund. The charge is built from the shortfall, notional earnings that accrue at the ATO general interest charge rate and compound daily from payday, and an administrative uplift of up to 60%. Unpaid super also sits behind the Director Penalty regime, so a company liability can become a personal one. Property-secured finance lets you settle the position before it reaches that stage.
Is a Payday Super Loan Right for You?
Ask yourself:
- •Is a tight payroll putting the 7-business-day super deadline at risk?
- •Do you already owe a Superannuation Guarantee Charge to the ATO?
- •Would property-secured funding settle the position faster than a bank can move?
- •Are you a director who wants to stay clear of personal liability for unpaid super?
If you answered yes to any of the above, short-term finance secured by property could be the right solution.
Payday Super Loans for Employers With Bad Credit
Super is now due on every pay run, and a missed payment becomes a charge owed straight to the ATO. Banks will not move on that timeline, and a bad credit file removes the option entirely. We fund against residential, commercial or industrial property, so the super gets paid on time whatever your file looks like. Rates from 9.7% p.a., and no full financials required.
Industries We Service
Payday super finance for builders and contractors
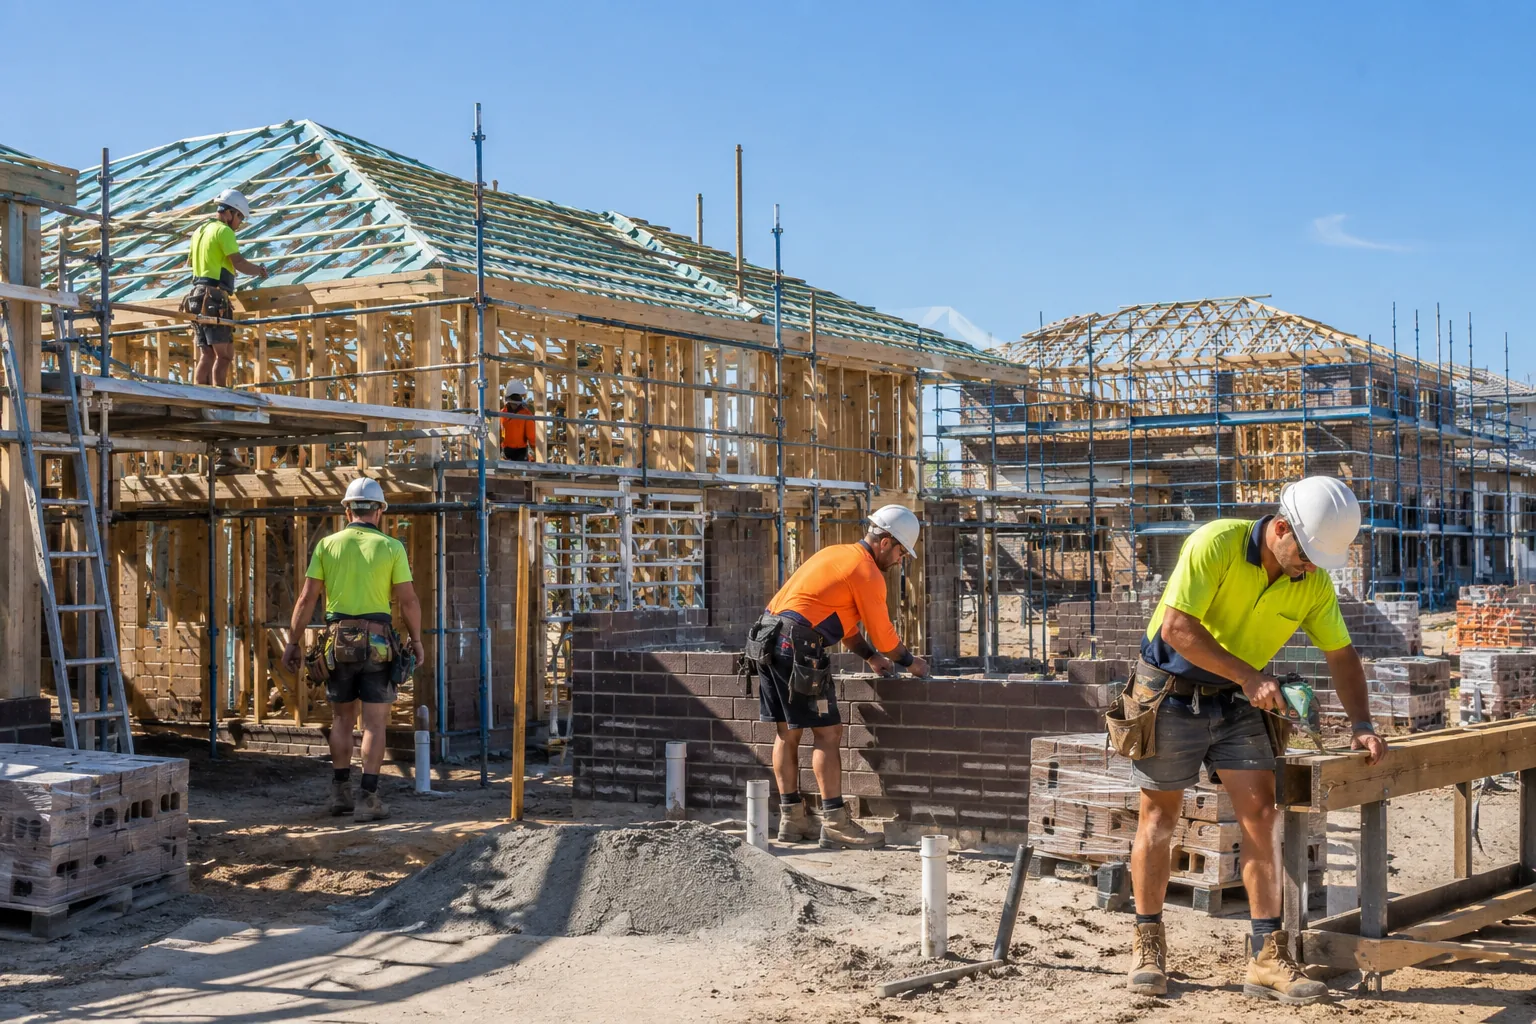
Construction carries a large wage bill against progress claims that arrive weeks later, so a single slow certifier can leave a pay run short in the week super is due. A payday super loan funds that super on time, and we lend against the yard, the office, or a director's own property.
It is repaid when the progress payment is made or the security is sold, so a retention held back or a variation still in dispute becomes a timing question rather than a missed deadline. Because our funds are our own, we can settle inside the 7 business days super has to reach the fund.
A payday super loan can help you:
- Fund super on payday while a progress claim sits with the certifier
- Keep each pay run's super current when retentions are held back
- Meet the 7-business-day deadline on a large site payroll
- Clear a Superannuation Guarantee Charge that threatens a licence or a tender
- Cover super and wages together on a job that pays out next month
- Settle an SGC assessment before it reaches a director penalty notice
Payday super finance for pubs, hotels and venues
Venues run rosters that swell for events and peak seasons, so the wage bill, and the super on it, spikes exactly when trade has not yet banked. A payday super loan funds super on payday through those peaks. Freehold operators secure against the venue property, and leasehold operators secure against a director's home or investment property, which is the normal pattern in this sector.
It is repaid out of the season the roster was built for, or by a refinance once the trading figures support one. A quiet winter becomes a timing pattern rather than a reason to fall behind on super, and the venue keeps trading for the whole term.
A payday super loan can help you:
- Fund super on a roster that swells for a peak season or a major event
- Keep super current through a quiet trading month
- Meet the 7-business-day deadline across multiple venue payrolls
- Clear a Superannuation Guarantee Charge before a liquor licence review
- Cover super owed on casual and event staff without cutting shifts
- Settle an SGC that has already been assessed against the company
Payday super finance for manufacturers
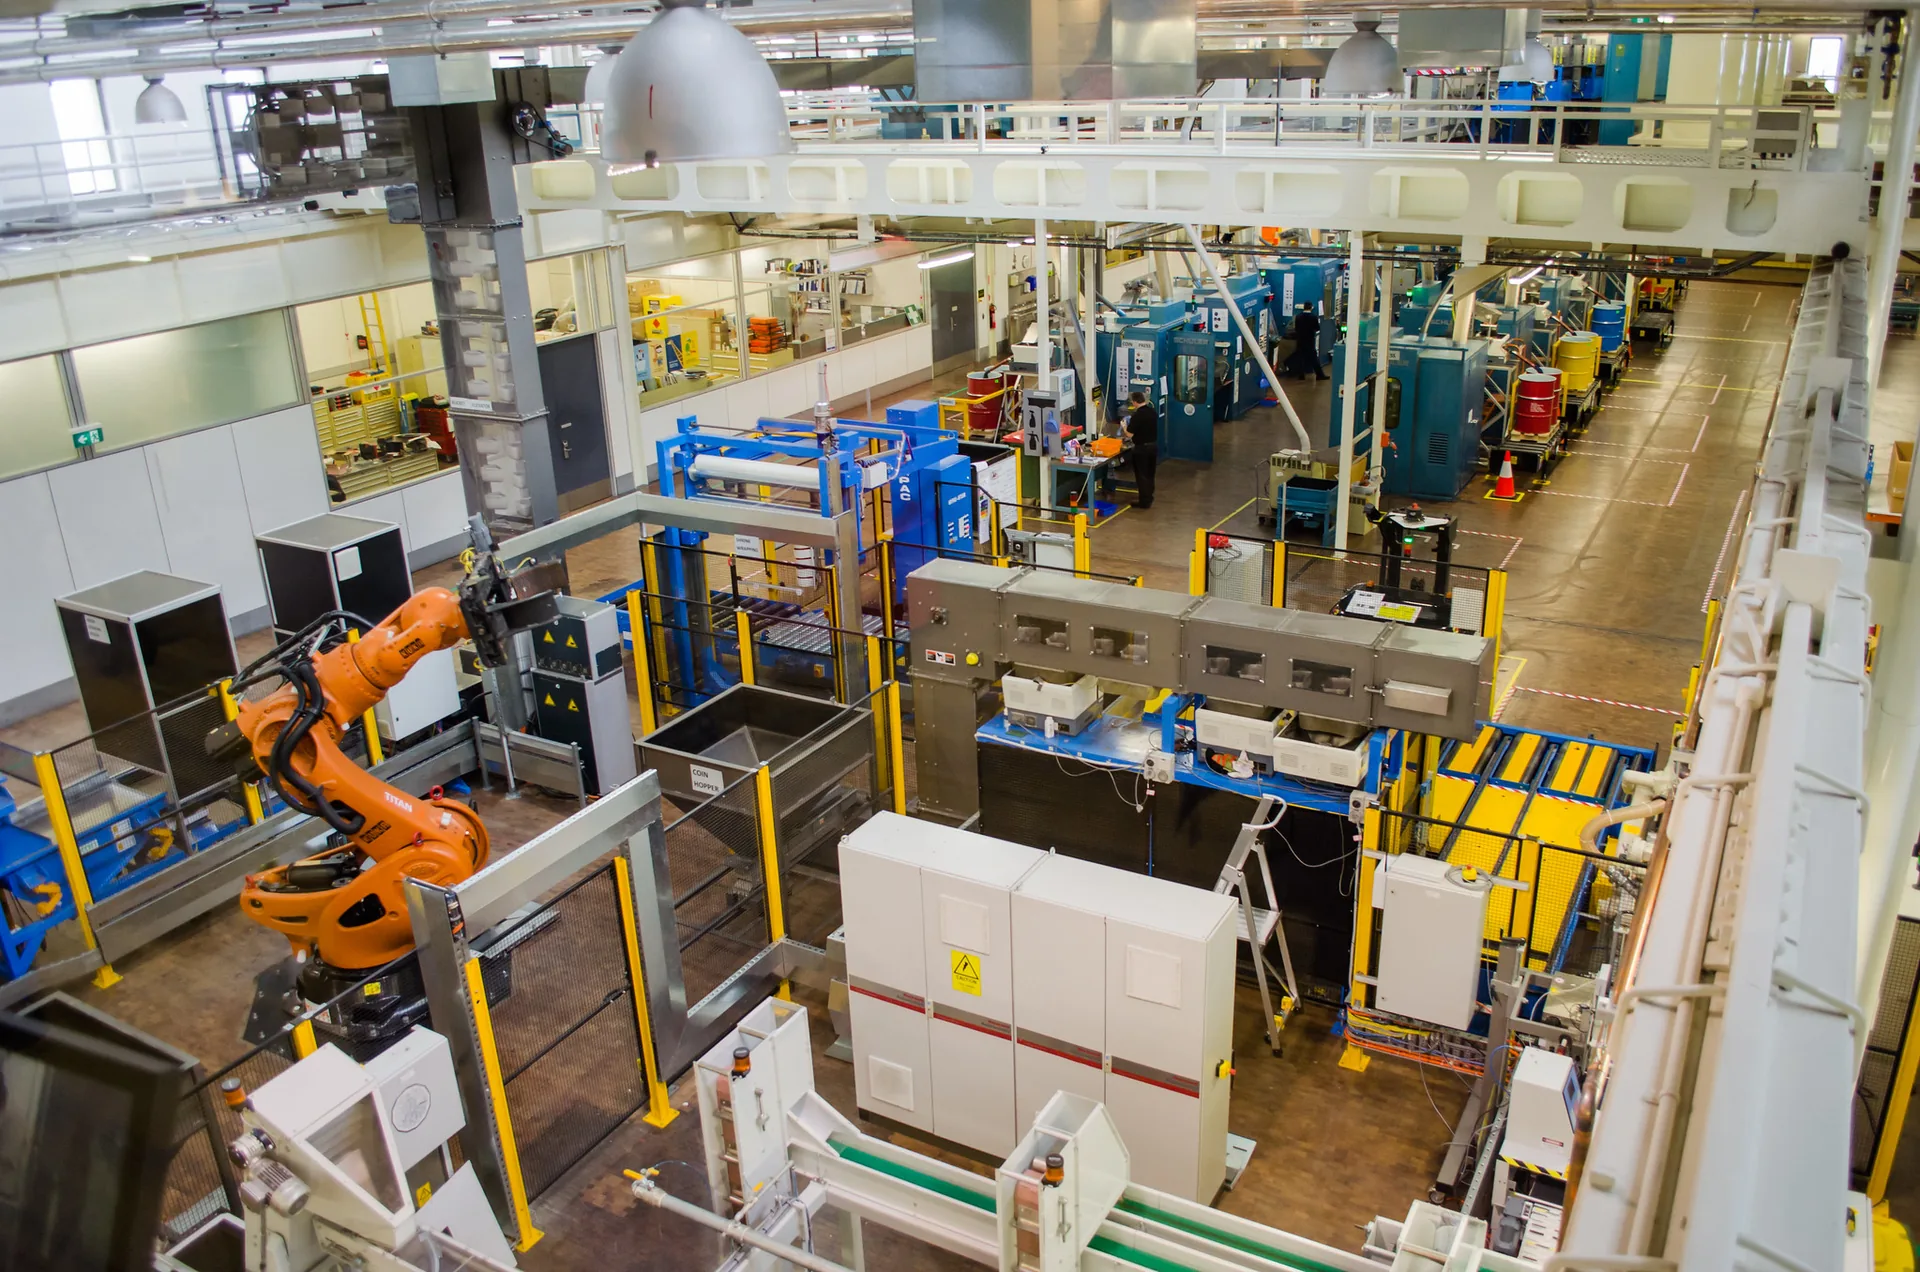
A factory floor carries a steady wage bill that does not pause when a customer pays late or a large order ties up cash, so super can fall due in a week when the account is thin. A payday super loan funds it on time. Our security is the factory or industrial property the business owns, or another property held by the company, the trust or a director, never the plant or the machinery on the floor.
It is repaid when receivables land or the security is refinanced, so a long payment cycle from a major buyer does not translate into a missed super deadline. We release capital against the property and the super is paid from those proceeds, which is a different thing to lending against the equipment itself.
A payday super loan can help you:
- Fund super on the factory payroll while a large order is still unpaid
- Keep super current through a slow receivables cycle
- Meet the 7-business-day deadline without pausing production
- Clear a Superannuation Guarantee Charge owed on shift wages
- Cover super across multiple sites on a single pay run
- Settle an SGC assessment before it becomes a director penalty
Payday super finance for retailers
Retail wage bills climb for peak trading and stock-heavy months, and the super on them falls due before the takings arrive. A payday super loan funds super on payday through that gap. Most retailers lease their space, so the security is usually a director's home or an investment property rather than the shop.
It is repaid out of the trading period the staff were rostered for, or by a refinance once that season is banked. A supplier peak or a seasonal hiring spike stops being a reason to run super late, and the store keeps trading throughout.
A payday super loan can help you:
- Fund super on a payroll that grows for a peak trading season
- Keep super current while cash is tied up in seasonal stock
- Meet the 7-business-day deadline across several store payrolls
- Clear a Superannuation Guarantee Charge before it damages supplier terms
- Cover super on additional seasonal staff without cutting hours
- Settle an SGC already assessed against the business
Payday super finance for transport and logistics operators
Drivers are paid on tight cycles while freight invoices settle on 30 or 60 day terms, so the super on a large driver payroll can fall due well before the run that earned it is paid. A payday super loan funds it on time. We lend against the depot or yard property, or a director's own property, not against the trucks or the trailers.
It is repaid when the freight invoices settle or the security is refinanced, so a long customer payment cycle does not put super behind. We release capital against the property, and super is paid from those proceeds.
A payday super loan can help you:
- Fund super on a driver payroll while freight invoices sit on terms
- Keep super current through a 60-day customer payment cycle
- Meet the 7-business-day deadline on a large transport payroll
- Clear a Superannuation Guarantee Charge before it threatens a contract
- Cover super owed across depots on one pay run
- Settle an assessed charge before the ATO issues a director penalty notice
Payday super finance for wholesalers and distributors
Wholesale ties cash up in imported stock and debtor terms at the same time as a warehouse and sales payroll falls due, so super can land in a week when working capital is fully committed. A payday super loan funds it on time. Security is the warehouse property where the business owns it, or a director's home or investment property where the premises are leased.
It is repaid when debtors pay or a shipment sells through, so a container in transit or a slow-paying account does not push super past the deadline. The stock position and the super obligation stop competing for the same cash.
A payday super loan can help you:
- Fund super on the payroll while cash is tied up in imported stock
- Keep super current while waiting on debtor payments
- Meet the 7-business-day deadline on a warehouse and sales payroll
- Clear a Superannuation Guarantee Charge before it affects credit terms
- Cover super owed while a shipment is still in transit
- Settle an SGC already assessed against the company
Payday super finance for technology companies
Payday super means the superannuation on every pay run has to reach the fund within 7 business days of payday. On a large engineering payroll that is a substantial payment leaving the account every fortnight, and it does not wait for an enterprise invoice sitting on 90 day terms.
The loan funds that super on time and is repaid when the invoice settles or the round closes. A gap between doing the work and being paid for it does not turn into a compliance problem, and the directors are not left personally liable for unpaid super.
A payday super loan can help you:
- Fund super on payday while an enterprise invoice sits on 90 day terms
- Meet the 7-business-day deadline on a fortnightly engineering payroll
- Keep super current through the months before a raise completes
- Clear a Superannuation Guarantee Charge, which is not tax deductible
- Cover super on a payroll that grew faster than the revenue behind it
- Settle an SGC assessment before the directors are pursued for it
Payday super finance for professional and medical practices
Practices carry a salaried team whose super falls due each pay run, while fees and Medicare or client payments arrive on their own cycle, so a slow month can leave super short. A payday super loan funds it on time. These practices usually lease their rooms, so the security is a principal's home or an investment property rather than the premises.
It is repaid when the fee income catches up or the facility is refinanced, so a gap between billing and receipt does not put staff super behind. The team is paid and their super is current while the practice waits to be paid itself.
A payday super loan can help you:
- Fund staff super on payday while fees are still to be collected
- Keep super current through a slow billing cycle
- Meet the 7-business-day deadline on a salaried practice payroll
- Clear a Superannuation Guarantee Charge before it reaches a registration or tender
- Cover super owed while Medicare or client payments settle
- Settle an SGC already assessed against the practice
Payday super finance for real estate and property businesses
Agencies and property businesses run salaried and administrative teams whose super falls due each cycle, while commissions and rent-roll income arrive unevenly across the year. A payday super loan funds super on time. We take security over office property the business owns, or an investment property in the portfolio.
It is repaid when a settlement pays a commission through or the security is refinanced, so a quiet sales month does not put team super behind. The rent roll and the property assets do the work of keeping the payroll compliant.
A payday super loan can help you:
- Fund team super on payday between commission settlements
- Keep super current through a quiet sales month
- Meet the 7-business-day deadline on an agency payroll
- Clear a Superannuation Guarantee Charge before it affects a licence
- Release equity from a portfolio property to cover super owed
- Settle an SGC already assessed against the agency
Payday super finance for property developers
Development cash is locked in a site and its stock until settlement, yet the super on a project and head-office payroll falls due on every pay run in between. A payday super loan funds it on time. We lend against the site, the completed stock, or another property in the portfolio.
It is repaid when the stock settles or a facility takes over, so the long stretch between spending on a project and selling it does not push super past the deadline. Payroll super stays current while capital stays committed to the build.
A payday super loan can help you:
- Fund payroll super while capital is locked in a site and its stock
- Keep super current through the build, before any lot has settled
- Meet the 7-business-day deadline on a project payroll
- Clear a Superannuation Guarantee Charge before it affects a construction drawdown
- Release capital from residual stock to cover super owed
- Settle the charge before an assessment becomes a director penalty
"Payday Super turned a quarterly deadline into one that falls on every pay run, and the charge that follows a missed payment is owed straight to the ATO. We lend against residential, commercial or industrial property, so a business can fund super on payday or clear a charge that has already landed within the same week. In most cases that is faster and cleaner than letting the position drift toward a director penalty notice, and we are happy to run through the numbers with you."
Gino Tabila
Associate Director
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
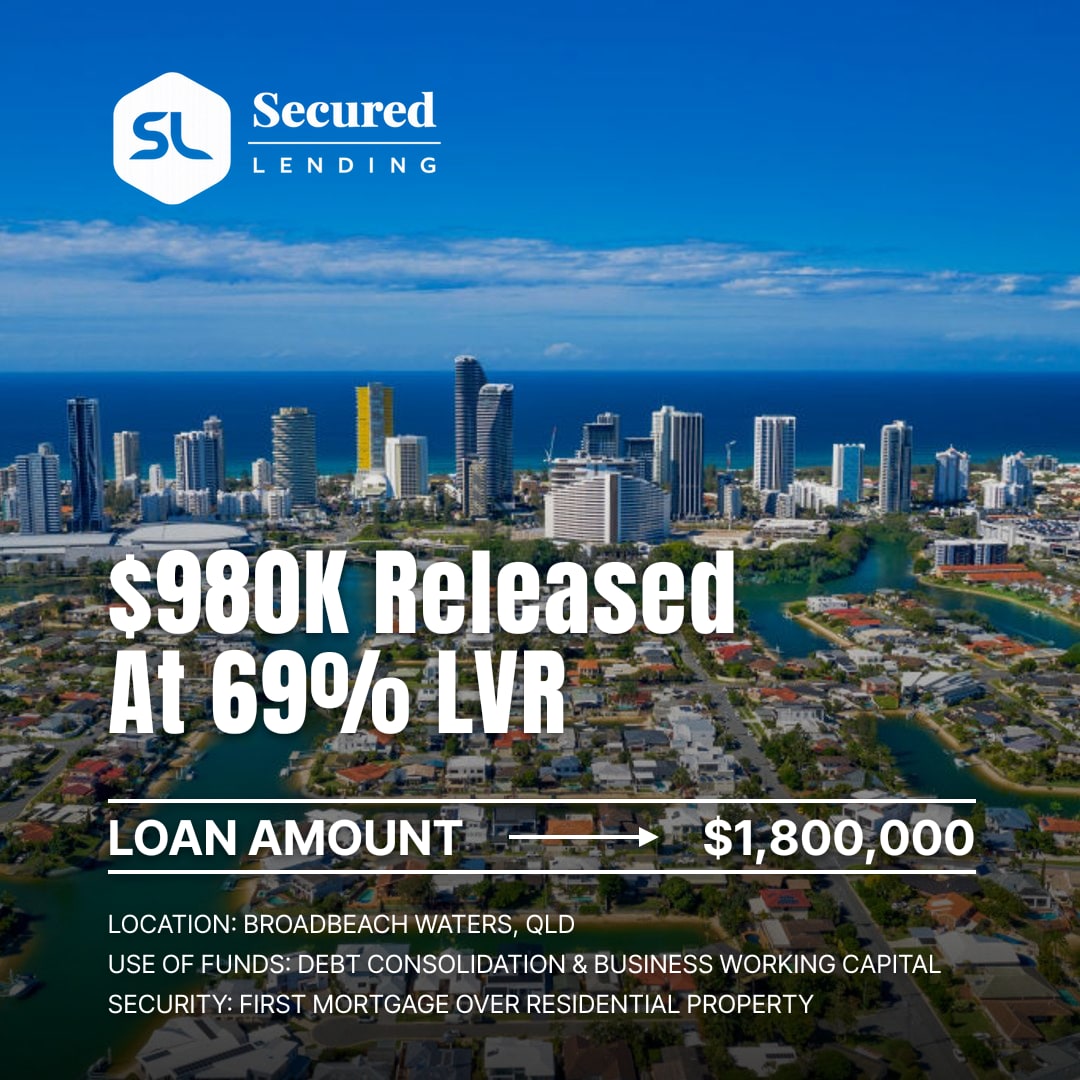
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
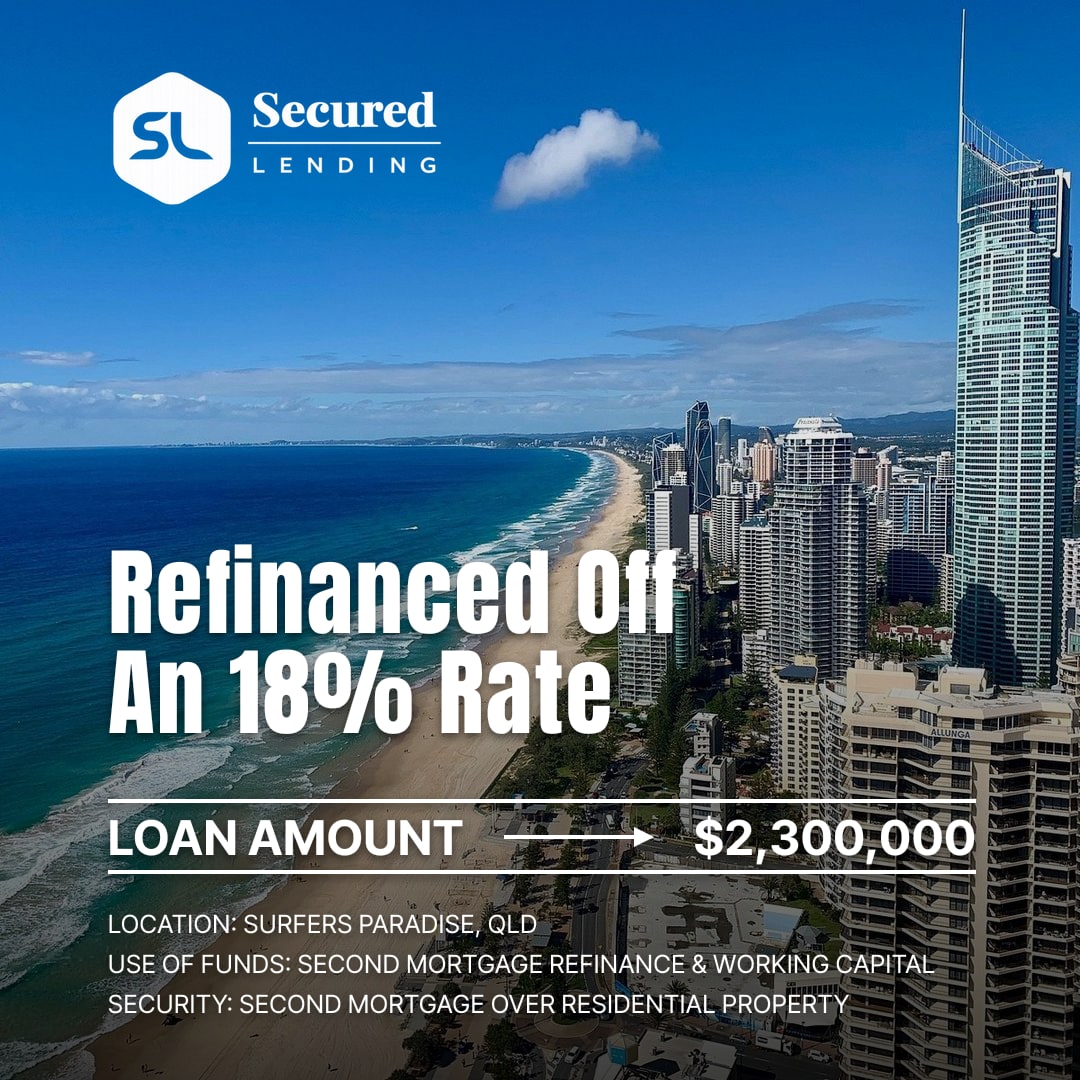
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
Recently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Scenarios We Can Help With
Browse our full range of services, industries, locations, and resources to find the right financial solution for your needs.