Fast Short Term Business Loans
Capital when you need it. No long-term lock-ins.
Experts in strategic, short-term finance
At Secured Lending, we help business owners access fast, practical funding solutions tailored to short-term needs. Our short-term loans are typically 1 to 24 months in duration and are required to be secured against property.
What Are Short Term Loans?
Short term loans are designed to provide businesses with the funds they need to cover short-term financial needs: working capital, unexpected expenses, or time-sensitive investment opportunities. They are typically repaid within 1 to 24 months.
Why Secured Lending?
Our short-term loans are designed for situations where funding is not immediately available from traditional sources such as banks. We pride ourselves on our ability to assess your financial needs in a timely manner and can fund your loan within 24 hours.
- •Finance within 24 hours of approval
- •Loans from $250,000 to $10 million
- •Rates from 9.7% p.a.
- •Terms from 1 to 24 months
- •Secured against residential or commercial property
- •No long-term lock-ins or rigid exit penalties
Common Uses for Short Term Finance
- •Bridging cash flow gaps between invoices or settlement dates
- •Working capital to fund operations, payroll, or supplier payments
- •Urgent tax debt or ATO liabilities requiring immediate resolution
- •Property and real estate: development site acquisitions, auction funding, deposits
- •Business acquisitions, mergers, partner buyouts, or franchise purchases
- •Equipment purchase, machinery finance, or commercial vehicle funding
- •Refinancing expiring loans or exiting restrictive facilities
Short Term Loans for Business Owners With Bad Credit
Short term lending is where a bad credit file matters least, because the loan is repaid from a specific event rather than out of ongoing trading. We look at the property, the equity inside 70% LVR and what retires the debt. Defaults, ATO arrears and prior declines are ordinary on these files. Rates from 9.7% p.a., terms of 1 to 24 months, funded within 24 hours.
Industries We Service
Short term loans for builders and contractors
A short term loan tops up working capital for a defined period, such as the months a progress claim or retention is overdue. It runs for months rather than years, and it is repaid once the job that created the need is finished.
It is repaid by the progress payment, practical completion, or the sale of the security. A builder about to tender does not want a long facility sitting on the balance sheet, and this is the version of that debt which is not still there in three years.
A short term loan can help you:
- Fund a job from mobilisation to final claim, and no longer
- Cover a defined cash flow gap without a multi-year facility
- Keep the balance sheet clean ahead of the next tender
- Repay in full when the contract that created the debt pays
- Borrow for a fixed window rather than an open-ended line
- Clear the facility before the next job is priced
Short term loans for retailers
A short term loan funds a season rather than a decade, secured against a director's home or investment property. The term is set to the trading period the money is actually for.
It is repaid out of the takings from the season the stock was bought for. Retail debt that outlasts the season it was raised for becomes permanent debt, and a fixed end date is what prevents it.
A short term loan can help you:
- Fund one season and clear it from that season's takings
- Borrow across a trading window rather than indefinitely
- Avoid debt that outlives the stock it paid for
- Cover a fit-out and clear it before the next lease review
- Keep a director's property free of a long-dated charge
- Repay in full at the end of a defined term
Short term loans for pubs, hotels and venues
A short term loan is set to the length of the need it funds, whether that is topping up working capital through a quiet season, a refurbishment or a licence purchase. Each of those has an end date, and so does the facility.
It is repaid from the trade the work unlocks, or from the sale of an outgoing venue. A venue carrying long-dated debt is harder to sell and harder to refinance, and a facility with a known end date keeps the freehold clean.
A short term loan can help you:
- Fund a refurbishment and clear it from the season it serves
- Borrow across a defined project rather than indefinitely
- Keep the freehold clean for a future sale or refinance
- Repay from the trade the work was done to generate
- Avoid a long-dated charge over venue property you may sell
- Clear the facility before the next trading year begins
Short term loans for wholesalers and importers
A short term loan is sized to one stock cycle, secured against the warehouse or a director's property. Stock is bought, sold and paid for inside a known window, and the facility matches it.
It is repaid as that stock sells through. Financing a cycle with a permanent facility means paying for capital in the months you are not using it, and a term matched to the cycle does not.
A short term loan can help you:
- Borrow for one stock cycle and repay as it sells through
- Match the term to the shipment rather than to a calendar
- Avoid paying for capital in the months you are not using it
- Clear the facility before the next container is ordered
- Keep the warehouse free of a long-dated charge
- Repay in full without an early repayment negotiation
Short term loans for manufacturers
A short term loan is set to the length of the order it funds, secured against the factory or a director's property.
It is repaid when the customer pays. A single large order does not justify a permanent facility, and a term matched to the delivery and payment cycle means the debt ends when the order does.
A short term loan can help you:
- Fund one order and clear it when the customer pays
- Match the term to the delivery and payment cycle
- Avoid a permanent facility for a one-off order
- Keep the factory free of a long-dated charge
- Clear the debt before the next production run is quoted
- Borrow for the length of a contract, not beyond it
Short term loans for transport and warehousing operators
A short term loan runs for the ramp-up period of a contract, secured against the depot, the warehouse or a director's property.
It is repaid from contract receipts, or by an asset finance facility once the equipment is earning. Standing up a fleet and being paid for using it are months apart, and the facility is written for that, not for years.
A short term loan can help you:
- Fund a contract ramp-up and clear it from the receipts
- Bridge to an asset finance facility rather than replace one
- Match the term to the ramp-up, not to the contract length
- Avoid a long-dated charge over the depot property
- Clear the facility once the fleet is earning
- Borrow without committing the business for years
Short term loans for technology companies
A short term loan runs for weeks or months, until the event that repays it happens: the round closes, the R&D refund is paid, the enterprise invoice settles, or a bank facility arrives.
The facility is discharged as soon as the round, the refund or the invoice pays it out. It is not intended to become the company's long-term debt, and there are no ongoing covenants once it is repaid.
A short term loan can help you:
- Borrow for the eight weeks between a term sheet and the money arriving
- Bridge to an R&D tax incentive refund with a known assessment period
- Cover three months rather than commit to a multi-year facility
- Repay the loan on the day the round completes
- Repay the facility before a due diligence process begins
- Fund a contract that starts in three weeks and pays in five months
Short term loans for property developers
A short term loan runs to the settlement, secured against the site, completed stock, or another property in the portfolio.
It is repaid when the stock settles or a construction facility takes over. Development debt is meant to be temporary by design, and a term set to the settlement rather than to a lender's preference is what keeps it that way.
A short term loan can help you:
- Borrow to a settlement date rather than an open term
- Clear the facility as lots settle
- Avoid debt that outlives the project that created it
- Bridge to a construction facility rather than replace one
- Keep the site clean for a senior lender to fund behind
- Match the term to the programme, not to a credit policy
Short term loans for property investors
A short term loan runs to the sale or the refinance, secured against an investment property or the wider portfolio.
It is repaid when the property settles, or when a longer-term facility takes over. An investor does not want a private facility sitting on the portfolio permanently, and this one is written to come off it.
A short term loan can help you:
- Borrow to a sale date rather than an open-ended term
- Take a private facility off the portfolio once it has done its job
- Fund a renovation and repay on the revaluation or the sale
- Avoid a long-dated charge across several titles
- Bridge to a longer-term lender rather than replace one
- Hold the debt only for as long as the strategy needs it
Short term loans for practices and professional firms
A short term loan runs until the practice facility settles, secured against a director's home or investment property.
It is repaid when that facility settles. It exists to cover a gap of weeks or months, not to become the practice's long-term debt, and it is discharged from the director's property when the permanent lender arrives.
A short term loan can help you:
- Cover the gap until a practice facility settles
- Borrow for weeks or months rather than years
- Take the charge off a director's home once the deal is done
- Clear the facility the day the practice loan lands
- Avoid a private facility becoming permanent practice debt
- Borrow without a covenant that outlasts the transaction
"Short term lending runs smoothest when the objective is clear from day one, and that is a conversation we are happy to lead. Once we understand the LVR, the security, and how the facility will be repaid, we can move quickly on approval and keep everything running cleanly through to the exit."
Gino Tabila
Associate Director
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
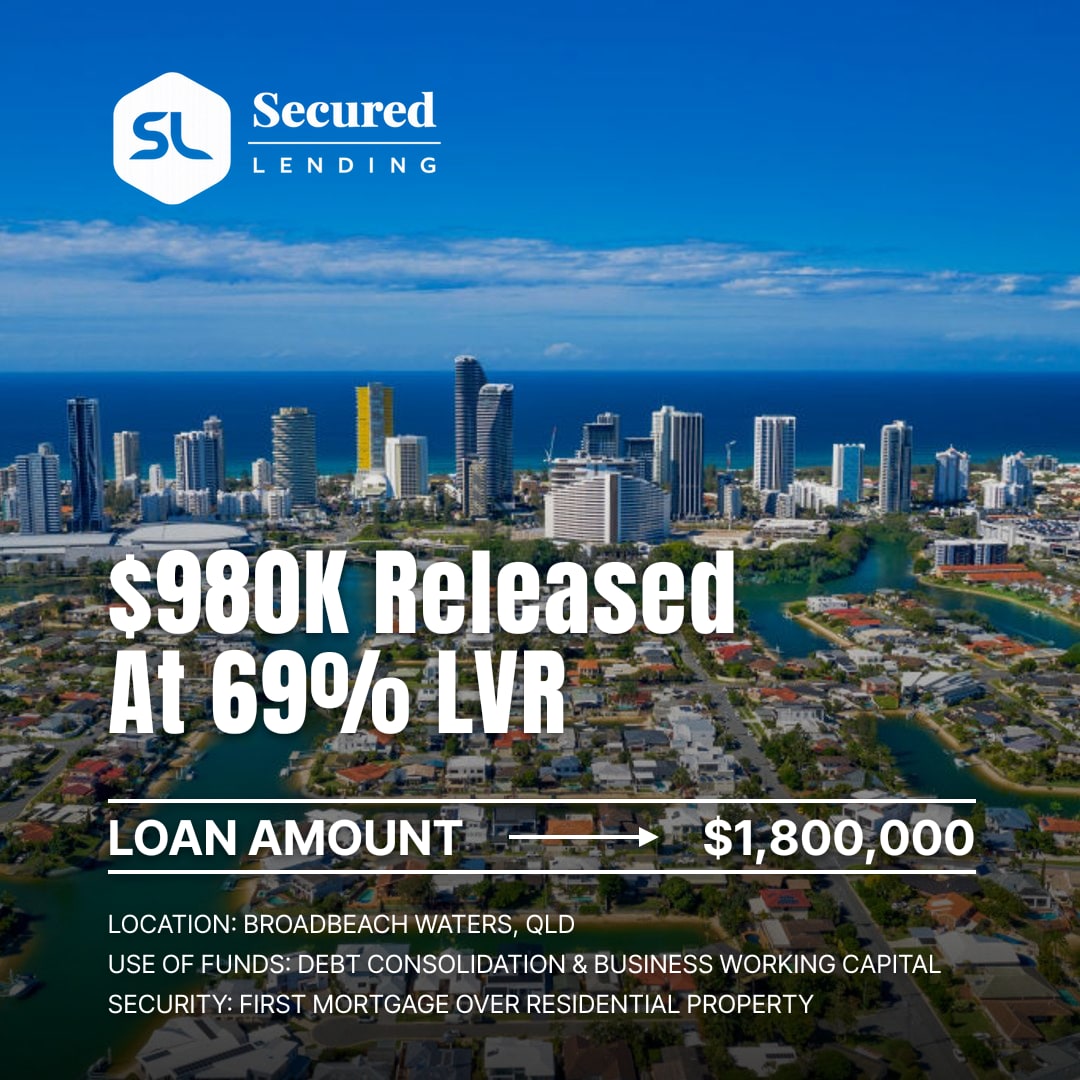
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
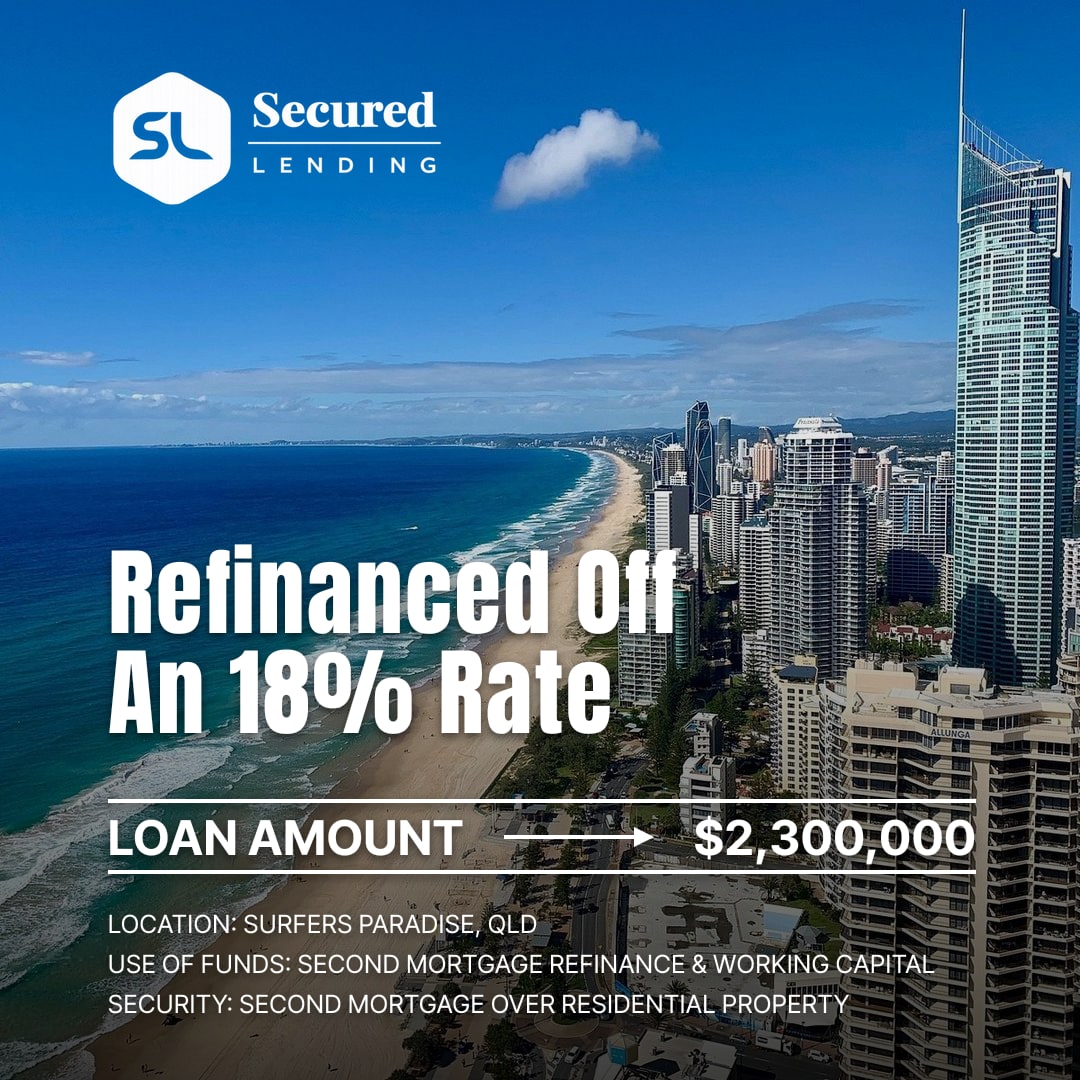
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
Recently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Scenarios We Can Help With
Browse our full range of services, industries, locations, and resources to find the right financial solution for your needs.