Second Mortgage Loans for Business, Funded Fast
Over 200+ second mortgages facilitated. Unlock equity and access capital.
Experts in strategic, short-term finance
What Is a Second Mortgage Private Loan?
A second mortgage is a loan secured by a second-ranking registered charge over your property, sitting behind your existing first mortgage. As a private lender, Secured Lending takes that second mortgage position, giving you access to the equity you have built up, while your first mortgage stays completely untouched.
You don't need to refinance. You don't need to approach your existing bank. And you don't need to meet the same rigid criteria that block most borrowers from accessing capital through traditional channels. Over 200 second mortgages facilitated across Australia.
Who Uses Second Mortgage Private Finance?
You might be a good candidate if:
- •Your existing bank won't lend additional funds against a property that already has a mortgage
- •You need capital quickly and can't wait weeks or months for a formal bank process
- •You're self-employed, operate through a company or trust, or have income that doesn't fit standard serviceability
- •You have ATO debt, a creditor judgment, or an urgent payment obligation that needs to be cleared
- •You want to fund business growth without refinancing your first mortgage at a higher rate
- •Your bank has declined a refinance because you have outstanding tax debt
- •You need to bridge between the sale of a property and the settlement of a purchase
- •You're behind on payments and need to consolidate debt before a formal default notice is issued
Key Features
- •Flexible loan terms: from 1 month to 24 months
- •Fixed interest rates: starting from 11.95% p.a.
- •Loan amounts based on equity: not your credit score
- •No need to refinance: your first mortgage stays untouched
- •Settlement within 24 hours for qualifying applications
Second Mortgage Options for Business Owners With Bad Credit
A second mortgage is often the cleanest answer when credit history is the problem, because your first mortgage stays exactly where it is. We take a second registered mortgage over the property and lend against the equity above the first, to a combined 70% LVR. Defaults and arrears do not block that. Rates start from 11.95% p.a., and no full financials are needed on an asset-backed file.
Industries We Service
Second mortgage finance for property investors
A second mortgage sits behind the first mortgage already on your investment property, which stays exactly where it is. There is no refinance, no discharge of the existing facility, and no break costs on a rate you would rather keep.
It is repaid when the property sells, or by a refinance once the whole position can be restructured. It is the product for an investor holding equity behind a cheap first mortgage that would be expensive to disturb.
A second mortgage can help you:
- Release equity without discharging your existing first mortgage
- Keep a low first mortgage rate you would rather not lose
- Fund a deposit on the next purchase before the current one sells
- Avoid break costs on a fixed facility
- Borrow behind the first across one title or several
- Exit by sale, or by a refinance of the whole position
Second mortgage finance for pubs, hotels and venues
A second mortgage sits behind the first mortgage on the venue, which stays in place. The existing lender is not disturbed, the facility is not refinanced, and the venue keeps trading as normal.
It is repaid when an outgoing venue sells, or by a refinance once the trading figures support one. It suits an operator with real equity in a freehold and a first mortgage worth keeping.
A second mortgage can help you:
- Release equity in the venue without touching the first mortgage
- Fund a second site while the first stays financed as it is
- Pay for a refurbishment or a fit-out in the off season
- Keep an existing lender and an existing rate in place
- Trade as normal for the life of the facility
- Exit by sale, or by a refinance once the figures support it
Second mortgage finance for builders and contractors
A second mortgage sits behind the first mortgage on the yard, the office or a director's property, and the existing facility stays untouched.
It is repaid by the progress payment, practical completion, or the sale of the security. It is the right product when the equity is there but the first mortgage is not worth breaking to reach it.
A second mortgage can help you:
- Reach equity in the yard without refinancing the first mortgage
- Pay wages and subcontractors while a claim sits unpaid
- Fund the next contract behind a first mortgage you keep
- Keep an existing facility and its rate in place
- Cover a retention released late, or a disputed variation
- Exit by the progress payment, completion, or a sale
Second mortgage finance for property developers
A second mortgage sits behind the construction facility or the first mortgage already on the site, both of which stay in place. It is the top-up, not the replacement.
It is repaid when the stock settles or the senior facility is retired. It closes an equity gap that would otherwise stall a project, without renegotiating a senior debt that is already working.
A second mortgage can help you:
- Close an equity gap without renegotiating the senior facility
- Sit behind a construction facility that stays in place
- Fund holding costs while approvals are finalised
- Cover a cost overrun late in a project
- Buy out a partner behind a senior facility that stays in place
- Exit when the stock settles, or the senior debt is retired
Second mortgage finance for manufacturers
A second mortgage sits behind the first mortgage on the factory, which stays in place. The senior lender is not disturbed and the plant does not stop.
It is repaid when the customer pays, or by a longer-term facility once the order is delivered. It is how equity in a factory becomes working capital without refinancing a facility that is already priced well.
A second mortgage can help you:
- Reach equity in the factory without refinancing the first
- Fund materials and tooling on an order paid for on delivery
- Take on an order that would strain the working capital line
- Leave a well-priced factory mortgage exactly as it is
- Buy plant without disturbing the senior debt
- Exit by the customer payment, or a longer-term facility
Second mortgage finance for transport and warehousing operators
A second mortgage sits behind the first mortgage on the depot or warehouse, which stays exactly as it is.
It is repaid from contract receipts, an asset finance takeout, or a refinance. It funds a ramp-up without touching a senior facility that is already in place over the site.
A second mortgage can help you:
- Reach equity in the depot without refinancing the first
- Fund trucks, trailers or racking for a new contract
- Bridge the gap between winning the work and being paid
- Leave the depot's senior facility exactly as it is
- Upgrade the fleet without refinancing the depot mortgage
- Exit by contract receipts, or an asset finance takeout
Second mortgage finance for wholesalers and importers
A second mortgage sits behind the first mortgage on the warehouse, or on a director's property where the premises are leased. The existing facility stays in place.
It is repaid as the stock sells through, or when a debtor facility takes over. It puts equity behind a shipment without refinancing a facility that is doing its job.
A second mortgage can help you:
- Reach equity without refinancing the first mortgage
- Fund a shipment behind a warehouse mortgage that stays in place
- Accept a large order that cash flow alone would not carry
- Leave a warehouse mortgage undisturbed while borrowing behind it
- Cover duty and freight behind a first mortgage that stays in place
- Exit by sell-through, or a debtor facility
Second mortgage finance for retailers
A second mortgage sits behind the first mortgage on a director's home or investment property, which stays in place. Most retailers lease their space, so this is the usual way equity is reached.
It is repaid out of the season the stock was bought for, or by a refinance once the trading period is banked. The existing home loan is not refinanced and its rate is not lost.
A second mortgage can help you:
- Reach equity in a director's property without refinancing it
- Order a season's stock months before the takings arrive
- Take a discount without refinancing the home loan to fund it
- Keep an existing home loan and its rate in place
- Pay for a fit-out or a new site up front
- Exit by the season's takings, with the first mortgage untouched
Second mortgage finance for technology companies
A second mortgage sits behind the facility already in place, which stays exactly where it is. It funds a hire, a bolt-on acquisition or a tax position without disturbing a home loan or a commercial facility on a rate that is no longer available.
It is repaid when the round closes, the R&D refund is paid, or the company refinances the whole position. Releasing capital does not require refinancing the existing debt, so a rate fixed three years ago stays in place.
A second mortgage can help you:
- Release equity for an engineering hire without refinancing a fixed home loan
- Avoid break costs on a facility written at a rate no longer available
- Borrow behind an existing lender that will not increase its facility
- Fund a bolt-on acquisition while the existing facility stays untouched
- Clear an ATO debt without refinancing the existing first mortgage
- Keep an existing commercial facility in place while the company grows
Second mortgage finance for practices and professional firms
A second mortgage sits behind the first mortgage on a director's home or investment property, which stays in place. These firms almost always lease their rooms, so the director's property is the security.
It is repaid when the long-term practice facility settles. It funds a transaction on the vendor's timetable without refinancing the director's home loan to do it.
A second mortgage can help you:
- Borrow behind a home loan without disturbing the practice's debt
- Fund a buy-in behind a home loan that stays exactly as it is
- Acquire a book without refinancing the director's home loan
- Avoid break costs on a fixed home loan
- Pay out a departing partner without touching the first mortgage
- Exit by refinancing the whole position, first mortgage included
Second mortgage finance for childcare operators
A second mortgage sits behind the bank loan already on the centre property or on a director's home or investment property, and that loan stays exactly where it is. It funds payroll while Child Care Subsidy payments are on their way, the deposit on a second centre, or fit-out works, without breaking the existing facility.
It is repaid by a refinance of the combined group once both centres are trading, from trading income, or by a sale of property. An operator with one centre trading well can buy the next one without refinancing the loan it already has.
A second mortgage can help you:
- Release equity for a second centre while the first centre's loan stays in place
- Meet payroll before subsidy payments arrive, without breaking your bank loan
- Fund fit-out and opening costs behind a construction or bank loan
- Buy the centre you lease from the landlord, behind your existing home loan
- Clear an ATO balance without refinancing the loan on the centre
- Refinance both centres together once they are trading
Second mortgage finance for medical, dental and allied health practices
A second mortgage sits behind the existing bank loan, which stays exactly where it is, so a practice can fund the purchase of a retiring principal's practice, a departing partner's shares or a fit-out without refinancing that loan. It can also consolidate several business debts into one.
It is repaid by longer-term finance once the new rooms or the new ownership have trading on record, or by a bank refinance. A dental practice in Plenty, Victoria, received a $300,000 second mortgage within 5 business days to fund working capital and consolidate debts, with its first mortgage left in place and a major bank refinance as the exit.
A second mortgage can help you:
- Buy a retiring principal's practice without refinancing your bank loan
- Pay out a departing partner's shares behind the existing first mortgage
- Fit out a procedure room or a second surgery while the bank loan stays in place
- Consolidate several practice debts into one loan behind the first mortgage
- Pay for dental chairs or imaging equipment without disturbing the first mortgage
- Move to a major bank refinance once the practice has trading on record
Second mortgage finance for waste and recycling companies
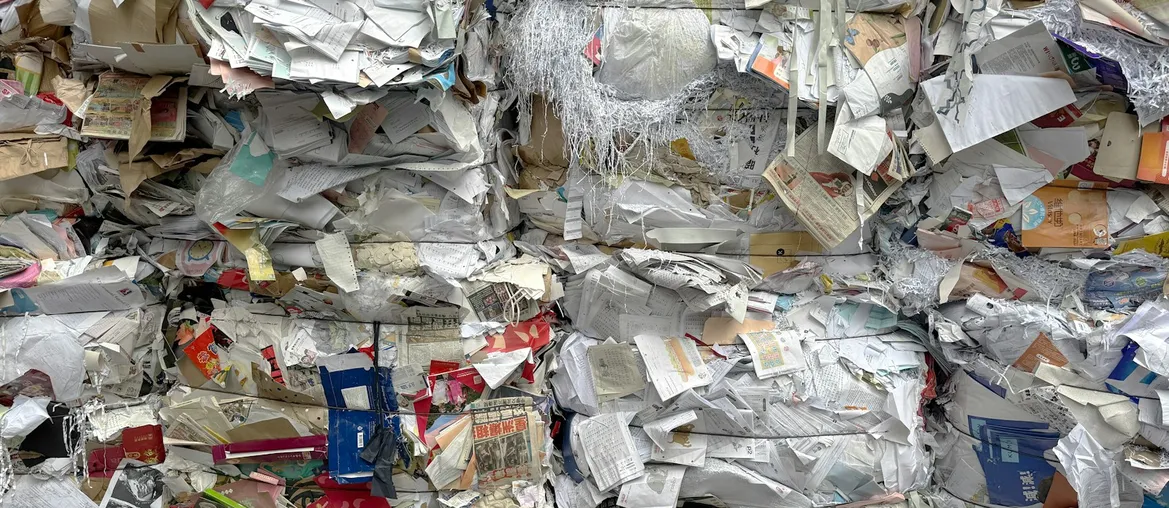
A second mortgage sits behind the existing first mortgage over the depot, transfer station or recycling site property, or a director's home or investment property, and that first loan stays in place. It funds a baler, a shredder, new trucks or the start of a new collection contract, and we lend against the property, never against the plant, the trucks or the bins.
It is repaid from contract income, trading income or a refinance. A collection company can start a council contract on the date in the tender without refinancing the loan already on its depot property.
A second mortgage can help you:
- Buy a baler or sorting line while the first mortgage stays in place
- Fund trucks and bins for a new council contract behind your existing loan
- Cover wages and tip fees during a late council payment without refinancing
- Pay consultant and audit costs on a former industrial site
- Clear an ATO debt before a tender checks your tax compliance
- Refinance the first and second mortgages together once the contract is paying
Second mortgage finance for mining services companies
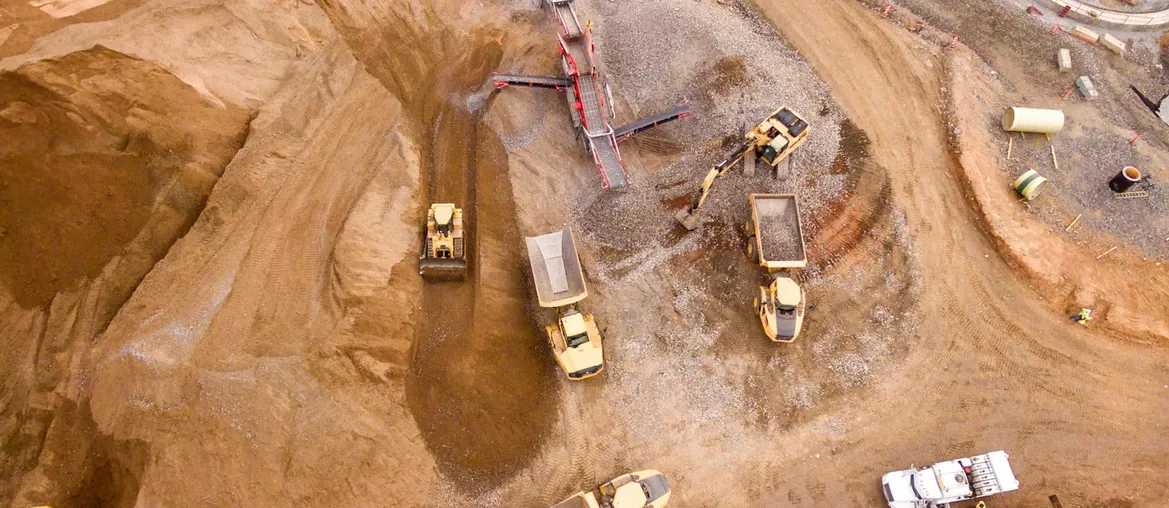
A second mortgage sits behind the existing first mortgage over a yard, depot, workshop or camp property, or a director's home or investment property, and the first loan stays exactly where it is. It funds crews, travel and parts for a new contract, or another drill rig or excavator, and we lend against the property, never against the equipment or the contract.
It is repaid from dated contract payments once they are documented, or by a refinance once the contract has a payment history. Our own valuers assess property in regional and remote towns where there is a realistic market for it, so a location near the mine affects the amount rather than ruling the loan out.
A second mortgage can help you:
- Pay for crews and travel before the first contract invoice is paid
- Buy another rig or excavator behind the loan on your depot property
- Add rooms to a freehold camp while the first mortgage stays in place
- Pay wages and fuel while a head contractor's invoices are outstanding
- Release equity in a workshop property in a regional mining town
- Repay from documented contract payments or a refinance
"Second mortgage lending comes down to understanding the full debt stack, and that is work we enjoy. We look at the first mortgage balance, the combined LVR across both positions, and whether the equity buffer comfortably supports the facility. Where the underlying security is strong and the exit is clear, we can often have funds in place within the same week."
Gino Tabila
Associate Director
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
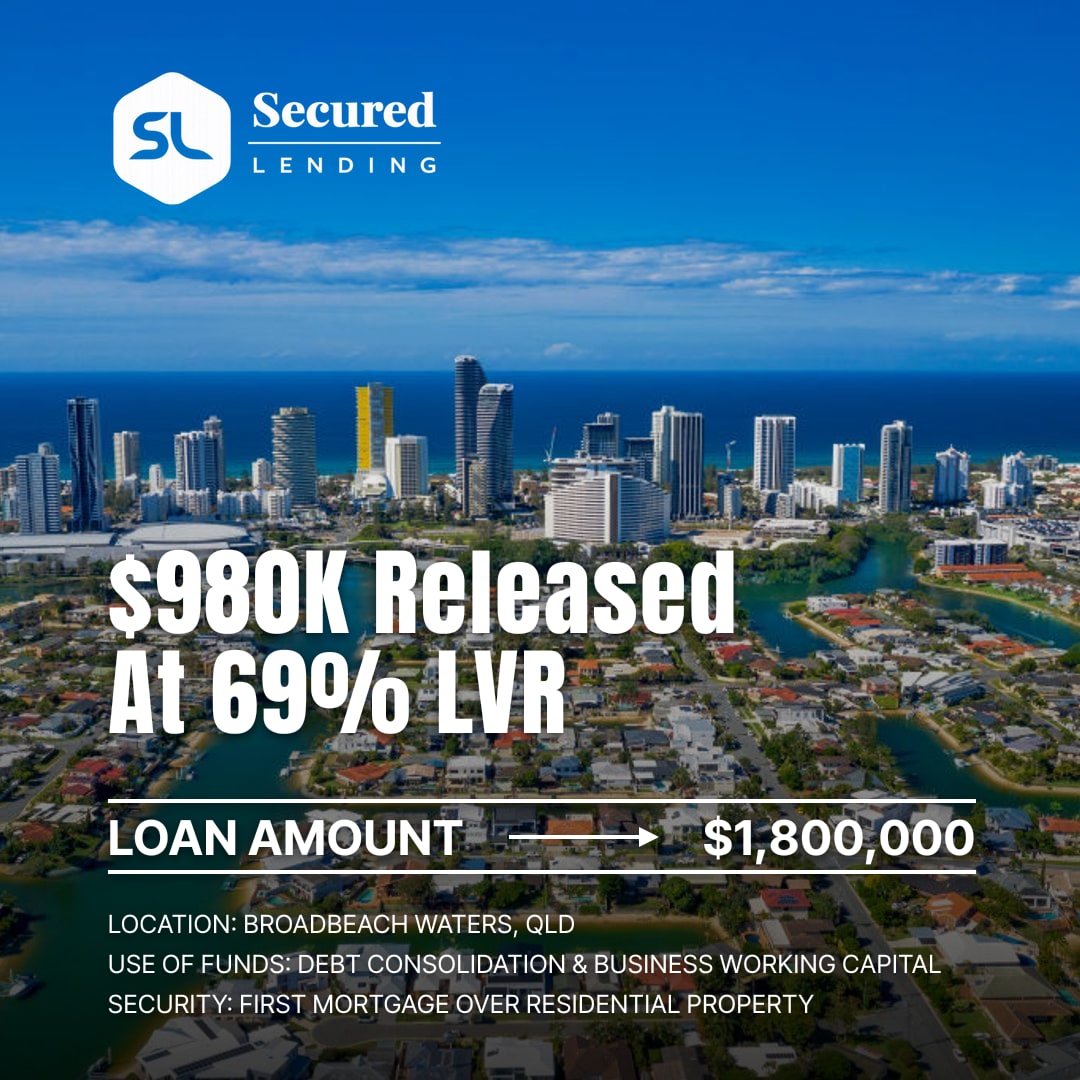
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
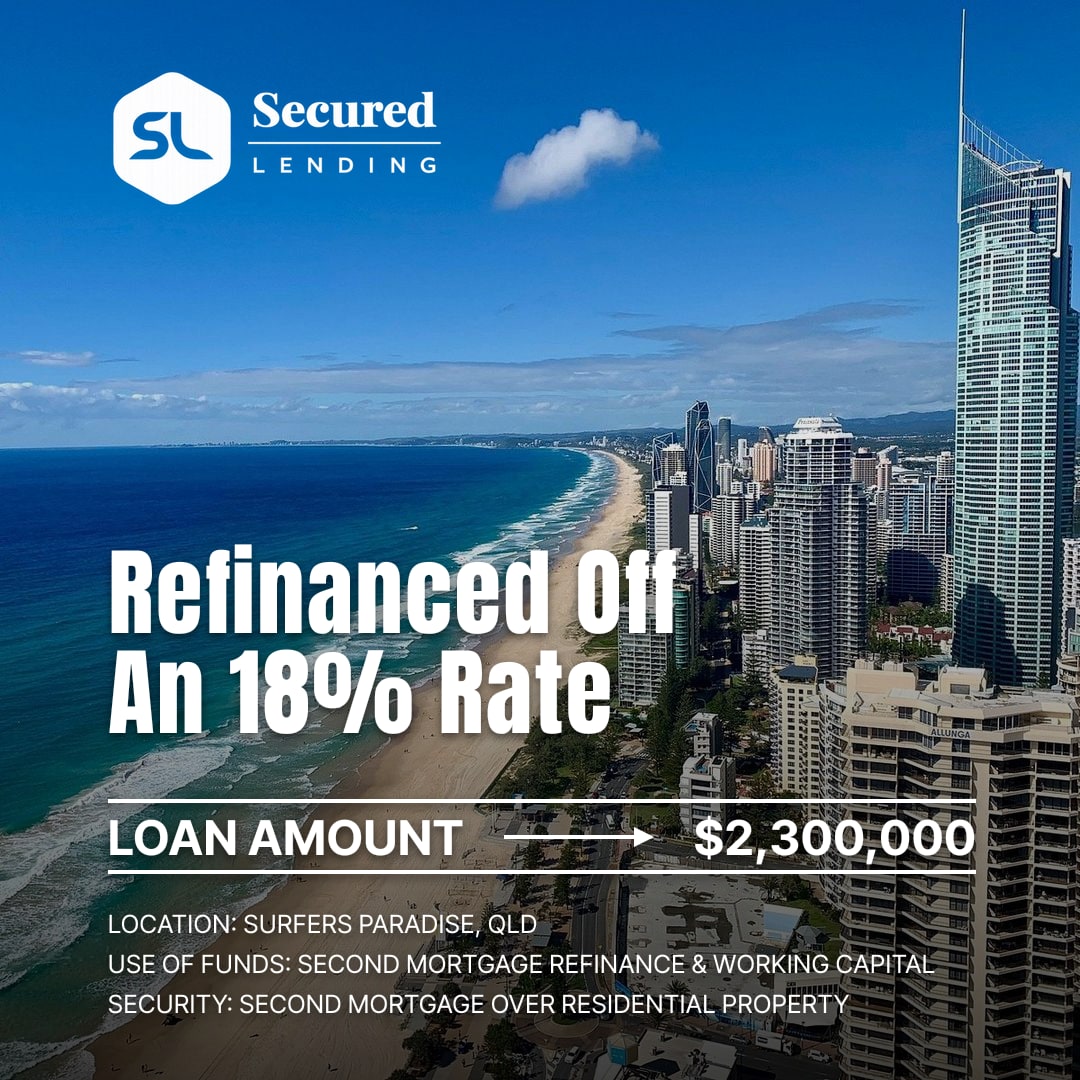
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
Recently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Scenarios We Can Help With
Browse our full range of services, industries, locations, and resources to find the right financial solution for your needs.