Secured Business Line of Credit, Funded Fast
Bridge the gap fast with flexible finance, secured against property
Experts in strategic, short-term finance
As a private lender, our flexible, short-term BLOC is structured to give you financial agility when you need it most. You can draw funds as you go to seize opportunities, manage urgent tax debt, or cover any unexpected cash flow gap.
Key Features of the Short-Term BLOC
- •Revolving flexibility: draw down, repay, and redraw within the term
- •Terms from 6 to 18 months
- •Secured by a second mortgage only, with a maximum LVR of 70%
- •Access capital up to $2,000,000
- •Fast assessment and settlement to meet critical deadlines
Real-World Use Cases
This product is specifically designed to solve immediate, time-sensitive funding problems:
- •Construction companies bridging delayed progress payments: draw to cover payroll and suppliers, repay when the progress claim clears
- •Seasonal retailers funding bulk inventory ahead of peak demand when working capital is tied up in a pending settlement
- •Trading companies funding a DOCA contribution against director property equity to exit voluntary administration
- •Business owners managing urgent tax debt or BAS liabilities while waiting on revenue
- •Borrowers needing a revolving facility while a longer-term refinance or sale is in motion
Costs
Pricing is confirmed in writing before you commit.
A Business Line of Credit With Bad Credit on File
A line of credit is usually the first thing a bank pulls when your file turns. We can put one back in place, secured by a second mortgage over property to 70% LVR, with pricing confirmed in writing before you commit. Credit history is not the gate here. Equity is, and so is a clear reason for the facility.
Industries We Service
A business line of credit for retailers
A line of credit is a revolving facility secured against a director's home or investment property. You draw what you need when you need it, repay it as the takings come in, and the limit is there again for the next order.
You only pay for what you actually use, which is what makes it suit a trading year that is not flat. The facility stays in place across seasons, so a stock order does not need a new application every time.
A line of credit can help you:
- Draw for a season's stock and repay as the takings arrive
- Take a supplier discount without arranging a new facility
- Cover rent and wages through a quiet quarter
- Pay only for the portion of the limit you actually use
- Keep a limit in place across seasons, not just one order
- Restock quickly after a strong trading period
A business line of credit for wholesalers and importers
A line of credit is a revolving facility secured against the warehouse, or a director's property where the premises are leased. You draw to pay for a shipment and repay as the stock sells through.
You only pay for what you use, and the limit is available again for the next container. It is built for a business whose funding need repeats every cycle rather than arriving once.
A line of credit can help you:
- Draw for each container and repay as the stock sells through
- Cover customs, freight and storage as they fall due
- Commit to a bulk buy without a new application each time
- Carry no cost in the weeks between containers
- Keep a limit available across a whole container programme
- Bridge the gap between paying a supplier and being paid
A business line of credit for builders and contractors
A line of credit is a revolving facility that tops up working capital each time a progress claim or retention is paid late. You draw on it to pay wages and suppliers while a claim is outstanding, and repay when the payment is made.
You only pay for what you use, and the limit resets for the next claim. It matches the way a builder's cash flow actually behaves, which is a cycle rather than a single event.
A line of credit can help you:
- Draw against an unpaid progress claim and repay when it lands
- Cover wages and subcontractors across the payment cycle
- Fund mobilisation on the next job without a new application
- Carry no cost in the weeks a claim is paid on time
- Keep a limit in place across several contracts
- Absorb a late retention without stopping work
A business line of credit for software and technology companies
A line of credit is a revolving facility the company draws against as it needs it and repays as invoices are collected. It is fee-based, so there is no interest rate, and no cost at all in the months nothing is drawn.
That suits a business whose receipts are uneven even when the work is steady, which is normal in enterprise software and services. The limit stays in place across the financial year rather than being applied for each time it is needed.
A line of credit can help you:
- Draw as invoices are issued and repay as customers settle them
- Cover payroll in the weeks between milestone payments
- Pay fees only on what is actually drawn
- Fund a quarterly cloud commitment and clear it in the same quarter
- Keep a limit available for an acquisition that has not been identified yet
- Absorb one large customer paying late without cutting the development schedule
A business line of credit for manufacturers
A line of credit is a revolving facility secured against the factory property. You draw for materials on an order and repay when the customer pays.
You only pay for what you use, and the limit is there again for the next order. It is the facility for a business whose working capital need moves with the order book.
A line of credit can help you:
- Draw for materials on an order and repay when the customer pays
- Take on a large order without arranging a new facility
- Cover a long payment cycle on a supply contract
- Carry no cost between production runs
- Keep a limit available as the order book moves
- Buy consumables and tooling as they are needed
A business line of credit for pubs, hotels and venues
A line of credit is a revolving facility that tops up working capital in the quiet months, when takings fall but wages and supplier bills do not. You draw on it in the off season and repay through the busy one.
You only pay for what you use, so the facility costs little in the months you do not need it. In a business whose trade is seasonal, that is exactly what the facility is for.
A line of credit can help you:
- Draw through the quiet months and repay through the busy ones
- Cover wages and suppliers in a slow trading week
- Fund a refurbishment in stages rather than in one hit
- Carry no cost in the months the venue is busy
- Keep a limit in place across a whole trading year
- Stock up ahead of an event or a holiday period
A business line of credit for transport and warehousing operators
A line of credit is a revolving facility secured against the depot or warehouse property. You draw as a contract ramps up and repay from the receipts as it runs.
You only pay for what you use, and the limit is available again for the next contract. Fuel, tyres and maintenance do not arrive on a schedule, and neither does a facility that has to be applied for each time.
A line of credit can help you:
- Draw as a contract ramps up and repay from its receipts
- Cover fuel, tyres and maintenance as they fall due
- Cover a payment gap that recurs on every contract, not just one
- Carry no cost while the fleet is fully utilised
- Keep a limit available across several contracts
- Absorb a late payment without parking trucks
A business line of credit for practices and professional firms
A line of credit is a revolving facility secured against a director's home or investment property. You draw as the practice needs it, and repay from fees as they are billed and collected.
You only pay for what you use, which suits a practice whose receipts are lumpy even when the work is steady.
A line of credit can help you:
- Draw against work in progress and repay as fees are collected
- Cover PAYG, superannuation and rent between billing cycles
- Fund equipment or a fit-out in stages
- Carry no cost in the months fees arrive on time
- Keep a limit in place across a financial year
- Absorb a slow-paying client without pressuring the partners
A business line of credit for property developers
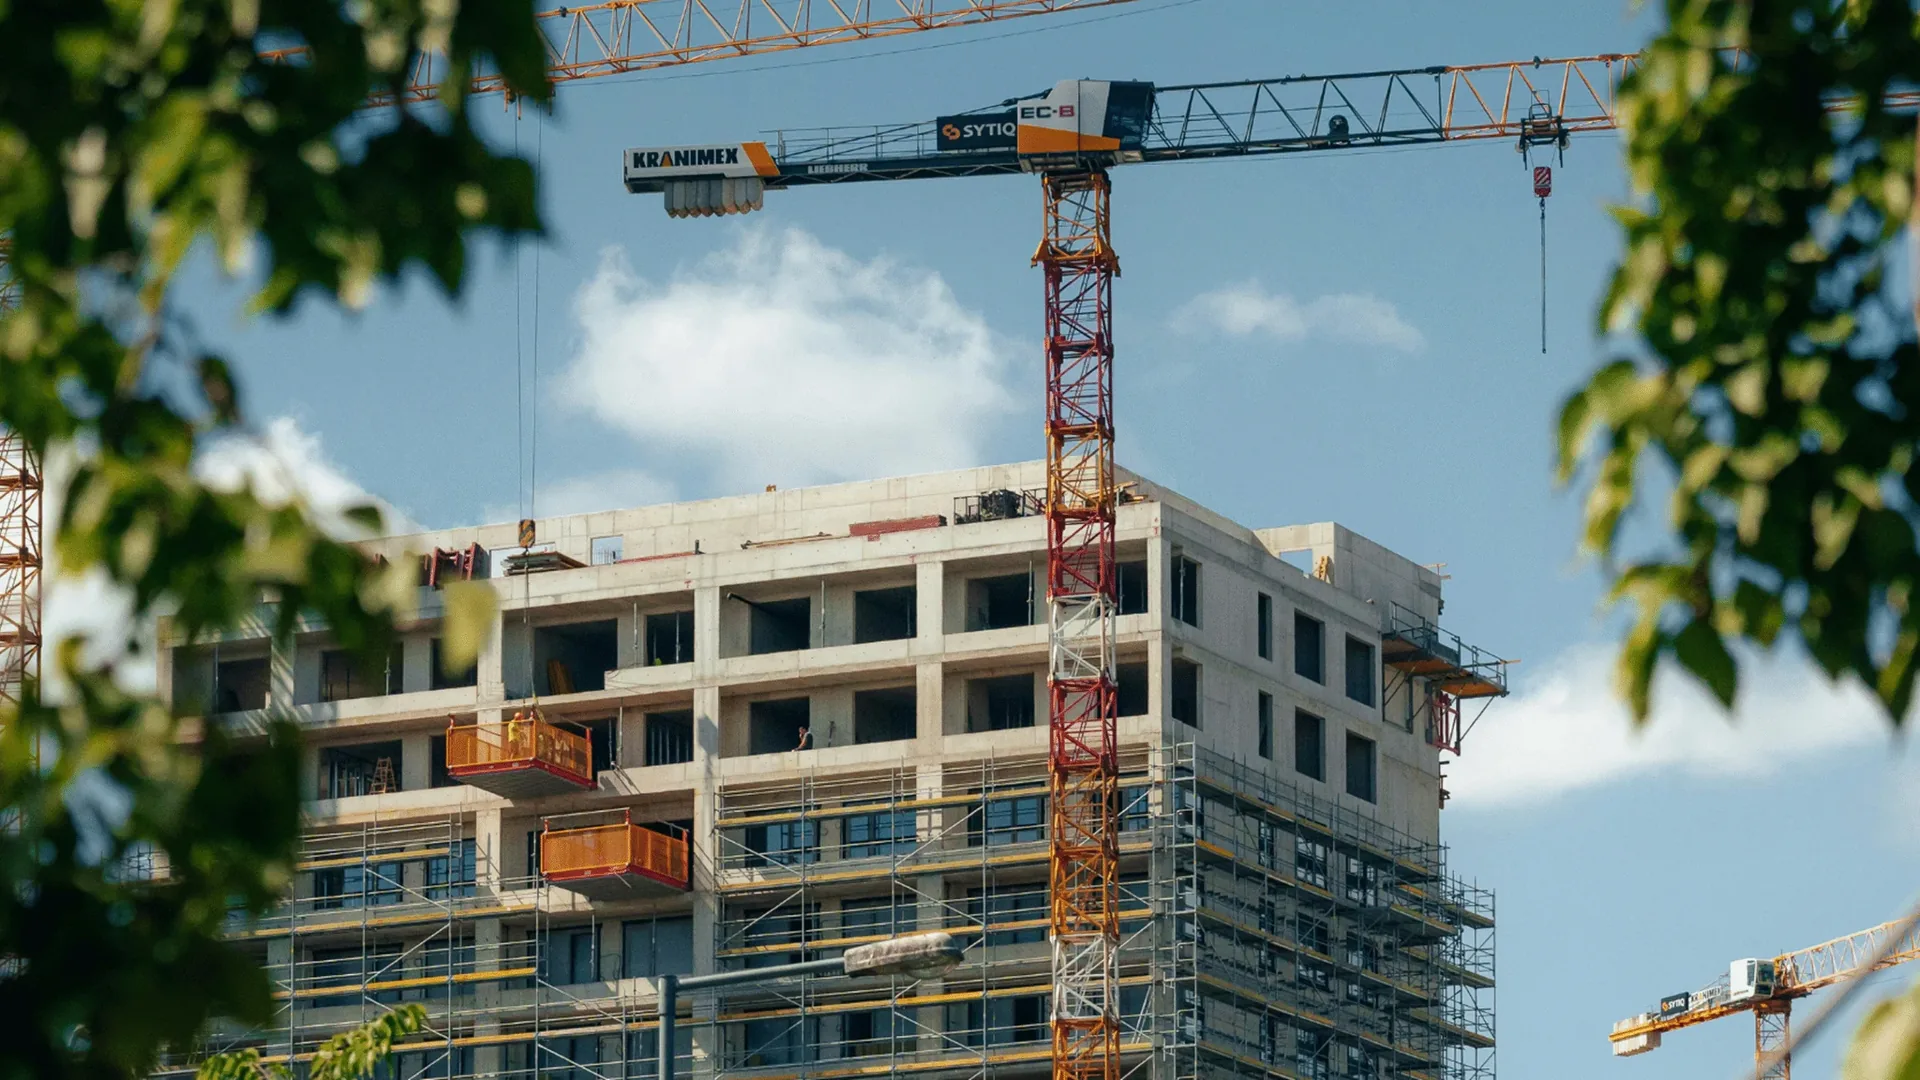
A line of credit is a revolving facility secured against a site, completed stock, or another property in the portfolio. You draw for holding costs and repay as lots settle.
You only pay for what you use, and the limit is available again for the next stage. It suits the costs a project carries continuously, rather than the ones it incurs once.
A line of credit can help you:
- Draw for holding costs and repay as lots settle
- Cover rates, insurance and consultants across a project
- Fund the deposit on the next site without a new application
- Carry no cost between project stages
- Keep a limit available across the life of a project
- Absorb a delayed settlement without stalling the programme
A business line of credit for property investors
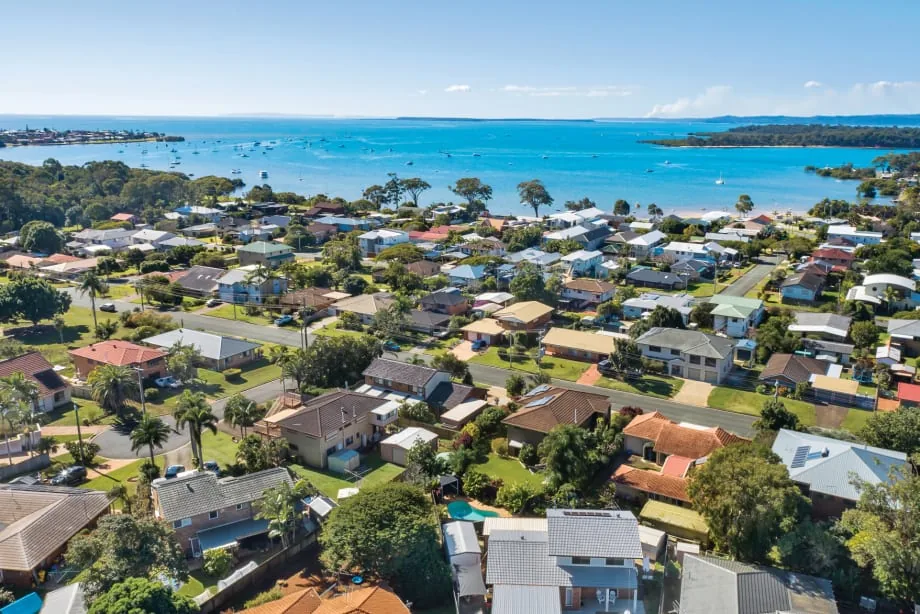
A line of credit is a revolving facility secured against an investment property or the wider portfolio. You draw when an opportunity comes up, and repay when a property sells or refinances.
You only pay for what you use, so an investor can hold a deposit-ready limit without paying to keep it idle.
A line of credit can help you:
- Hold a deposit-ready limit without paying to keep it idle
- Draw for an auction deposit and repay on settlement
- Fund a renovation in stages as the work is done
- Cover rates, strata and vacancy between tenancies
- Carry no cost while the limit sits unused
- Keep a limit available across the whole portfolio
"A secured line of credit against property gives a business ready access to capital without having to go back to a lender every time an opportunity moves. Inside 70% LVR, we can structure the facility quickly so it is there to draw on as needed. For businesses that move fast, that standing access to capital is a genuine edge, and we are happy to set it up to suit how you operate."
Gino Tabila
Associate Director
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
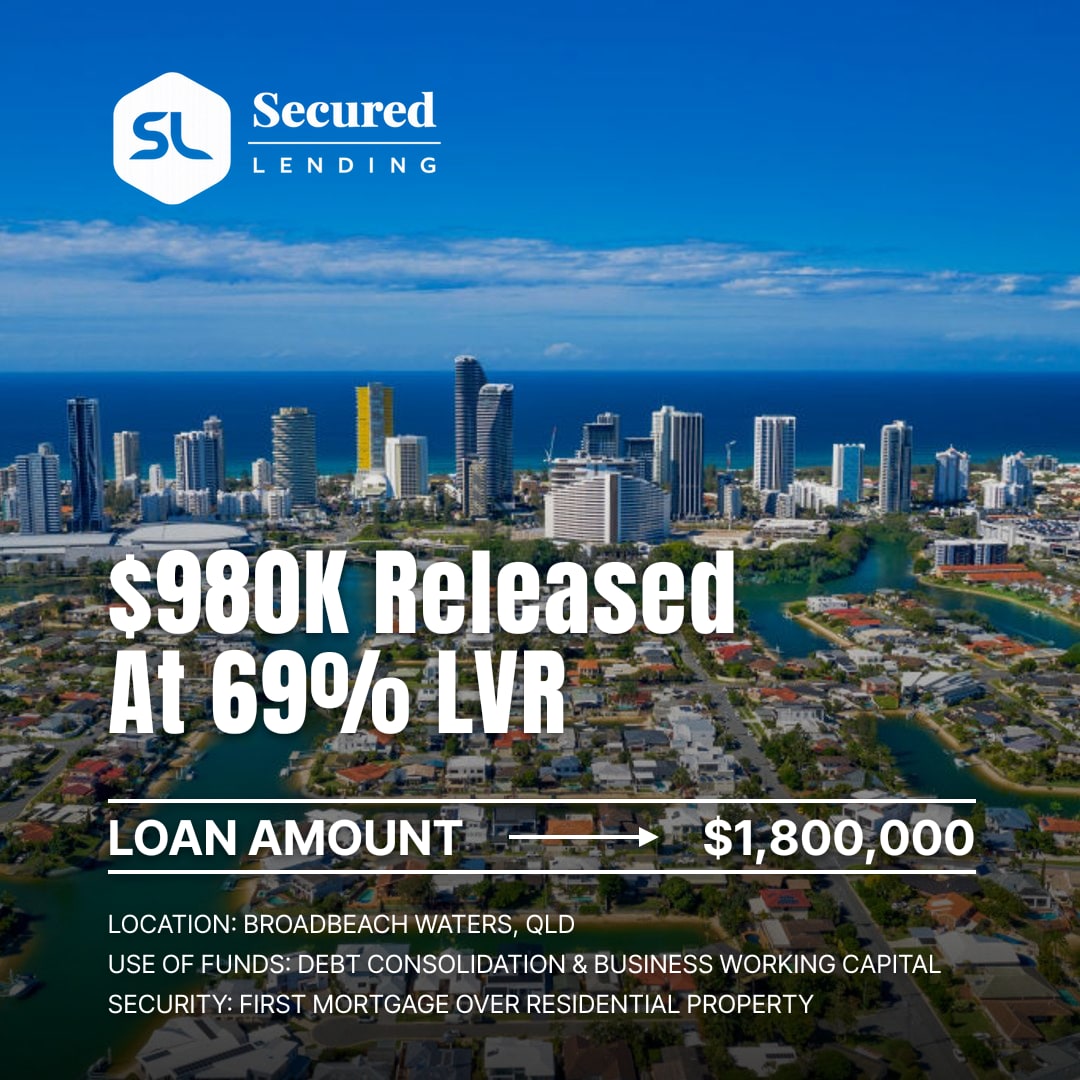
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
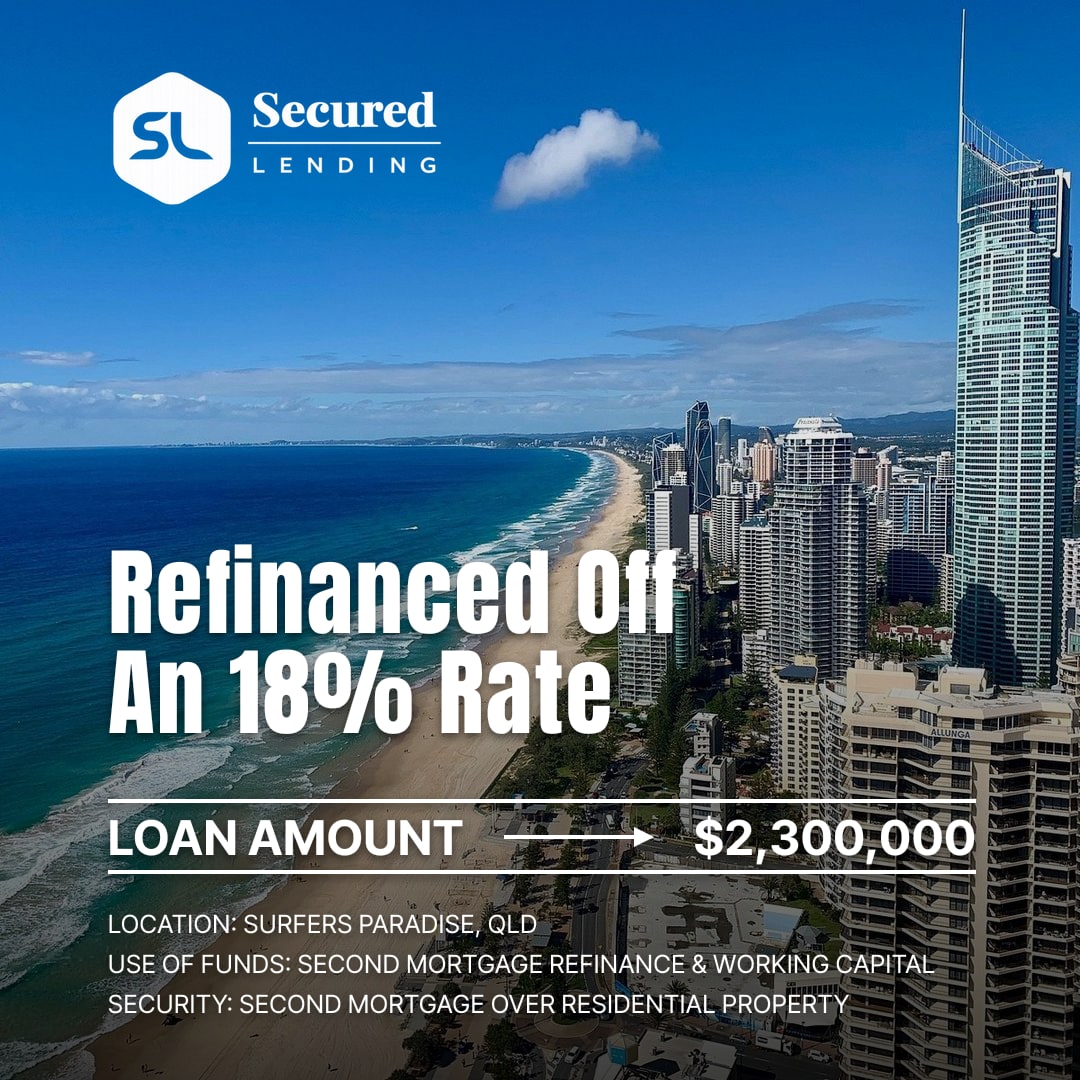
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
Recently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Scenarios We Can Help With
Browse our full range of services, industries, locations, and resources to find the right financial solution for your needs.