Secured Debt Consolidation Loans, Funded Fast
Simplify repayments. Lower costs. Regain cash flow.
Experts in strategic, short-term finance
What is a Secured Debt Consolidation Loan?
A secured debt consolidation loan allows a business to combine multiple existing debts, often high-interest short-term facilities, into one structured loan backed by real property. Businesses often accumulate debts through equipment finance, merchant cash advances, unsecured lines of credit, or short-term facilities with varying interest rates and payment schedules.
By consolidating these debts into one property-secured loan, Secured Lending helps clear the slate. With one lender, one repayment schedule, and typically a lower blended interest rate, businesses can:
- •Reduce interest costs by replacing high-rate facilities
- •Streamline repayments into a single manageable loan
- •Align a single repayment schedule with your cash flow cycle
- •Avoid defaults or arrears caused by scattered repayment schedules
Why Businesses Choose Secured Lending
- •Loan sizes from $250,000 to $10 million: tailored for SMEs through to large-scale operators
- •Fast turnaround: funding possible in as little as 24 hours
- •Sydney-based private lender: decisions made locally, without bank bureaucracy
- •Proven track record: more than $500 million in loans facilitated
Common Situations Where We Help
- •Businesses juggling multiple short-term facilities at high rates
- •Cash flow shortfalls caused by customer payment delays
- •High-rate facilities compounding faster than the business can clear them
- •Expansion opportunities stalled due to scattered repayments
Consolidation assumes you still hold the timetable. Where a payout figure is climbing, a lender has issued a notice, or the ATO has started recovery action, the work is a restructure instead, and the order the debts are cleared in starts to matter as much as the rate.
Debt Consolidation for Business Owners With Bad Credit
By the time a business is running four facilities at four rates, the credit file usually shows it. Missed payments, defaults, a judgment or two. That history is what stops a bank consolidating the debt, and it is not what we assess. We lend against the property, roll the facilities into one position inside 70% LVR, and do it without full financials on an asset-backed file.
Industries We Service
Debt consolidation for pubs, hotels and venues
A debt consolidation loan rolls the facilities a venue has accumulated into one loan, secured against the venue or a director's property where it is leasehold. The equipment finance, the merchant advance, the ATO plan and the cards become a single facility with a single repayment.
It is repaid when a venue sells, or by a refinance once the trading figures support one. The gain is not only cost, it is that one repayment on a known date is something a seasonal business can actually plan around.
A debt consolidation loan can help you:
- Roll equipment finance, cards and an ATO plan into one facility
- Clear a merchant advance taking a cut of every night's till
- Replace several repayment dates with one you can plan around
- Stop short-term facilities compounding against each other
- Free up the cash flow to trade through a quiet season
- Exit by sale, or once one clean facility can be refinanced
Debt consolidation for retailers
A debt consolidation loan combines the facilities a retailer accumulates into one loan secured against a director's home or investment property. The stock finance, the cards, the merchant advance and the ATO plan become one facility.
It is repaid out of trade, or by a refinance once the position is clean. A stack of short-term facilities all drawing on the same daily takings is what quietly turns a viable shop into a cash flow problem.
A debt consolidation loan can help you:
- Roll stock finance, cards and an ATO plan into one facility
- Clear a merchant cash advance taking a cut of daily takings
- Stop several facilities drawing on the same daily takings
- Replace a repayment every week with one you can plan around
- Restore margin that short-term facilities were consuming
- Exit by trade, or by a refinance once the position is clean
Debt consolidation for builders and contractors
A debt consolidation loan rolls the facilities a builder accumulates across jobs into one loan, secured against the yard, the office or a director's property.
It is repaid by a progress payment, the sale of the security, or a refinance. Debt in this sector is taken on job by job, which is how a builder ends up servicing four facilities out of one payment cycle.
A debt consolidation loan can help you:
- Roll plant finance, cards and an ATO plan into one facility
- Clear facilities taken on job by job across several contracts
- Replace several repayment dates with one payment cycle
- Stop short-term facilities compounding while a claim sits unpaid
- Restore the cash flow needed to bid on the next contract
- Exit by a progress payment, a sale, or a refinance
Debt consolidation for transport and warehousing operators
A debt consolidation loan rolls the facilities behind a fleet into one loan, secured against the depot, the warehouse or a director's property.
It is repaid from contract receipts, or by a refinance. Fleets are financed vehicle by vehicle, and an operator can end up carrying a dozen agreements at a dozen rates without ever having chosen to.
A debt consolidation loan can help you:
- Roll a dozen vehicle agreements into one facility
- Clear chattel mortgages taken on vehicle by vehicle
- Replace a dozen repayment dates with one
- Stop high-rate facilities eating the margin on a contract
- Free up the capacity to take on the next contract
- Exit by contract receipts, or a refinance
Debt consolidation for manufacturers
A debt consolidation loan rolls plant finance, trade facilities and tax arrears into one loan secured against the factory property.
It is repaid when customers pay, or by a refinance once the position is clean. Equipment is financed machine by machine, and the repayments tend to accumulate faster than the order book does.
A debt consolidation loan can help you:
- Roll plant and equipment finance into one facility
- Clear trade facilities and an ATO plan at the same time
- Replace a repayment for every machine with one for the plant
- Stop repayments outrunning the order book
- Restore the working capital to take on a large order
- Exit by customer payments, or a refinance
Debt consolidation for wholesalers and importers
A debt consolidation loan rolls trade facilities, stock finance and tax arrears into one loan, secured against the warehouse or a director's property.
It is repaid as stock sells through, or by a refinance. Importers commonly finance the same stock two or three times over, and the cost of carrying it can quietly exceed the margin on selling it.
A debt consolidation loan can help you:
- Roll trade finance, stock finance and cards into one facility
- Clear facilities that finance the same stock twice over
- Replace a facility per shipment with one facility
- Stop the cost of carrying stock exceeding the margin on it
- Free up the capacity to commit to the next shipment
- Exit by sell-through, or a refinance
Debt consolidation for technology companies
A debt consolidation loan rolls venture debt, equipment and card facilities, a tax arrears balance and any short-term money raised along the way into one loan with one payment date.
It is repaid by a refinance once the position is clean, or from revenue as it recovers. Six lenders and four payment dates is often the reason the next lender declines, and consolidating them is what makes a longer-term facility possible.
A debt consolidation loan can help you:
- Roll venture debt, card facilities and equipment finance into one loan
- Clear a tax arrears balance at the same time as the commercial debt
- Replace six payment dates with one
- Repay the short-term facilities taken on to get through the last two quarters
- Present a balance sheet an investor or a bank will lend against
- Stop meeting several repayment dates out of one month of revenue
Debt consolidation for practices and professional firms
A debt consolidation loan rolls practice debt, equipment finance and tax arrears into one loan, secured against a director's home or investment property.
It is repaid by a refinance to a long-term practice facility, or from the practice's own cash flow. Partnership debt is often personal, and consolidating it is usually what makes the practice financeable again.
A debt consolidation loan can help you:
- Roll practice debt, equipment finance and cards into one facility
- Clear PAYG and superannuation arrears across a partnership
- Replace partner-by-partner debt with one practice facility
- Restore a position a long-term lender will refinance
- Fund a partner's exit at the same time as clearing the debt
- Exit once the position is clean enough for a practice lender
Debt consolidation for property developers
A debt consolidation loan rolls the facilities carried across projects into one loan, secured against a site, completed stock, or another property in the portfolio.
It is repaid when the stock settles, or when the project is refinanced. Developers accumulate mezzanine, private and trade debt across projects, and it is rarely all repaid by the project that created it.
A debt consolidation loan can help you:
- Roll mezzanine, private and trade debt into one facility
- Clear debt carried over from a project that is already finished
- Replace a facility per project with one across the portfolio
- Clean up a position a senior lender will not fund behind
- Free up the capacity to acquire the next site
- Exit when stock settles, or on a project refinance
Debt consolidation for property investors
A debt consolidation loan rolls the facilities across a portfolio into one loan, secured against one property or several.
It is repaid when a property sells, or when the portfolio is refinanced. A portfolio built over time is financed over time, and the result is a spread of rates, terms and expiry dates that nobody actually designed.
A debt consolidation loan can help you:
- Roll facilities across several titles into one loan
- Clear high-rate private debt taken on to complete a purchase
- Replace a spread of expiry dates with one facility
- Clean up a position that is blocking a portfolio refinance
- Free up equity for the next acquisition
- Exit by sale, or by a portfolio refinance
"When a business is running three or four facilities at different rates across different lenders, the blended cost of that debt can quietly add up. Consolidating into a single first or second mortgage position inside 70% LVR usually brings the overall cost of debt down and takes a lot of the administrative and refinancing pressure off the table. We are glad to map out what that looks like for your situation."
Gino Tabila
Associate Director
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
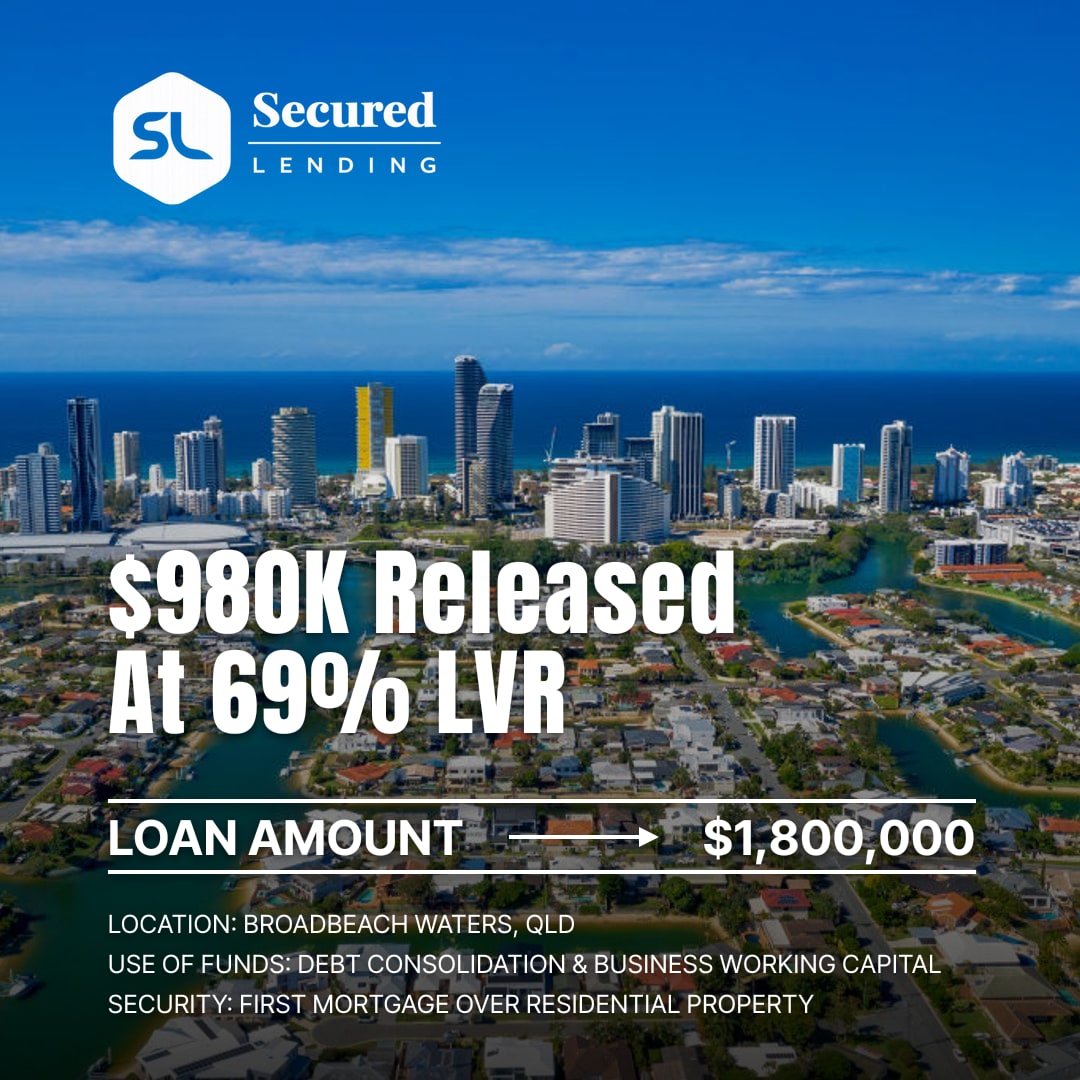
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
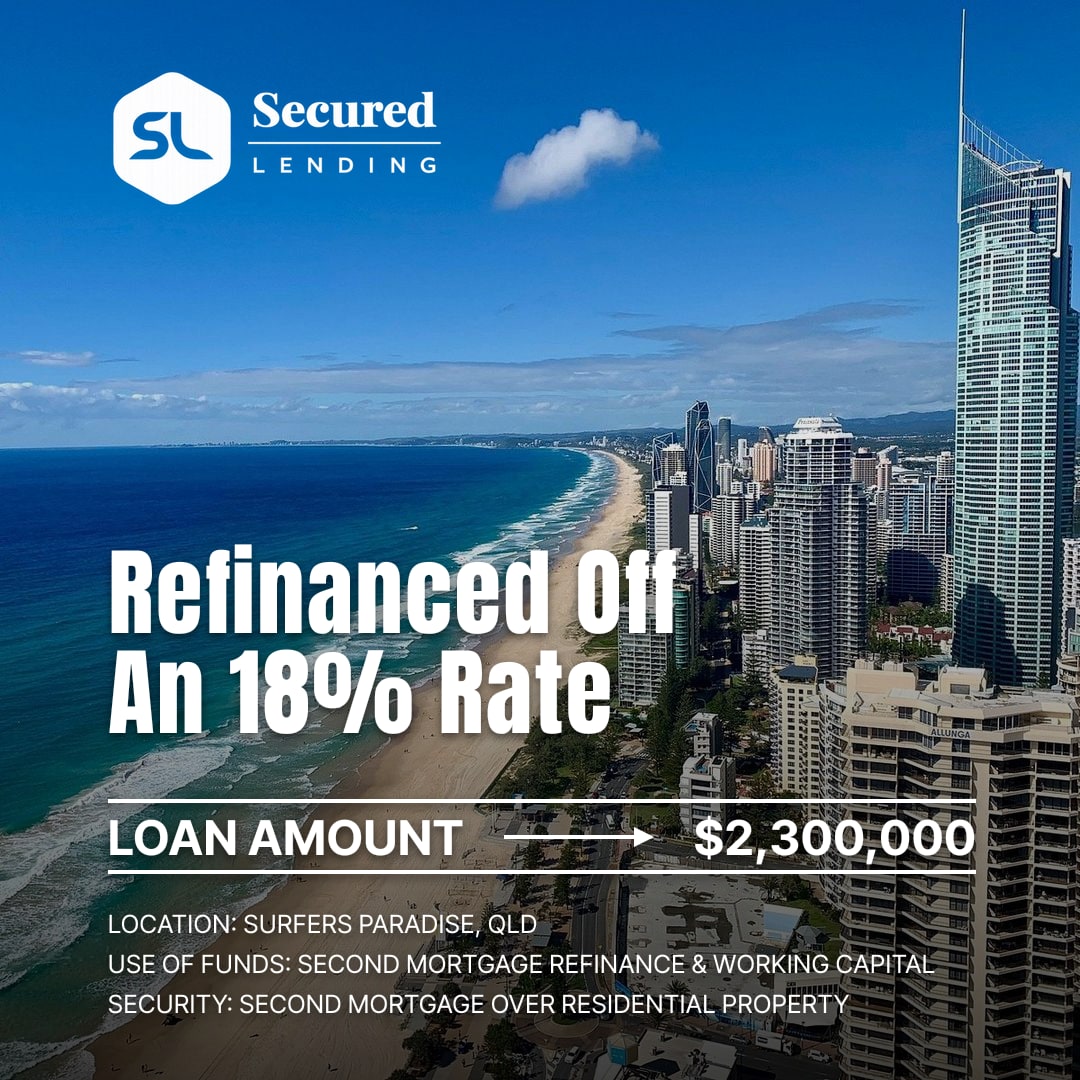
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
Recently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Scenarios We Can Help With
Browse our full range of services, industries, locations, and resources to find the right financial solution for your needs.