Urgent ATO Tax Debt Finance, Funded Fast
Pay off your ATO debt and let your business thrive
Experts in strategic, short-term finance
The ATO says that where a business does not pay its tax debt, or does not engage with the ATO to pay it, it may take firmer action. That can include a garnishee notice to your bank, your customers or your merchant card provider, a director penalty notice, or reporting the debt to credit reporting bureaus. In the 2024-25 financial year the ATO issued more than 84,000 director penalty notices and more than 15,000 garnishee notices.
A tax debt loan gives your business the funds to pay the ATO in full, which stops the general interest charge building on the balance. If your business owes the ATO, we would be glad to help.
Why Consider a Tax Debt Loan?
- •Avoid ATO Penalties and Legal Action: Stay ahead of escalating fees and enforcement by clearing your tax debt on time
- •Free Up Working Capital: Preserve your cash flow and keep business operations running smoothly
- •Consolidate Outstanding Debts: Roll multiple obligations into one manageable repayment plan
- •Avoid Business Disruption: Protect your reputation, credit profile, and continuity of service
Unpaid ATO Debt Now Costs More
Are you treating unpaid tax like a cash flow buffer? The ATO's general interest charge (GIC) is 11.51% a year for October to December 2026, calculated daily on a compounding basis, and the ATO reviews the rate every quarter. Since 1 July 2025, GIC can no longer be claimed as a tax deduction, so the whole charge is a cost to the business. Whether interest on a business loan used to pay the ATO can be claimed depends on your circumstances. Ask your accountant to compare the two before you decide.
Unpaid super now works the same way. Since Payday Super began on 1 July 2026, super that is not received by the fund within 7 business days of payday becomes a Superannuation Guarantee Charge owed directly to the ATO, with interest that compounds daily from payday, just like the GIC above.
Is a Tax Debt Loan Right for You?
Ask yourself:
- •Is ATO pressure limiting your business growth?
- •Do you need short-term cash to stay compliant and operational?
- •Would fast finance help you negotiate better terms with the ATO?
- •Are traditional lenders unwilling to assist due to the nature of your tax debt?
If you answered yes to any of the above, a short-term tax debt loan could be the right solution.
Tax Debt Finance for Business Owners With Bad Credit
Owing the ATO and carrying defaults tend to arrive together, and each one makes the other harder to fix through a bank. We break the loop by lending on the property. Where there is equity inside 70% LVR and a clear path to repayment, we can clear the tax debt in days at rates from 9.7% p.a., without the full financials a bank would want before it even opened the file.
Industries We Service
ATO tax debt finance for builders and contractors
An ATO tax debt loan clears the debt in full, secured against the yard, the office or a director's property. The ATO is paid out, the escalation stops, and the business deals with one lender instead of a payment plan and a penalty regime.
It is repaid by a progress payment, the completion of a job, or a refinance once the position is clean. In construction the debt is rarely just a debt, because an ATO position can cost a licence, a tender, or a head contractor's approval to stay on site.
An ATO tax debt loan can help you:
- Pay out an ATO debt in full and stop the penalties compounding
- Clear PAYG and superannuation before a penalty notice issues
- Protect a licence or accreditation that the debt puts at risk
- Stay eligible for tenders that require a clean tax position
- Stop a garnishee intercepting a head contractor's payment
- Keep a head contractor's approval to remain on site
ATO tax debt finance for pubs, hotels and venues
An ATO tax debt loan pays the ATO out in full, secured against the venue or a director's property. The penalties stop compounding, and the payment plan stops running the business.
It is repaid from trade, from a sale, or by a refinance once the tax position is clean. Hospitality carries this debt more often than most, because a quiet season is usually paid for with the money that was set aside for GST and PAYG.
An ATO tax debt loan can help you:
- Clear the debt before the ATO moves to wind up the company
- Clear a payment plan taking a cut of every quiet week
- Clear GST and PAYG that a quiet season was funded with
- Lift a garnishee taking money before it reaches the venue
- Protect a liquor or gaming licence from a tax position
- Keep trading as normal while the debt is cleared
ATO tax debt finance for retailers
An ATO tax debt loan clears the debt in full, secured against a director's home or investment property. Most retailers lease their space, so that property is the usual security.
It is repaid from the season's takings, or by a refinance once the position is clean. A retail tax debt is usually a timing failure rather than a trading failure, and the escalation does not distinguish between the two.
An ATO tax debt loan can help you:
- Clear a debt before it is reported to a credit bureau
- Restore a payment plan the ATO has already defaulted
- Clear GST and PAYG accrued through a quiet quarter
- Lift a garnishee taking money out of the merchant account
- Restore supplier terms that a tax default has put at risk
- Keep the doors open through the season that repays it
ATO tax debt finance for transport and warehousing operators
An ATO tax debt loan pays the ATO out in full, secured against the depot, the warehouse or a director's property.
It is repaid from contract receipts, or by a refinance once the position is clean. In transport the debt threatens more than the balance sheet, because contracts and accreditations are routinely conditional on a clean tax record.
An ATO tax debt loan can help you:
- Settle the debt before a statutory demand is issued
- Clear a debt that is blocking a contract renewal
- Protect an accreditation or contract that requires a clean record
- Clear GST and PAYG that a slow-paying contract left behind
- Lift a garnishee taking payments before they reach the business
- Keep the fleet on the road while the debt is cleared
ATO tax debt finance for technology companies
An ATO tax debt loan clears PAYG, GST and superannuation in a single payment. In a technology company the balance usually builds through a year of deliberate reinvestment rather than a year of trading badly, and it builds quickly against a large engineering payroll.
It is repaid from revenue, a raise, or a refinance once the position is clean. Clearing it in one payment stops the general interest charge compounding and clears a debt the ATO can report to credit bureaus, which is what blocks the company's next facility.
An ATO tax debt loan can help you:
- Clear PAYG, GST and superannuation built up on an engineering payroll
- Stop the general interest charge compounding on the balance
- Remove a reported tax debt before it blocks the next facility
- Act after a payment plan has already been defaulted on
- Clear the debt before it surfaces in acquisition due diligence
- Present a clean tax position to an incoming investor
ATO tax debt finance for manufacturers
An ATO tax debt loan clears the debt in full, secured against the factory or a director's property.
It is repaid when the customer pays, or by a refinance once the position is clean. A tax default in manufacturing tends to arrive alongside supplier terms being withdrawn, which is how a cash problem quietly becomes a production problem.
An ATO tax debt loan can help you:
- Stop the general interest charge compounding daily
- Clear a debt holding up an equipment finance approval
- Restore supplier terms that a tax default has withdrawn
- Protect a tender or supply contract that requires a clean record
- Stop a garnishee intercepting a customer's payment
- Keep the plant running while the debt is cleared
ATO tax debt finance for wholesalers and importers
An ATO tax debt loan pays the ATO out in full, secured against the warehouse or a director's property.
It is repaid as stock sells through, or by a refinance once the position is clean. GST and duty on imported stock are a common way this debt builds, because both are paid long before the goods are sold.
An ATO tax debt loan can help you:
- Clear the debt before the default is reported
- Clear a debt that has frozen trade credit insurance
- Clear GST and duty accrued on stock that has not yet sold
- Restore supplier and trade credit terms
- Stop a garnishee intercepting a debtor's payment
- Keep importing while the debt is cleared
ATO tax debt finance for practices and professional firms
An ATO tax debt loan clears the debt in full, secured against a director's home or investment property.
It is repaid by a refinance once the position is clean, or from the practice's own cash flow. In a partnership the exposure is personal, which is what makes a director penalty notice in this sector more than a company problem.
An ATO tax debt loan can help you:
- Clear the debt before the partners are pursued personally
- Respond to a director penalty notice inside its deadline
- Clear PAYG and superannuation across a partnership
- Protect a professional registration from a tax default
- Stop a garnishee intercepting fees as they are billed
- Keep the practice operating while the debt is cleared
ATO tax debt finance for property developers
An ATO tax debt loan clears the debt in full, secured against a site, completed stock, or another property in the portfolio.
It is repaid when the stock settles, or when the project is refinanced. A tax default at the wrong moment can stop a senior lender drawing a facility, which is how a tax problem becomes a construction problem.
An ATO tax debt loan can help you:
- Clear the debt before it triggers a senior facility default
- Clear GST that fell due before the lots settled
- Clear a position that is holding up a senior lender's drawdown
- Clear GST on lots that settled ahead of the tax bill
- Stop a garnishee intercepting settlement proceeds
- Keep the project on programme while the debt is cleared
ATO tax debt finance for property investors
An ATO tax debt loan clears the debt in full, secured against an investment property or the wider portfolio.
It is repaid when a property sells, or when the portfolio is refinanced. A tax default will usually stop a refinance in its tracks, so clearing it is often the first step to fixing the wider position.
An ATO tax debt loan can help you:
- Clear land tax and GST that have fallen due together
- Clear a debt that is blocking a lender from refinancing
- Clear a position that is blocking a refinance
- Clear tax that has fallen due on a property sale
- Lift a garnishee taking rent at the source
- Repay when a property settles, or on a portfolio refinance
ATO tax debt finance for childcare operators
An ATO tax debt loan clears withholding tax and superannuation built up on a large educator payroll in a single payment. In childcare the balance usually builds because staffing has to meet the required educator-to-child ratios every day the centre is open, while Child Care Subsidy payments arrive later.
It is repaid from trading income or a refinance. The funds are paid to the company, which pays the Australian Taxation Office in full, and we can still lend after a director penalty notice has arrived, which matters to directors when most of the debt is withholding tax and superannuation.
An ATO tax debt loan can help you:
- Clear withholding tax and superannuation built up on an educator payroll
- Act after a director penalty notice has arrived for unpaid superannuation
- Clear a balance that grew through a year of high staffing costs
- Clear the debt before the bank reviews the facility on your centre
- Keep educators paid on time while the full ATO balance is cleared
- Clear the tax debt before buying or opening a second centre
ATO tax debt finance for medical and dental practices
An ATO tax debt loan clears pay as you go withholding, goods and services tax and superannuation for employed staff in one payment. In a practice the balance builds on the payroll for nurses, receptionists and practice managers, while health fund payments and patient accounts arrive on their own timetable.
It is repaid by a refinance or the sale of a property. The loan is paid to your practice company, which pays the Australian Taxation Office in full, and we can still lend after a director penalty notice or a garnishee notice has arrived. The debt can be cleared ahead of a planned bank refinance.
An ATO tax debt loan can help you:
- Clear pay as you go withholding on a practice payroll in one payment
- Respond to a garnishee notice issued against the practice
- Clear the superannuation guarantee charge with income tax and activity statement debts
- Stop the general interest charge building on the practice's balance
- Clear the tax debt ahead of a bank refinance of the practice
- Clear the debt before buying a retiring principal's practice
"ATO debt attracts penalty interest that compounds quickly, so timing really matters. We have helped clients with seven-figure tax positions use property security to clear the debt and steady the business within the same week. In most cases the cost of the private facility works out to be less than the penalties and recovery action the ATO would otherwise apply, and we are happy to run through those numbers with you."
Gino Tabila
Associate Director
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
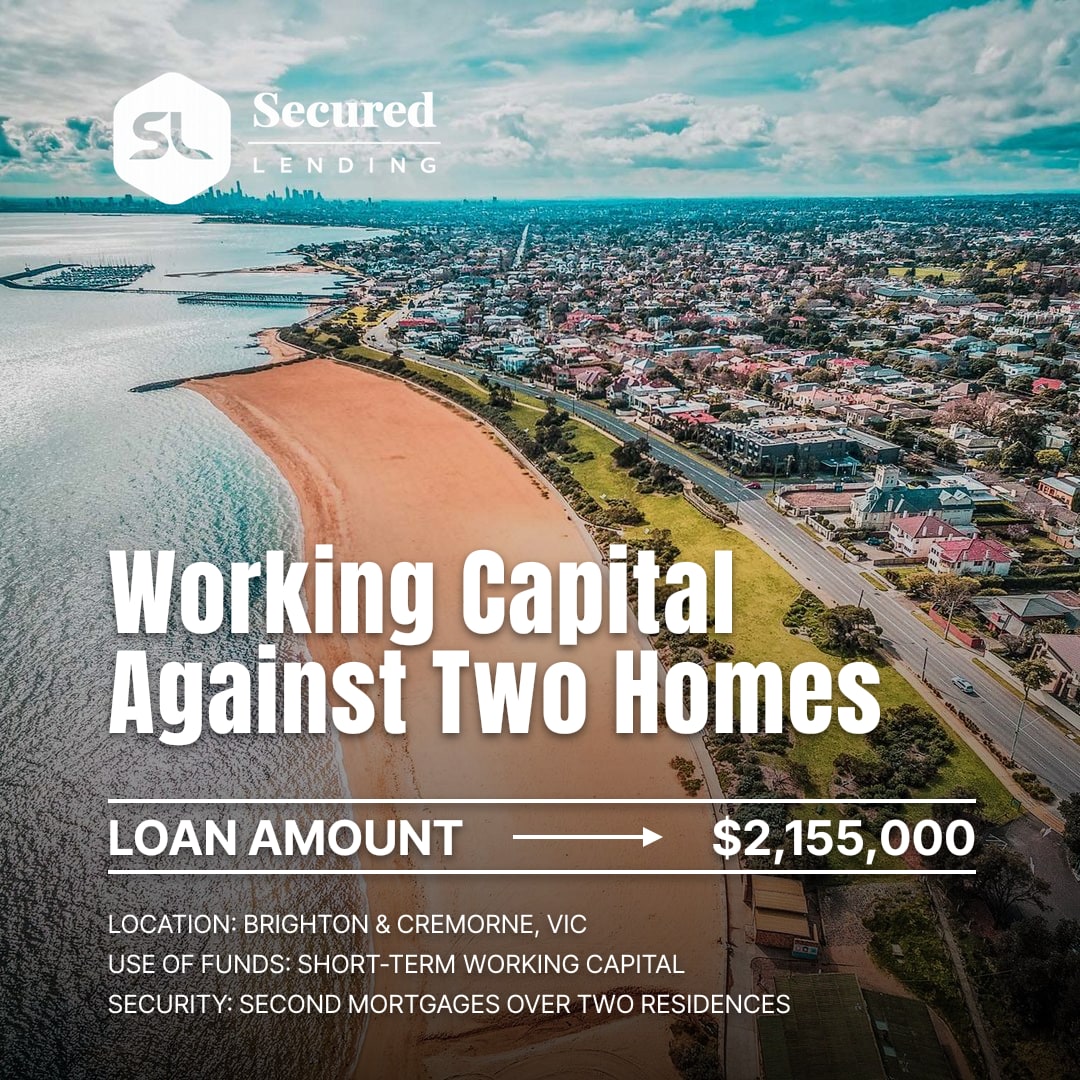
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
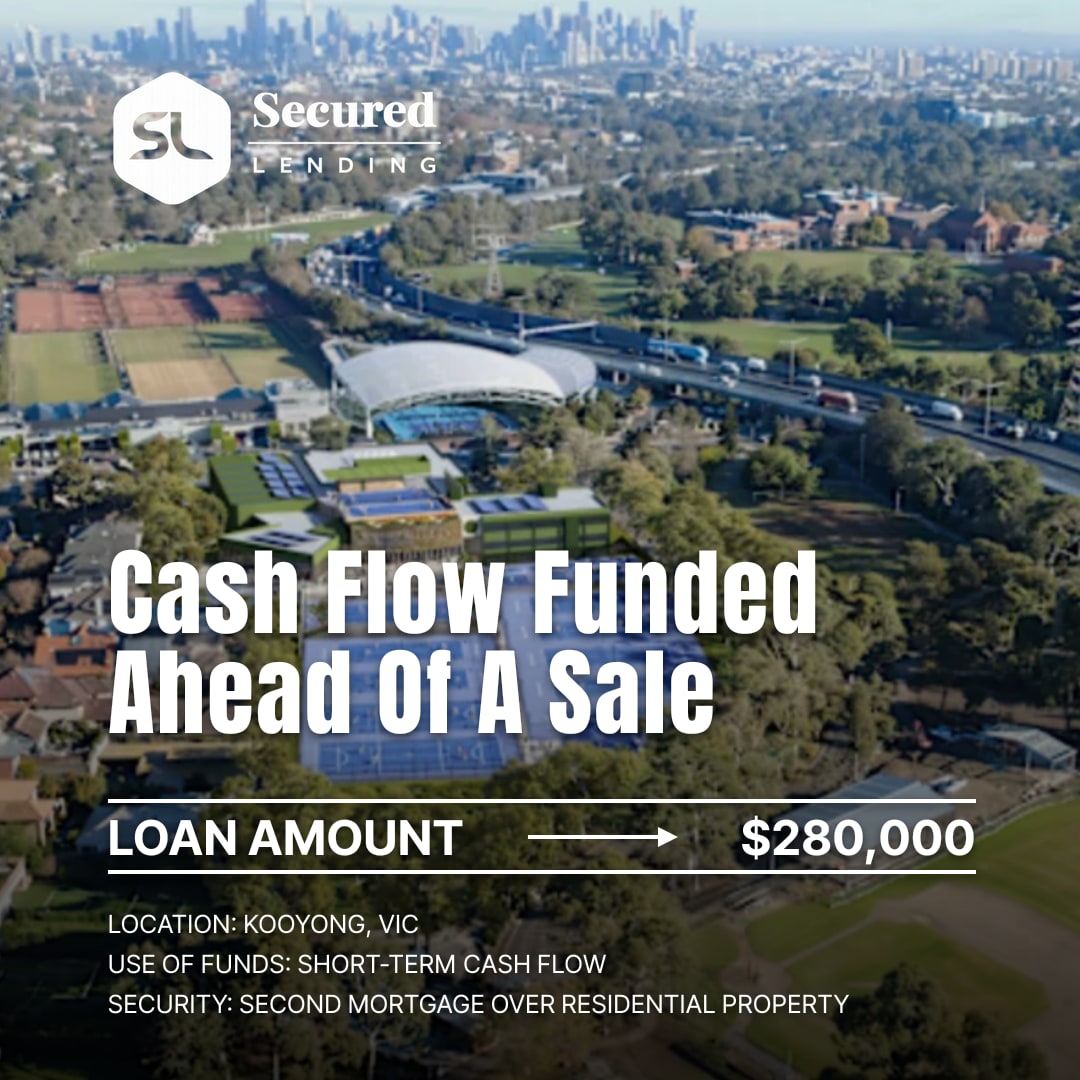
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
Recently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
ATO Debt Scenarios We Fund
Grouped by the notice or deadline in front of you. Each one is written up in full.