First Mortgage Loans for Business, Funded Fast
Secure funding backed by property, tailored for business needs
Experts in strategic, short-term finance
What Is a First Mortgage Private Loan?
A first mortgage private loan is short-term finance secured by a first registered charge over your residential, commercial, or industrial property. As a private lender, Secured Lending holds that first mortgage position, which means we are repaid first. That is what lets us move faster, lend more flexibly, and approve deals that banks simply won't touch.
Unlike a standard bank mortgage, first mortgage private loans aren't designed to be held for 25 years. They're purpose-built for property owners and business owners who need capital now: to bridge a gap, fund a project, clear urgent debt, or unlock equity sitting idle in their property.
Who Uses First Mortgage Private Finance?
Borrowers come to private lenders for a first mortgage when:
- •A bank has declined their application due to credit history, irregular income, or loan complexity
- •You're self-employed or operate a trust structure that doesn't fit standard serviceability models
- •You need to settle within days on a property purchase or refinance
- •You're bridging between the sale of one property and the purchase of another
- •You need to release equity quickly to fund a business opportunity or urgent obligation
- •Your existing mortgage is in arrears and you need to refinance out of default
- •You're funding a construction or development project that doesn't fit bank criteria
- •You need to pay a tax debt, ATO liability, or creditor before a formal arrangement is required
Why Choose Secured Lending as Your Private Lender?
- •Direct lender: you deal with the decision-makers, not a broker middleman
- •Transparent fees: loan fees and rates disclosed upfront, no hidden charges
- •Experienced team: specialists in complex, time-sensitive private lending scenarios
- •Nationwide coverage: lending across all states and territories
- •In-house valuation team: we assess your security simultaneously with your application
Bad Credit and a First Mortgage: What Actually Matters
Banks decline first mortgages on credit history and serviceability long before they look at what the property is worth. We work the other way around. A first registered mortgage over residential, commercial or industrial property puts us first in line, and that position is what lets us fund borrowers carrying defaults or arrears. Rates start from 9.7% p.a., and full financials are not required on an asset-backed file.
Industries We Service
First mortgage finance for property developers
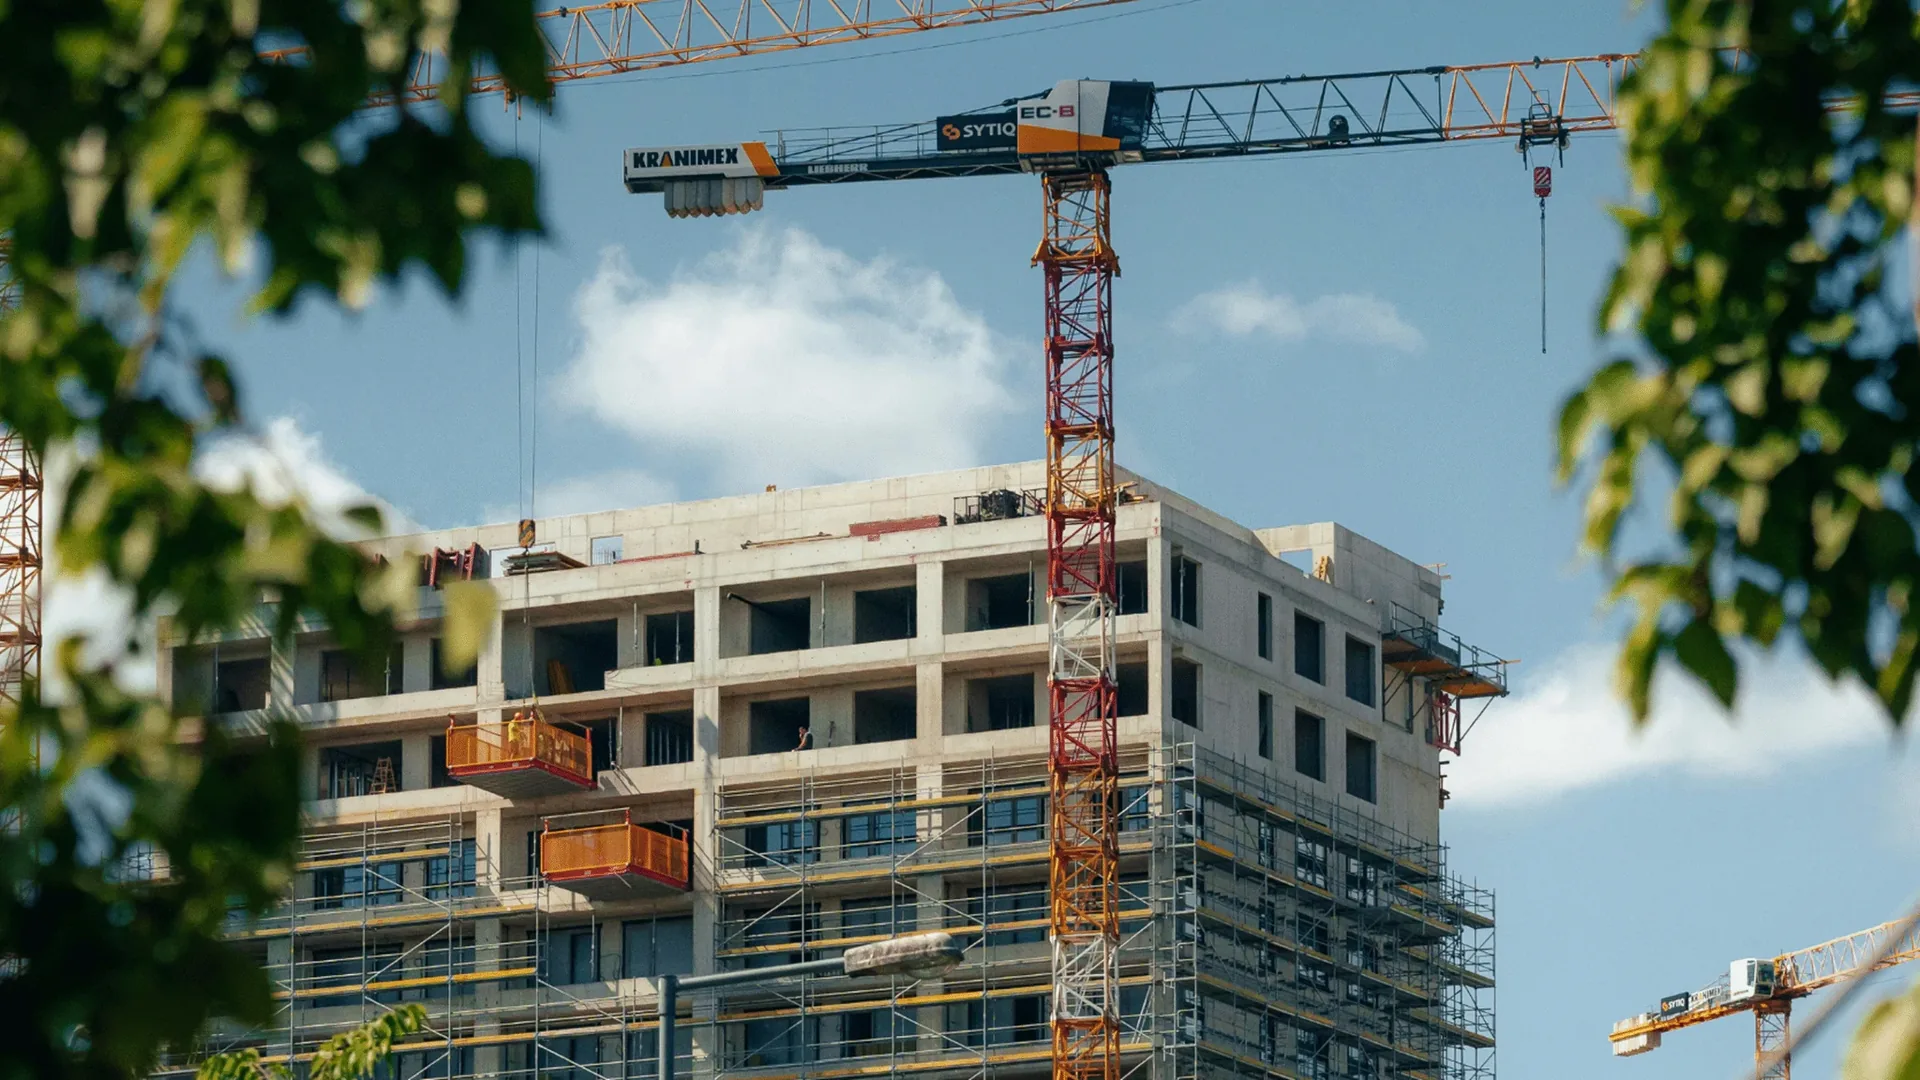
A first mortgage funds a site acquisition or a settlement with us in first position on title. Where there is an existing first, we pay it out and take its place, so the site carries one lender, one charge and one set of conditions rather than a stack of them.
It is repaid when the stock settles, a construction facility takes over, or the site is sold. Holding first position is what allows a facility sized to the whole site rather than a top-up behind somebody else, and we lend our own funds with our own valuers, so the approval and the valuation do not run on separate clocks.
A first mortgage can help you:
- Acquire a site with us as the only lender on title
- Pay out an existing first mortgage and consolidate the charge
- Fund a settlement where a construction facility is not yet in place
- Borrow against unencumbered property, the site itself or completed stock
- Structure a whole-of-site facility rather than a top-up
- Exit when the stock settles, or a construction facility takes over
First mortgage finance for property investors
A first mortgage lends against an investment property held outright, or refinances the existing first and takes its place. We hold the only registered charge on the title.
It is repaid when the property sells, when a longer-term facility takes over, or when the portfolio is refinanced as a whole. It is the product for an investor with equity sitting in unencumbered titles that is doing nothing.
A first mortgage can help you:
- Borrow against an investment property you own outright
- Pay out an existing first mortgage and take its place
- Fund a purchase with us as the only lender on title
- Release equity across a portfolio held in several titles
- Move on a purchase without waiting on a chain of approvals
- Exit by sale, or by a refinance of the portfolio
First mortgage finance for builders and contractors
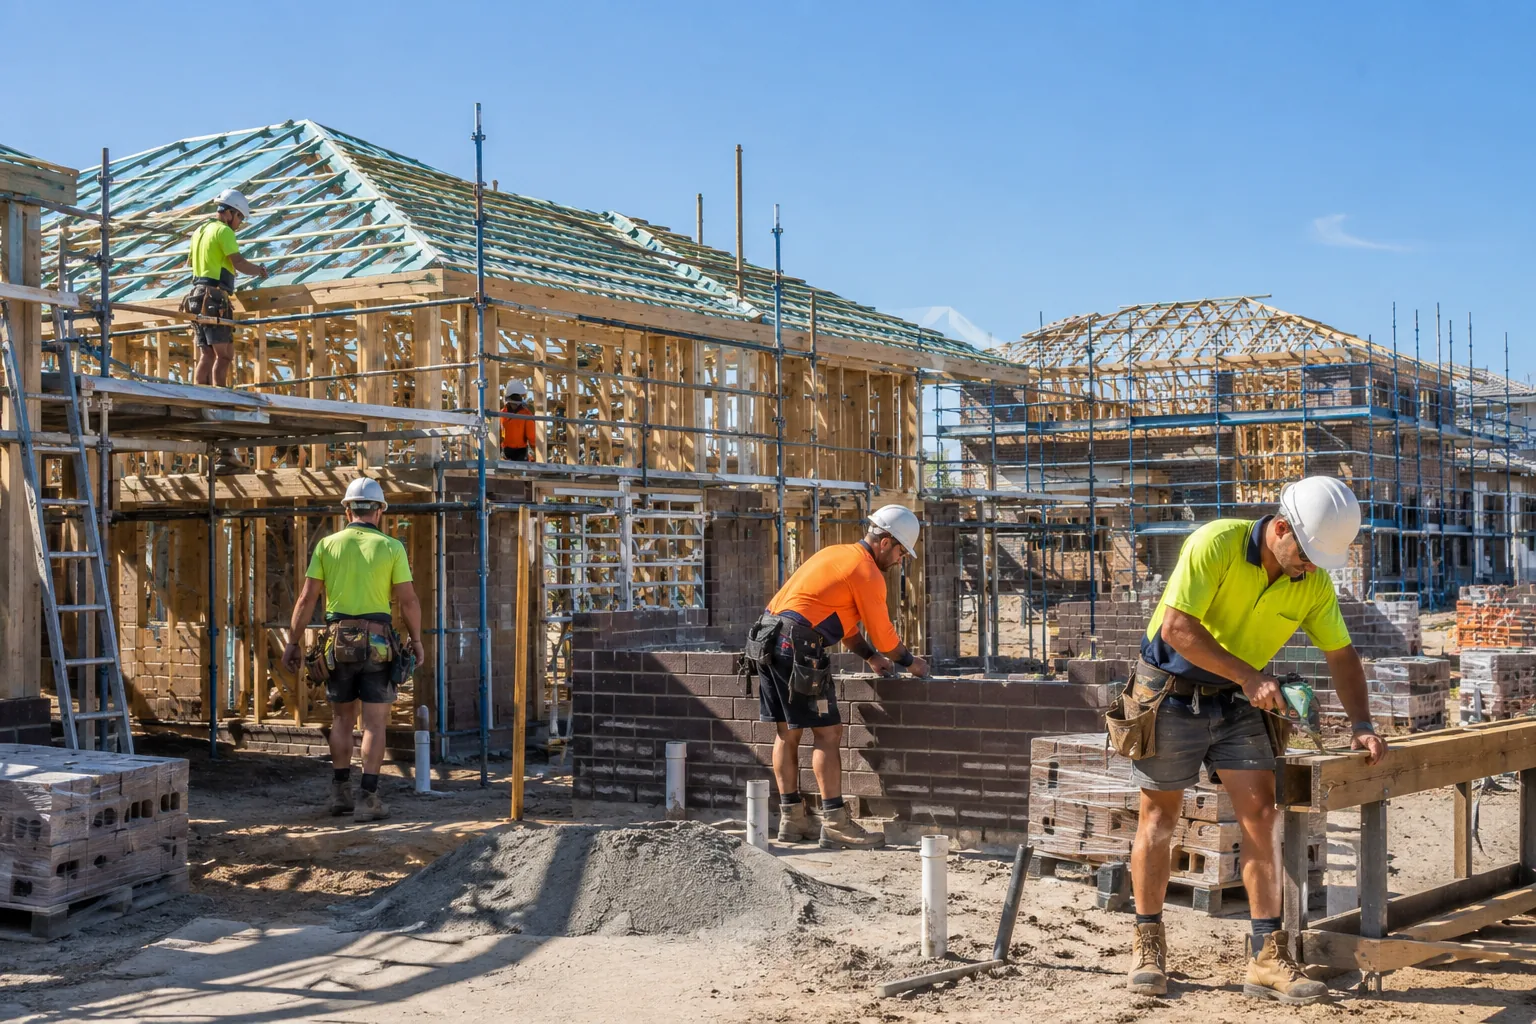
A first mortgage lends against the commercial or industrial property the business owns, the yard, the office or the depot, with us in first position. Where the property carries an existing first, we pay it out and take its place.
It is repaid by a progress payment, the completion of the job, or a refinance once the contract is banked. Because we hold the only charge, it supports a facility larger than sitting behind another lender ever could.
A first mortgage can help you:
- Borrow against commercial or industrial property owned outright
- Pay out an existing first mortgage and deal with one lender
- Fund plant, materials, or mobilisation on a major contract
- Cover wages and subcontractors across a long payment cycle
- Take a larger facility than a second position would support
- Exit by a progress payment, completion, or a refinance
First mortgage finance for pubs, hotels and venues
A first mortgage lends against the freehold venue property, with us in first position on title. Where the venue already carries a first mortgage, we pay it out and take its place, so there is one lender rather than two.
It is repaid when the venue sells, when a longer-term facility takes over, or from trade once the figures support a refinance. It is the product for a freeholder who wants the most capital the venue can carry, not a top-up behind an existing lender.
A first mortgage can help you:
- Borrow against freehold venue property owned outright
- Pay out the existing first mortgage on the venue
- Fund a second site, a refurbishment, or a licence purchase
- Release the most capital the venue can carry
- Keep trading as normal for the life of the facility
- Exit by sale, by refinance, or by trade
First mortgage finance for manufacturers
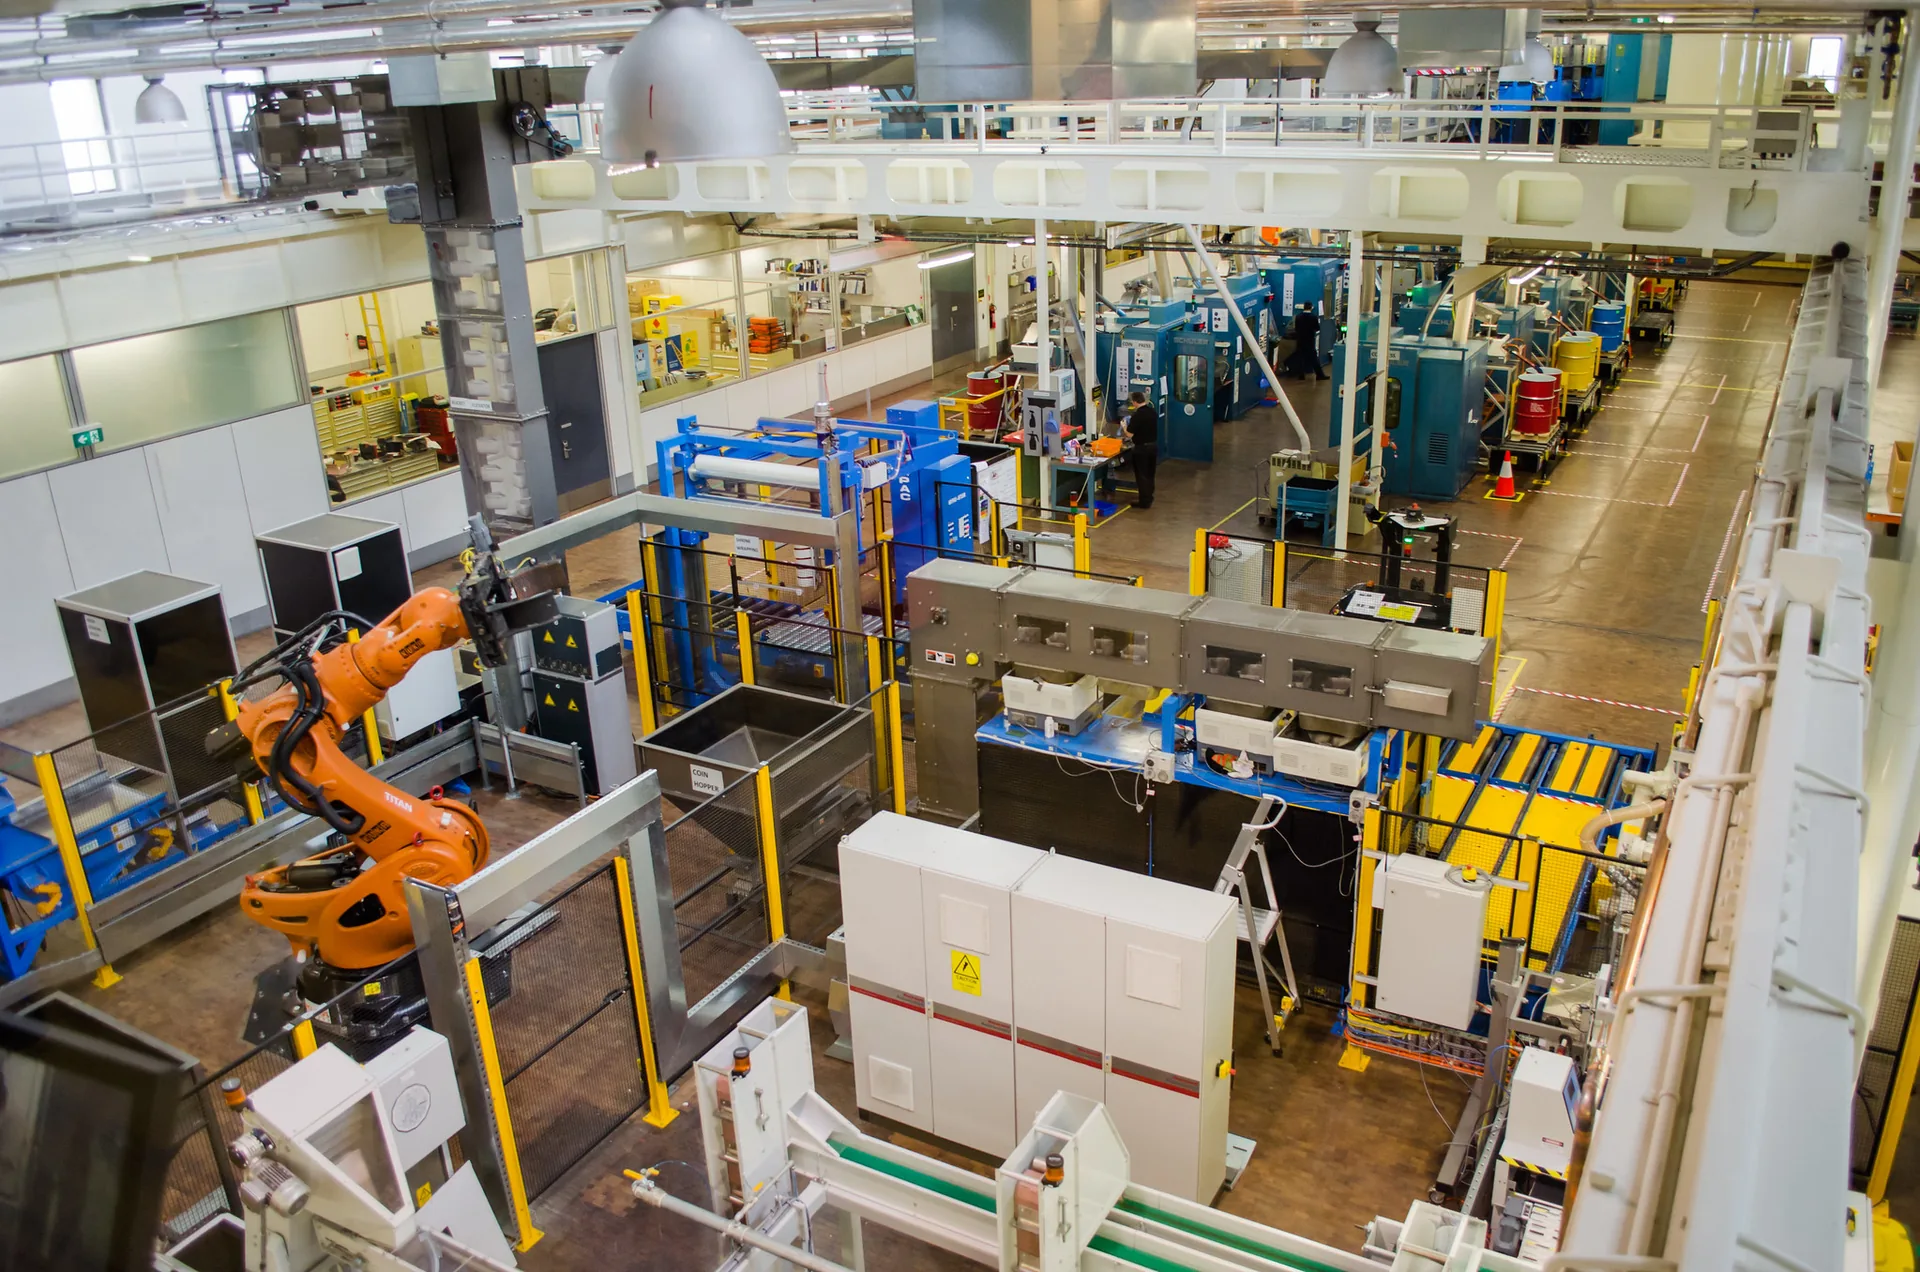
A first mortgage lends against the industrial property with us in first position. Where the site carries an existing first, we pay it out and take its place, leaving one lender and one charge over that property. We never take security over the plant itself.
It is repaid when the customer pays, or by a longer-term facility once the order is delivered and invoiced. First position is what allows a facility large enough to fund a genuinely significant order or a plant purchase, rather than a top-up.
A first mortgage can help you:
- Borrow against industrial property owned outright
- Pay out an existing first mortgage over the site
- Fund plant, machinery or tooling on a major order
- Buy the site next door and hold both under one charge
- Take a facility large enough for a significant order
- Keep the plant running for the life of the facility
First mortgage finance for transport and warehousing operators
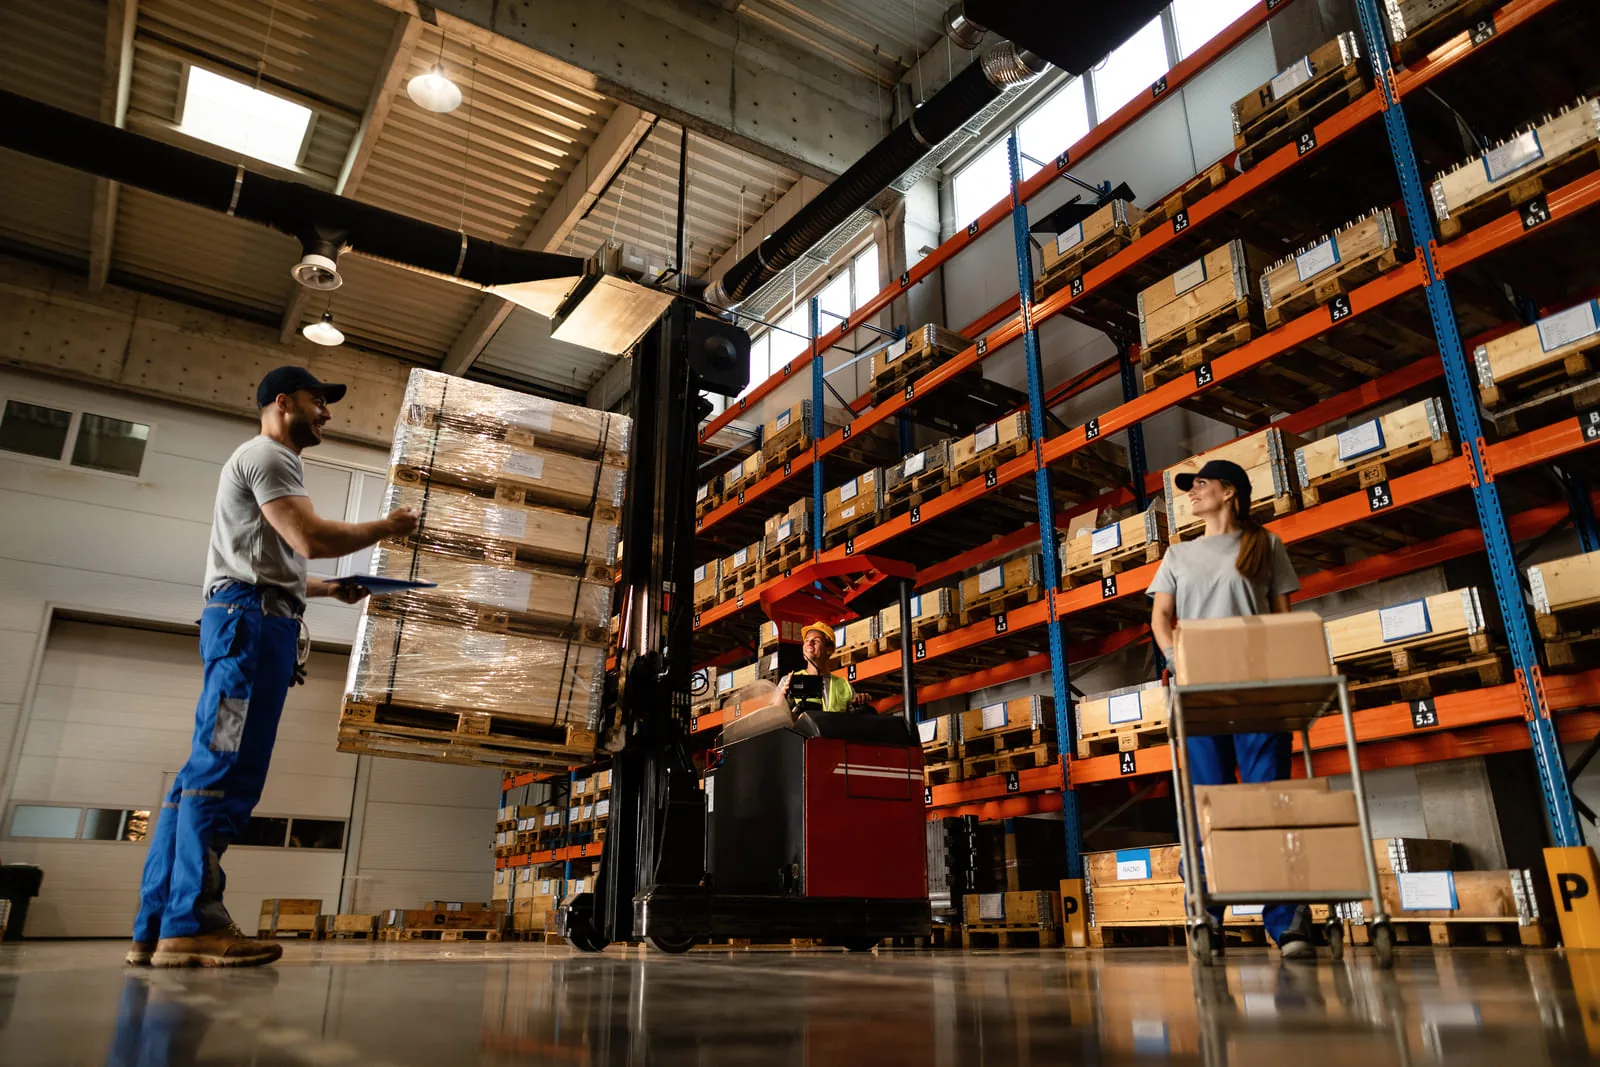
A first mortgage lends against the industrial property the business owns, the depot or the warehouse, with us as the only lender on title. Where there is an existing first, we pay it out and take its place.
It is repaid from contract receipts, an asset finance facility once the fleet is earning, or a refinance. First position supports the size of facility needed to stand up a whole contract, rather than the top-up a second mortgage gives you.
A first mortgage can help you:
- Borrow against depot or warehouse property owned outright
- Refinance the depot's existing first mortgage into the facility
- Fund a fleet, trailers or racking for a new contract
- Buy the depot when a lease ends and the site goes to market
- Take a facility large enough to stand up a whole contract
- Exit by contract receipts, asset finance, or a refinance
First mortgage finance for wholesalers and importers
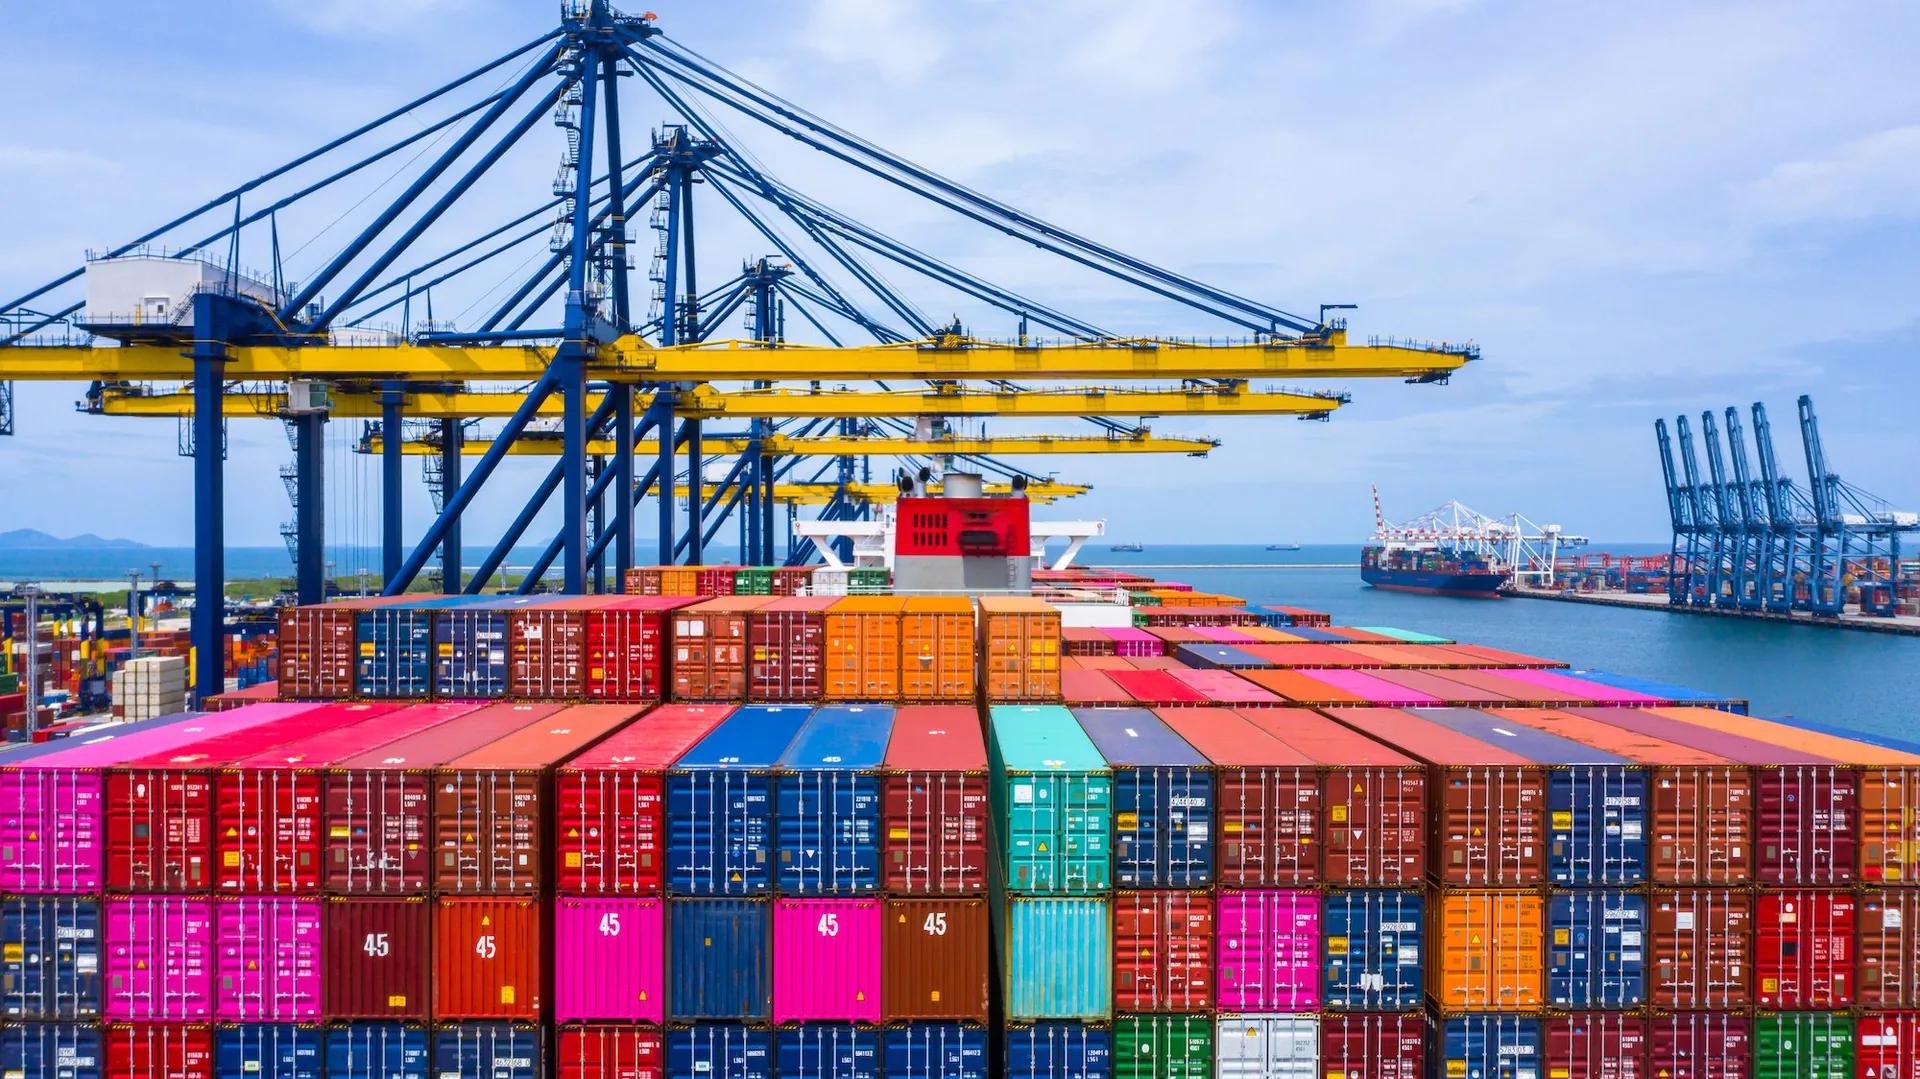
A first mortgage lends against the warehouse property the business owns, with us holding the only charge. Where the warehouse already carries a first mortgage, we pay it out and take its place.
It is repaid as the stock sells through, when a debtor facility takes over, or by a refinance. First position is what supports a facility big enough to fund a container programme rather than a single shipment.
A first mortgage can help you:
- Borrow against warehouse property owned outright
- Pay out an existing first mortgage over the premises
- Fund a container programme rather than a single shipment
- Buy the warehouse next door and hold both under one charge
- Cover customs, freight and storage on goods in transit
- Exit by sell-through, a debtor facility, or a refinance
First mortgage finance for retailers
A first mortgage lends against a director's home or investment property with us in first position, or against the shop where the business owns it. Most retailers lease their space, so the director's own property is the usual security.
It is repaid out of the season the stock was bought for, or by a refinance once the trading period is banked. Where the property is unencumbered, first position gives the largest facility available to us.
A first mortgage can help you:
- Borrow against a director's property held outright
- Refinance a home loan and fund the stock order together
- Fund a season's stock, a fit-out, or a new site
- Buy a full season of inventory in one order, not several
- Take the largest facility the property can carry
- Exit by the season's takings, or a refinance
First mortgage finance for technology companies
A first mortgage puts us in first position, which is what allows a facility large enough to buy a competitor outright rather than fund part of the price. It funds an acquisition, a multi-year product build, or a founder buying back shares from an early investor.
It is repaid by a refinance once the company has the trading history a bank wants to see, by the round, or by a sale. The size of the facility is set by the property equity and the exit, not by a revenue multiple or by a year of low profit.
A first mortgage can help you:
- Fund an acquisition outright rather than in stages
- Pay out an existing first mortgage and release the equity sitting behind it
- Acquire a managed service provider and its contract book in one transaction
- Fund a product build that runs across several financial years
- Buy out a co-founder or an early investor in a single payment
- Borrow an amount set by the property equity and the exit, not by a revenue multiple
First mortgage finance for practices and professional firms
A first mortgage lends against a director's home or investment property with us in first position, or against the rooms where the practice owns them. These firms almost always lease, so the director's property is the usual security.
It is repaid when a long-term practice facility settles, or when the acquisition it funded is refinanced. First position is what allows a facility large enough to fund a buy-in outright rather than partially.
A first mortgage can help you:
- Borrow against rooms the practice owns, or a director's property
- Pay out an existing first mortgage over the security
- Fund a practice buy-in outright rather than partially
- Acquire a practice outright with us as the only lender on title
- Buy the rooms when the landlord offers them
- Exit by a refinance to a long-term practice facility
First mortgage finance for aged care facilities
A first mortgage puts us in first position over the freehold property of an aged care facility or retirement village, valued by our own valuers on a going-concern basis. It buys a facility outright, or pays out a lender that is leaving the sector and takes its place on title.
It is repaid by a refinance to a bank or specialist aged care lender, or by a sale of property. In Queensland the residents' statutory charge over village land ranks ahead of registered mortgages, so on a Queensland village we lend on the value left after that charge, and residents' contracts and deposits stay as they are.
A first mortgage can help you:
- Buy a residential aged care facility with us as the only lender on title
- Pay out a lender that has decided to leave aged care
- Fund a refurbishment to the standards in the same first mortgage
- Buy retirement village land with any residents' charges taken into account
- Borrow on a facility valued on a going-concern basis by our own valuers
- Move to a specialist aged care lender once the acquisition has settled
First mortgage finance for motels, hotels and caravan parks
A first mortgage puts us in first position over the freehold accommodation property, valued on a going-concern basis by our own valuers. It funds the purchase of a motel, a hotel or a caravan park, or repays the existing lender in full so there is one lender on title rather than two.
It is repaid by a refinance once the property has traded under your ownership, or by a sale. The purchase price and a refurbishment budget can be paid together at settlement, and on a land lease community the homes residents own are left out of the valuation.
A first mortgage can help you:
- Buy a freehold motel or boutique hotel with one lender on title
- Repay in full an accommodation loan the bank will not renew
- Buy a caravan or holiday park and its cabins in one transaction
- Pay out a co-owner of a holiday park
- Fund new furniture and bathrooms with the purchase price at settlement
- Refinance once the property has traded under your ownership
"A first mortgage gives everyone a clean, straightforward position to work from, with no subordination to worry about. On quality commercial or residential property inside 70% LVR, that clarity is what lets us move from application to approval within 24 hours, and we are always happy to talk through where a deal sits."
Gino Tabila
Associate Director
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
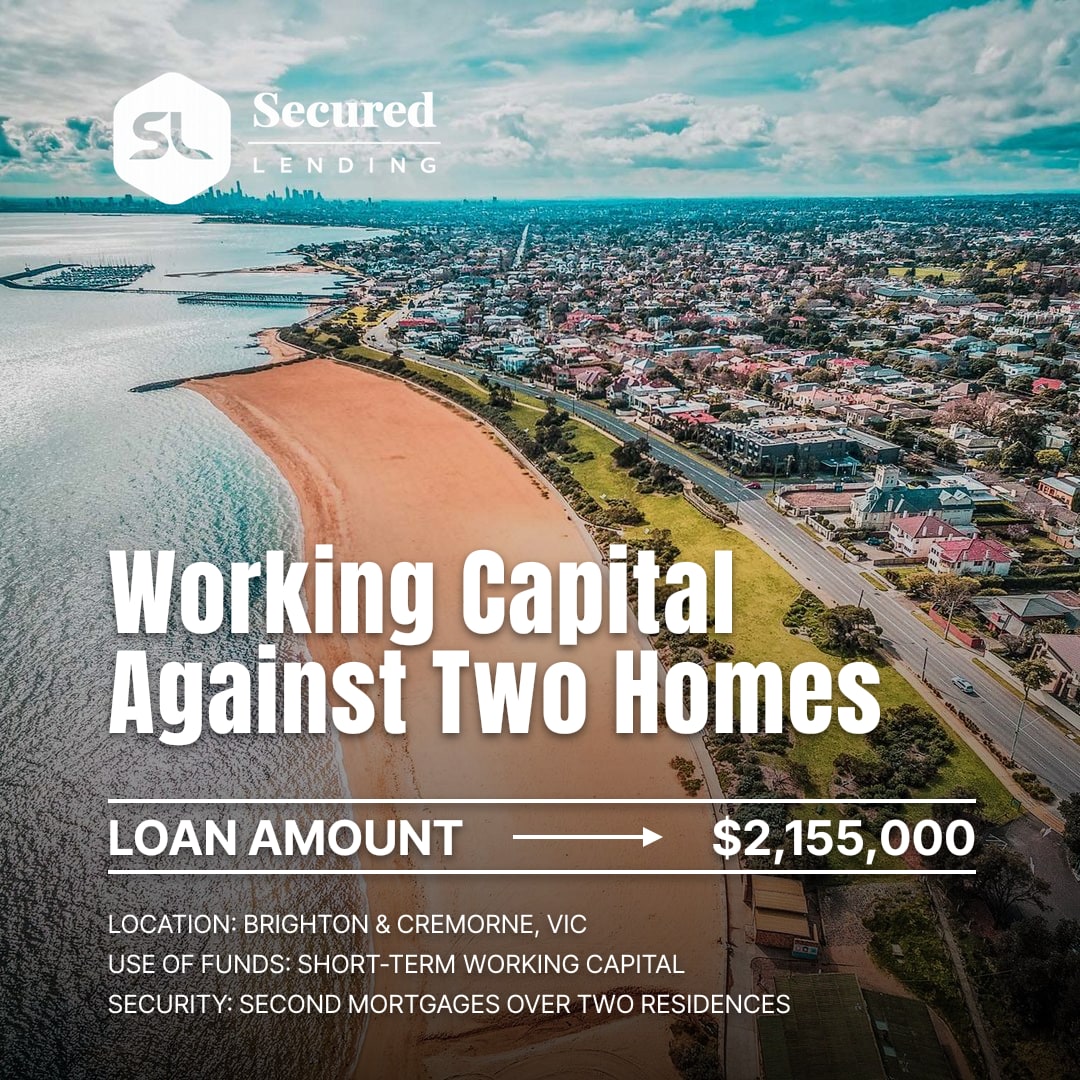
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
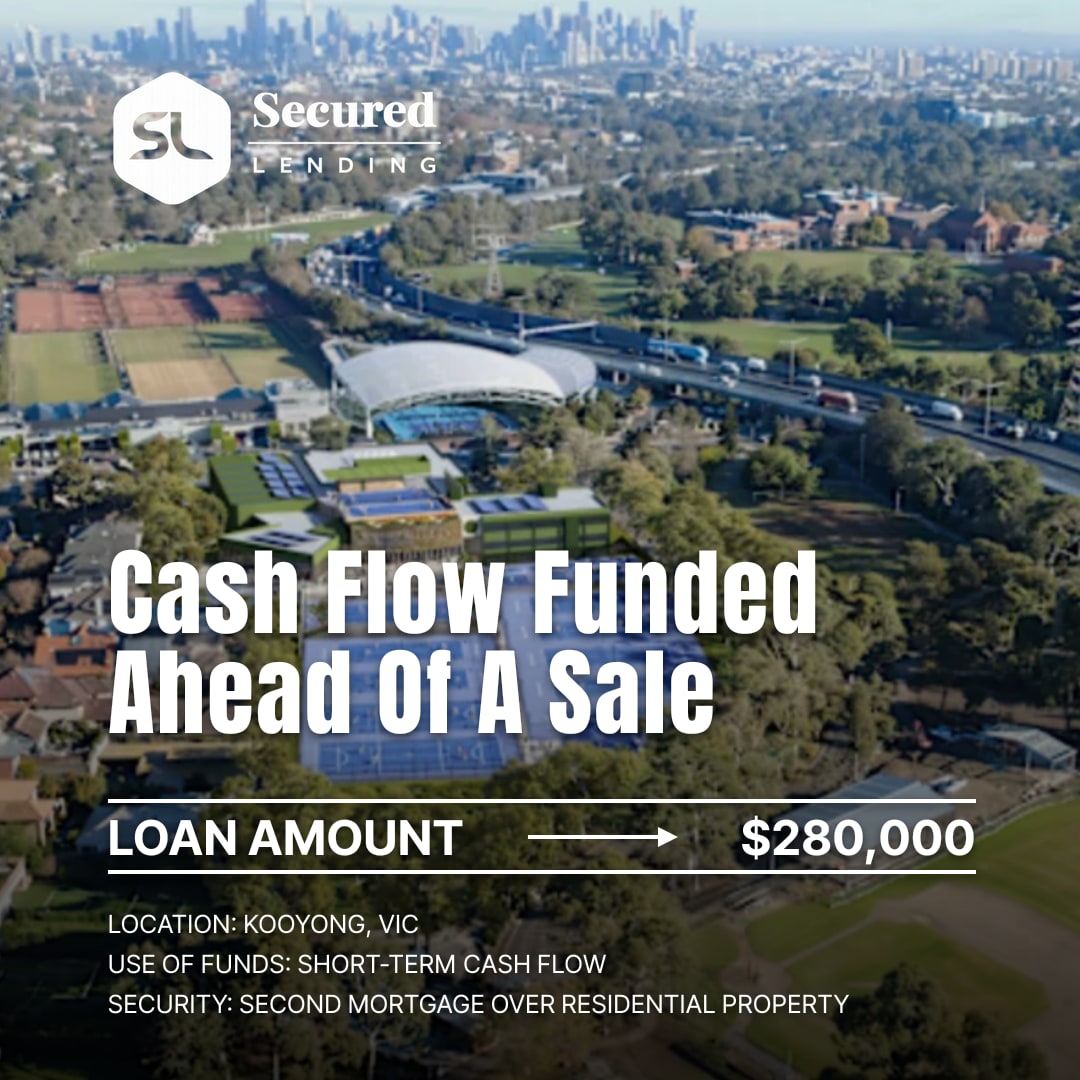
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
Recently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Scenarios We Can Help With
Browse our full range of services, industries, locations, and resources to find the right financial solution for your needs.