Low Cost Second Mortgage Loans, Funded Fast
Short-term second mortgage funding without the bank delay
Experts in strategic, short-term finance
Product Overview
| Term | Interest Rate (p.a.) | Security | Amount up to | LVR |
|---|---|---|---|---|
| 1 month | 11.95% | 2nd mortgage | $2M | 70% combined |
| 2 months | 12.95% | 2nd mortgage | $2M | 70% combined |
| 3 months | 13.95% | 2nd mortgage | $2M | 70% combined |
Key Features
- •Purpose-built for flexibility: designed to get you in and out fast
- •Terms from 1 to 3 months only
- •Second mortgage only, maximum 70% LVR (combined first plus second)
- •Loan amounts up to $2,000,000
- •Fast assessment and settlement
- •The shorter your term, the less you pay in total interest
Who Is This For?
- •Borrowers who need quick funds to finalise a settlement or refinance
- •Business owners bridging a short-term cash flow gap
- •Clients covering urgent expenses such as tax bills or supplier payments
- •Brokers with time-critical scenarios where bank approvals take too long
Important Notes
- •Exit strategy is critical: this is a short-term product and not intended for long-term use
- •Borrowers must have a clear refinance or sale pathway in place
- •Your existing first mortgage holder must consent to a second mortgage being registered
Low Cost Second Mortgages for Borrowers With Bad Credit
The cheapest way out of a credit problem is usually the shortest loan, not the lowest headline rate. A second mortgage over property held for one to three months keeps the total interest small, and the assessment rests on the combined equity inside 70% LVR rather than on your file. Pricing starts at 11.95% p.a., tiering to 12.95% at two months and 13.95% at three.
Industries We Service
Low cost second mortgage loans for retailers
When a retailer needs capital quickly, the facilities on offer are usually a merchant cash advance that takes a slice of every day's takings, or an unsecured line priced for the fact that nothing stands behind it. A second mortgage over a director's property is secured, and it is priced accordingly.
It is repaid out of the season the money was raised for. The security is what makes it cheap, and a lower loan to value ratio with a clear exit is what makes it cheaper still.
A low cost second mortgage can help you:
- Fund stock without a merchant advance taking a daily cut
- Borrow against property instead of against future card sales
- Replace an unsecured line priced for having no security
- Improve the rate by lending at a lower loan to value ratio
- Get a sharper rate where the exit is a banked trading season
- Stop paying an unsecured premium on money you can secure
Low cost second mortgage loans for pubs, hotels and venues
Venues are routinely offered daily-repayment advances taken out of the till, and equipment finance priced on depreciating assets. A second mortgage behind the first on the venue, or on a director's property, is secured against real property instead.
It is repaid when a venue sells, or once the trading figures support a refinance. Security against bricks rather than against a week's takings is the whole reason the pricing is different.
A low cost second mortgage can help you:
- Borrow against the freehold property rather than against the till
- Replace a daily-repayment advance secured on card takings
- Fund equipment without financing it against its own depreciation
- Improve the rate with a lower loan to value ratio on the venue
- Get a sharper rate where the exit is a venue sale
- Stop paying a premium for finance with no property behind it
Low cost second mortgage loans for builders and contractors
Builders are often quoted on invoice finance or an unsecured line while a progress claim sits unpaid, both priced for the risk of a debtor that may not pay. A second mortgage behind the first on the yard, the office or a director's property is priced against the property instead.
It is repaid by the progress payment or the sale of the security. A certified claim with a clear payment path is a clean exit, and a clean exit is what earns the better rate.
A low cost second mortgage can help you:
- Borrow against the industrial property rather than against an unpaid invoice
- Replace invoice finance priced on a debtor's reliability
- Fund a claim gap without an unsecured overdraft premium
- Improve the rate with a lower loan to value ratio on the yard
- Get a sharper rate where a certified claim is the exit
- Price the facility against property, not against a client's conduct
Low cost second mortgage loans for wholesalers and importers
Importers are commonly financed on trade facilities and stock finance, both priced against goods that can spoil, sit, or fail to sell. A second mortgage over the warehouse, or a director's property, is priced against property that does none of those things.
It is repaid as the stock sells through. Property security removes the stock risk from the pricing, which is the difference between the two facilities.
A low cost second mortgage can help you:
- Borrow against the warehouse property rather than against the stock in it
- Replace trade finance priced against goods that may not sell
- Fund a shipment without a stock finance risk premium
- Improve the rate with a lower loan to value ratio on the premises
- Get a sharper rate where the sell-through is well evidenced
- Take the stock risk out of what you pay for the money
Low cost second mortgage loans for manufacturers
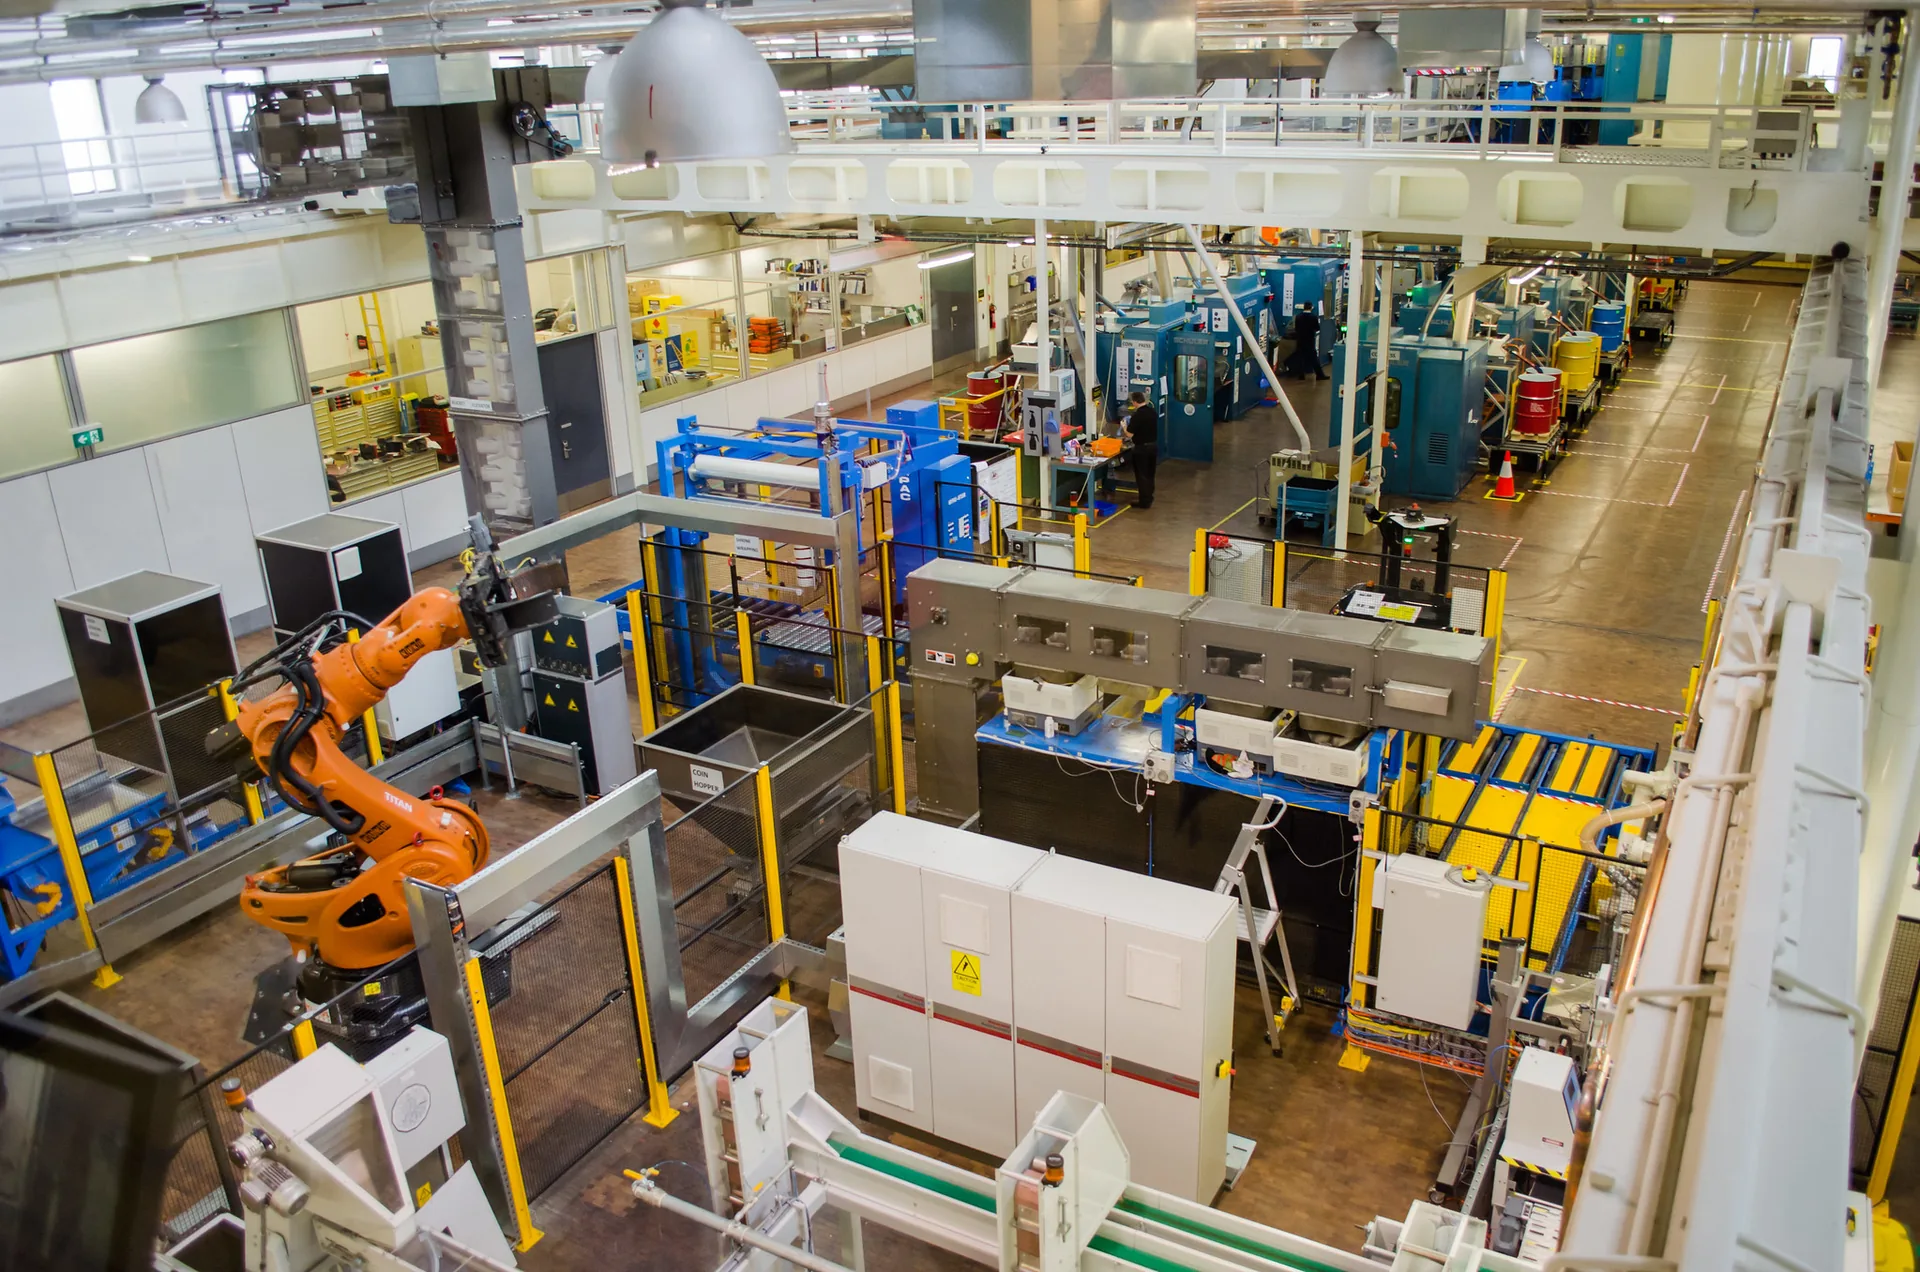
Manufacturers are usually offered equipment finance against machines that depreciate from the day they are installed. A second mortgage behind the first on the factory is priced against land and buildings, which do not.
It is repaid when the customer pays. The pricing follows the security, and a factory is a materially better security than the plant inside it.
A low cost second mortgage can help you:
- Borrow against the factory property rather than against depreciating plant
- Replace equipment finance priced against a machine's residual
- Fund an order without an unsecured working capital premium
- Improve the rate with a lower loan to value ratio on the site
- Get a sharper rate where a signed order underwrites the exit
- Price against land and buildings, not against machinery
Low cost second mortgage loans for transport and warehousing operators
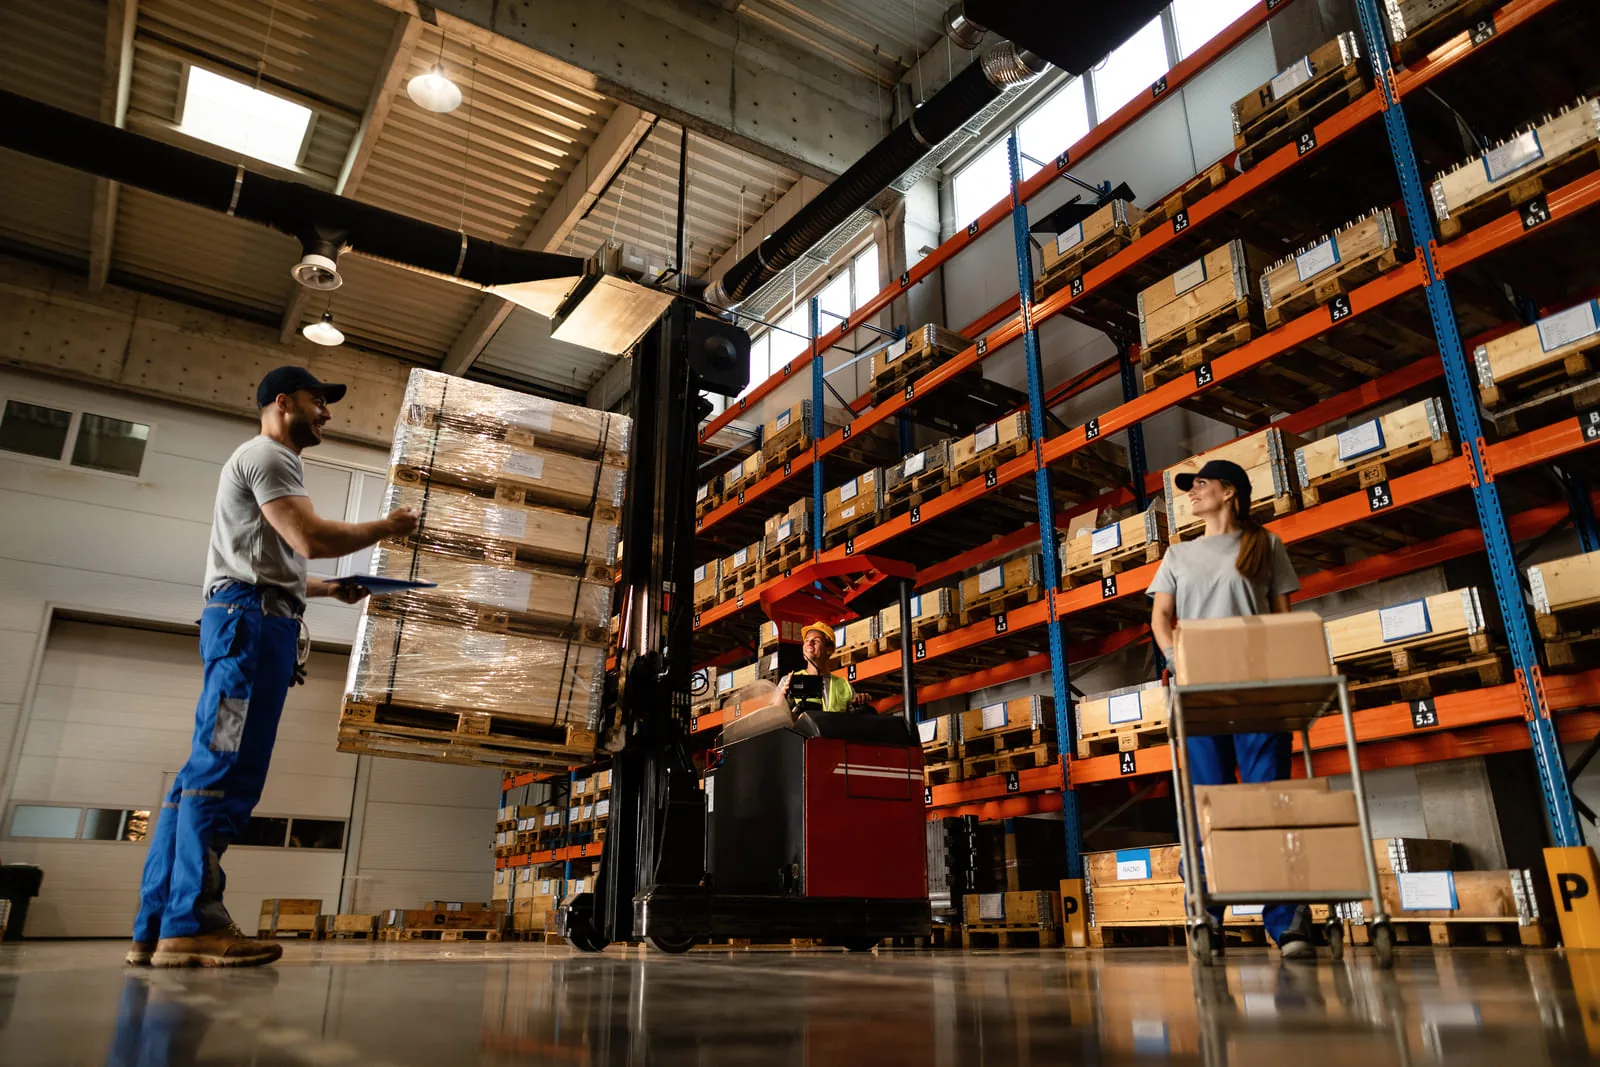
Fleets are typically financed vehicle by vehicle, each agreement priced against an asset that loses value with every kilometre. A second mortgage behind the first on the depot is priced against that property.
It is repaid from contract receipts, or an asset finance takeout. A property does not depreciate on a schedule, and the rate reflects that.
A low cost second mortgage can help you:
- Borrow against the depot property rather than against depreciating trucks
- Replace chattel finance priced on a vehicle's residual
- Fund a ramp-up without a rate set by the age of the fleet
- Improve the rate with a lower loan to value ratio on the depot
- Get a sharper rate where a signed contract underwrites the exit
- Price against property rather than against kilometres travelled
Low cost second mortgage loans for technology companies
Technology lending is usually offered unsecured or as venture debt, priced for the risk of lending to a business with no tangible assets. A low cost second mortgage is priced against property equity instead, which is why the rate is lower.
It is repaid when the round closes or a longer facility settles. No equity is given up to fund the gap, there is no warrant attached and no board seat, and the cost is a rate rather than a share of the company.
A low cost second mortgage can help you:
- Fund a shortfall without giving up equity in the company
- Replace venture debt carrying warrants and a covenant package
- Borrow at 11.95% p.a. rather than at a price set for unsecured lending
- Fund a bridge without resetting the valuation from the last round
- Take a facility with no warrant, no board seat and no information rights
- Fund an acquisition without an equity raise to pay for it
Low cost second mortgage loans for practices and professional firms
Practice finance is often offered unsecured, or on goodwill, and priced for the fact that goodwill depends on people who can leave. A second mortgage behind the first on a director's property is priced against the property.
It is repaid when the long-term practice facility settles. Goodwill is not what we lend against, and that is precisely why the rate is what it is.
A low cost second mortgage can help you:
- Borrow against property rather than against practice goodwill
- Replace an unsecured practice loan priced for having no security
- Fund a buy-in without a rate set by a valuation of goodwill
- Improve the rate with a lower loan to value ratio on the property
- Get a sharper rate where an approved practice loan is the exit
- Price against bricks rather than against a client list
Low cost second mortgage loans for property developers
The usual answer to a development equity gap is mezzanine debt, priced for sitting behind a senior lender with very little between it and a loss. A second mortgage over the site or the completed stock is still second, but it is priced against real property with a defined settlement behind it.
It is repaid when the stock settles, or when the senior facility is retired. A lower loan to value ratio across both charges, and a sell-down already under way, is what moves the price.
A low cost second mortgage can help you:
- Close an equity gap without paying mezzanine pricing
- Replace a mezzanine facility priced for a thin equity buffer
- Fund holding costs against real property, not against a forecast
- Improve the rate with a lower combined loan to value ratio
- Get a sharper rate where a sell-down is already under way
- Price against settled contracts rather than against a feasibility
Low cost second mortgage loans for property investors
An investor needing capital behind an existing first mortgage is usually quoted private second mortgage pricing set for a single, highly geared title. Spreading the security across a portfolio, or lending at a lower loan to value ratio, changes what that facility should cost.
It is repaid when a property sells, or when the position is refinanced. The rate follows the security and the exit, and both are things a portfolio can improve.
A low cost second mortgage can help you:
- Spread security across several titles to bring the rate down
- Borrow behind a first at a lower combined loan to value ratio
- Replace expensive private debt taken on to complete a purchase
- Get a sharper rate where a signed sale contract is the exit
- Fund a deposit without paying a single-title risk premium
- Use a tenanted asset to evidence a cleaner exit
"Second mortgage pricing is driven by the combined LVR across the full debt stack and the quality of the exit. Where the title information is clean, the combined LVR sits under 70%, and the repayment timeline is well defined, we are able to offer the most competitive terms in this product category, and we are happy to show how the pricing comes together."
Gino Tabila
Associate Director
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
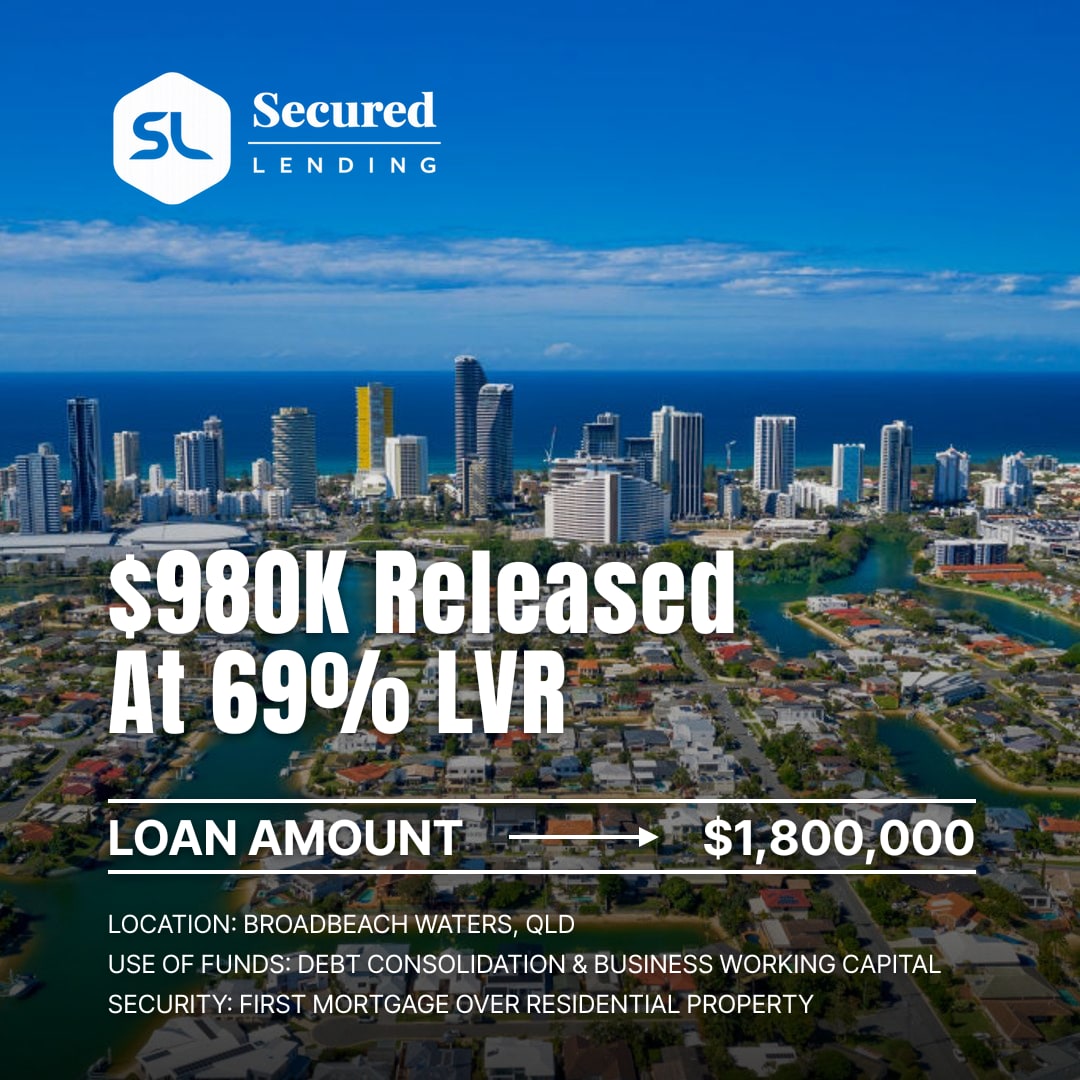
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
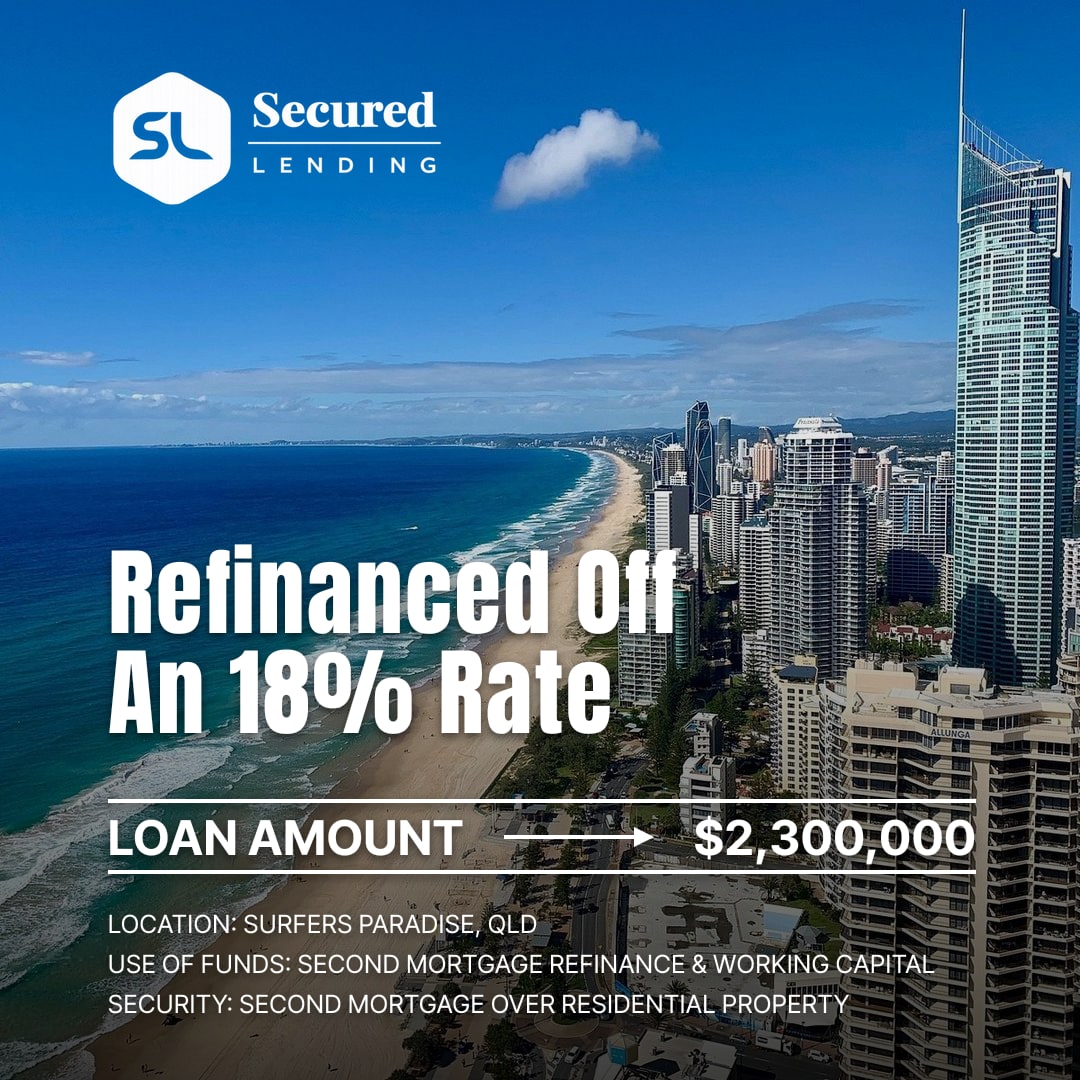
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
Recently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Scenarios We Can Help With
Browse our full range of services, industries, locations, and resources to find the right financial solution for your needs.