Private Working Capital Loans, Funded in 24 Hours
Cash flow to keep the business running while you wait to get paid
Experts in strategic, short-term finance
Some businesses that call us are growing and need cash to take on more work. Others, in construction and hospitality especially, are topping up cash flow through a hard trading year, with wages, suppliers and the ATO due before the revenue arrives. A working capital loan tops up the business bank account so your business keeps paying its team and its suppliers on time.
A bank reads a cash flow gap as a serviceability question and takes weeks to answer it. We read it as a timing question, and the answer comes back the same day. We lend our own money, hold our own credit authority and do our own valuations, which is why a file can go from enquiry to settled inside 24 hours rather than sitting in a queue while the deadline that prompted the call goes past.
What You Can Use It For
- •Pay the team on time through a revenue dip, a seasonal trough or a late progress claim
- •Clear supplier invoices that have gone past terms and put the relationship at risk
- •Buy stock and inventory ahead of a peak period or a large order
- •Purchase equipment, tooling or a vehicle the next job depends on
- •Fund an expansion: a second site, a fit-out, a new line, more people
- •Cover an ATO bill, BAS or superannuation obligation before it escalates
- •Meet legal, settlement or professional costs that fall due before the money arrives
- •Move on a time-sensitive opportunity that will not wait for the next receipt
Who We Lend To
Business purpose only. Beyond that we are considerably broader than a bank:
- •Companies and trusts, including layered or otherwise complex structures
- •Businesses with seasonal, lumpy or project-based income
- •Borrowers whose credit history is imperfect where the equity is there
- •Self-employed borrowers without a full set of current financials
- •Businesses recently declined by a bank on serviceability rather than on the numbers
- •SMSF borrowers, subject to the usual compliance requirements
What It Costs, and How Long It Runs
- •Loan amounts from $250,000
- •Rates from 9.7% p.a., interest only, so the monthly cost stays predictable
- •Terms from 1 to 24 months, with 3 to 6 months typical on a working capital file
- •Up to 70% LVR
- •First and second mortgages, so an existing bank loan can usually stay where it is
- •Same day assessment, and settlement within 24 hours on a clean title
The Security Does Not Have to Be the Business Premises
This is the point most borrowers are surprised by, and it is why a business that leases its premises can still borrow. The loan is secured by a first or second mortgage over residential, commercial or industrial property, and that property does not need to be the premises the business trades from. A director can offer a home or an investment property instead, held personally, in a company or in a trust.
What the money then pays for is a separate question. Stock, wages, equipment, suppliers and tax are all ordinary uses of a working capital facility, and none of them is what the loan is written against.
Working Capital Loans With Bad Credit
A business that has been short of cash for a while usually has a credit file that shows it. Late payments, a default, sometimes an ATO listing. A bank treats that as the answer. We treat it as context, then look at the equity available and what repays the facility. Full financials are not required on an asset-backed file.
Industries We Service
Topping up working capital for builders and contractors
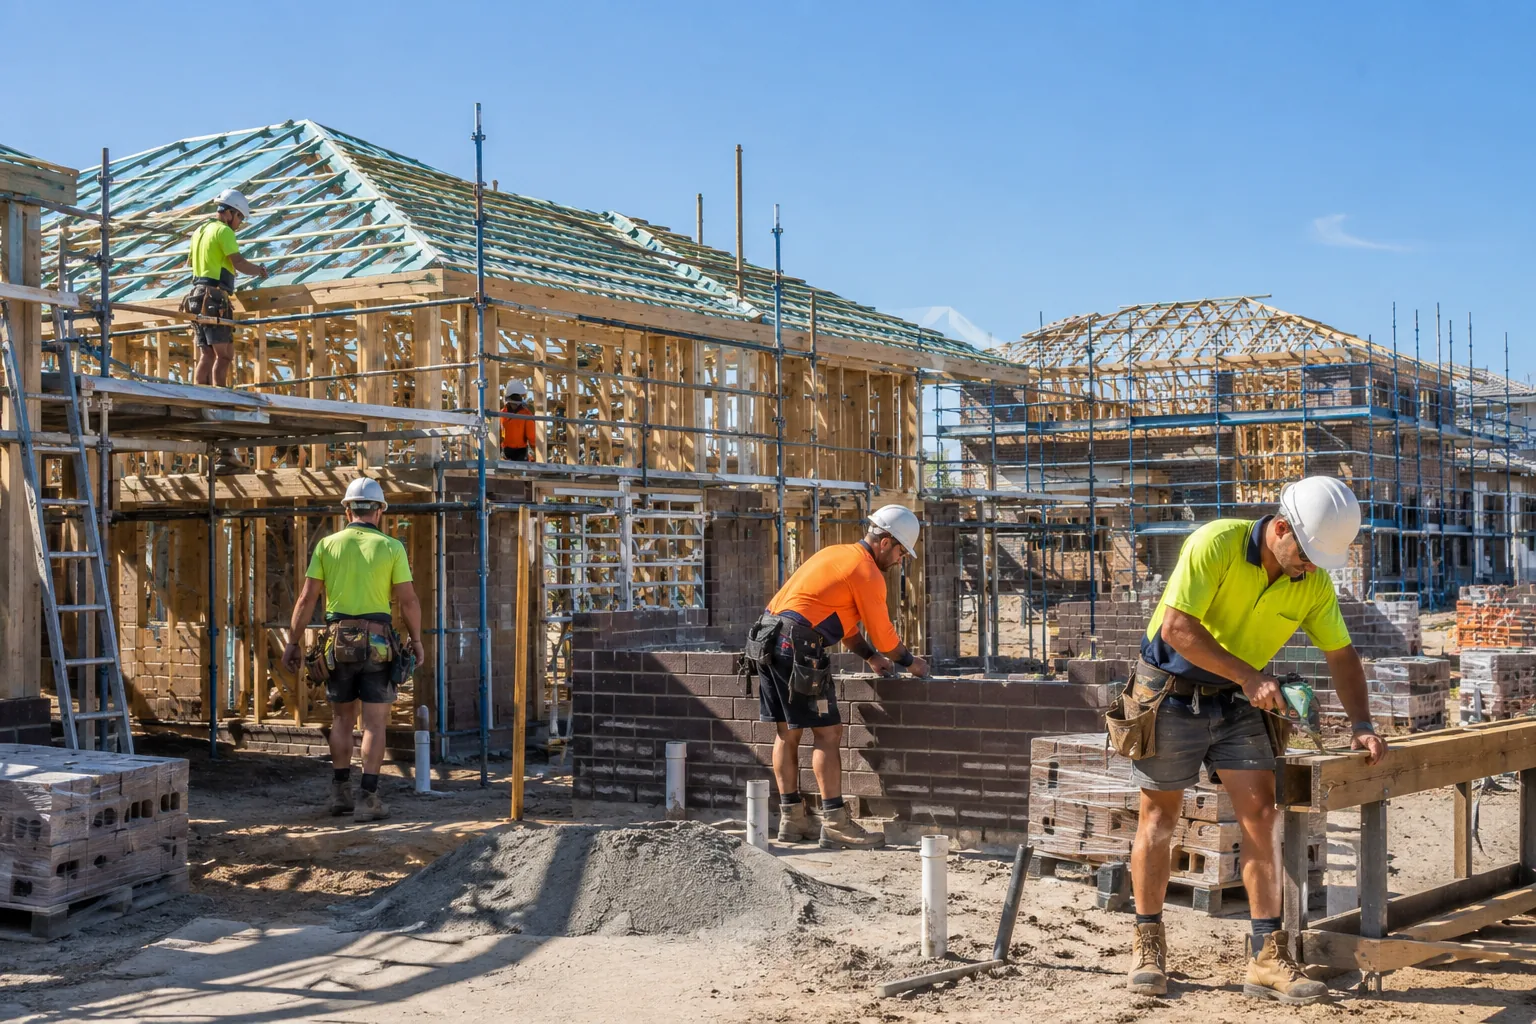
A working capital loan tops up the business bank account when progress claims and retentions are paid late but wages, subcontractors and suppliers are due every week. It covers the payroll, the materials order and the plant hire that fall due before the next payment arrives.
It is repaid when the late claims and retentions are paid, or from a refinance. Your crew stays on site and your supplier accounts stay within terms, and because we lend our own funds the answer does not wait on a committee.
A working capital loan can help you:
- Pay wages and subcontractors every week while a progress claim is overdue
- Keep supplier accounts within terms so materials keep arriving on site
- Carry a retention that is being released later than the contract said
- Fund a variation while it is still being argued
- Cover plant hire and site costs through a slow payment run
- Clear an ATO debt before it puts a licence or a tender at risk
Working capital for wholesalers and importers
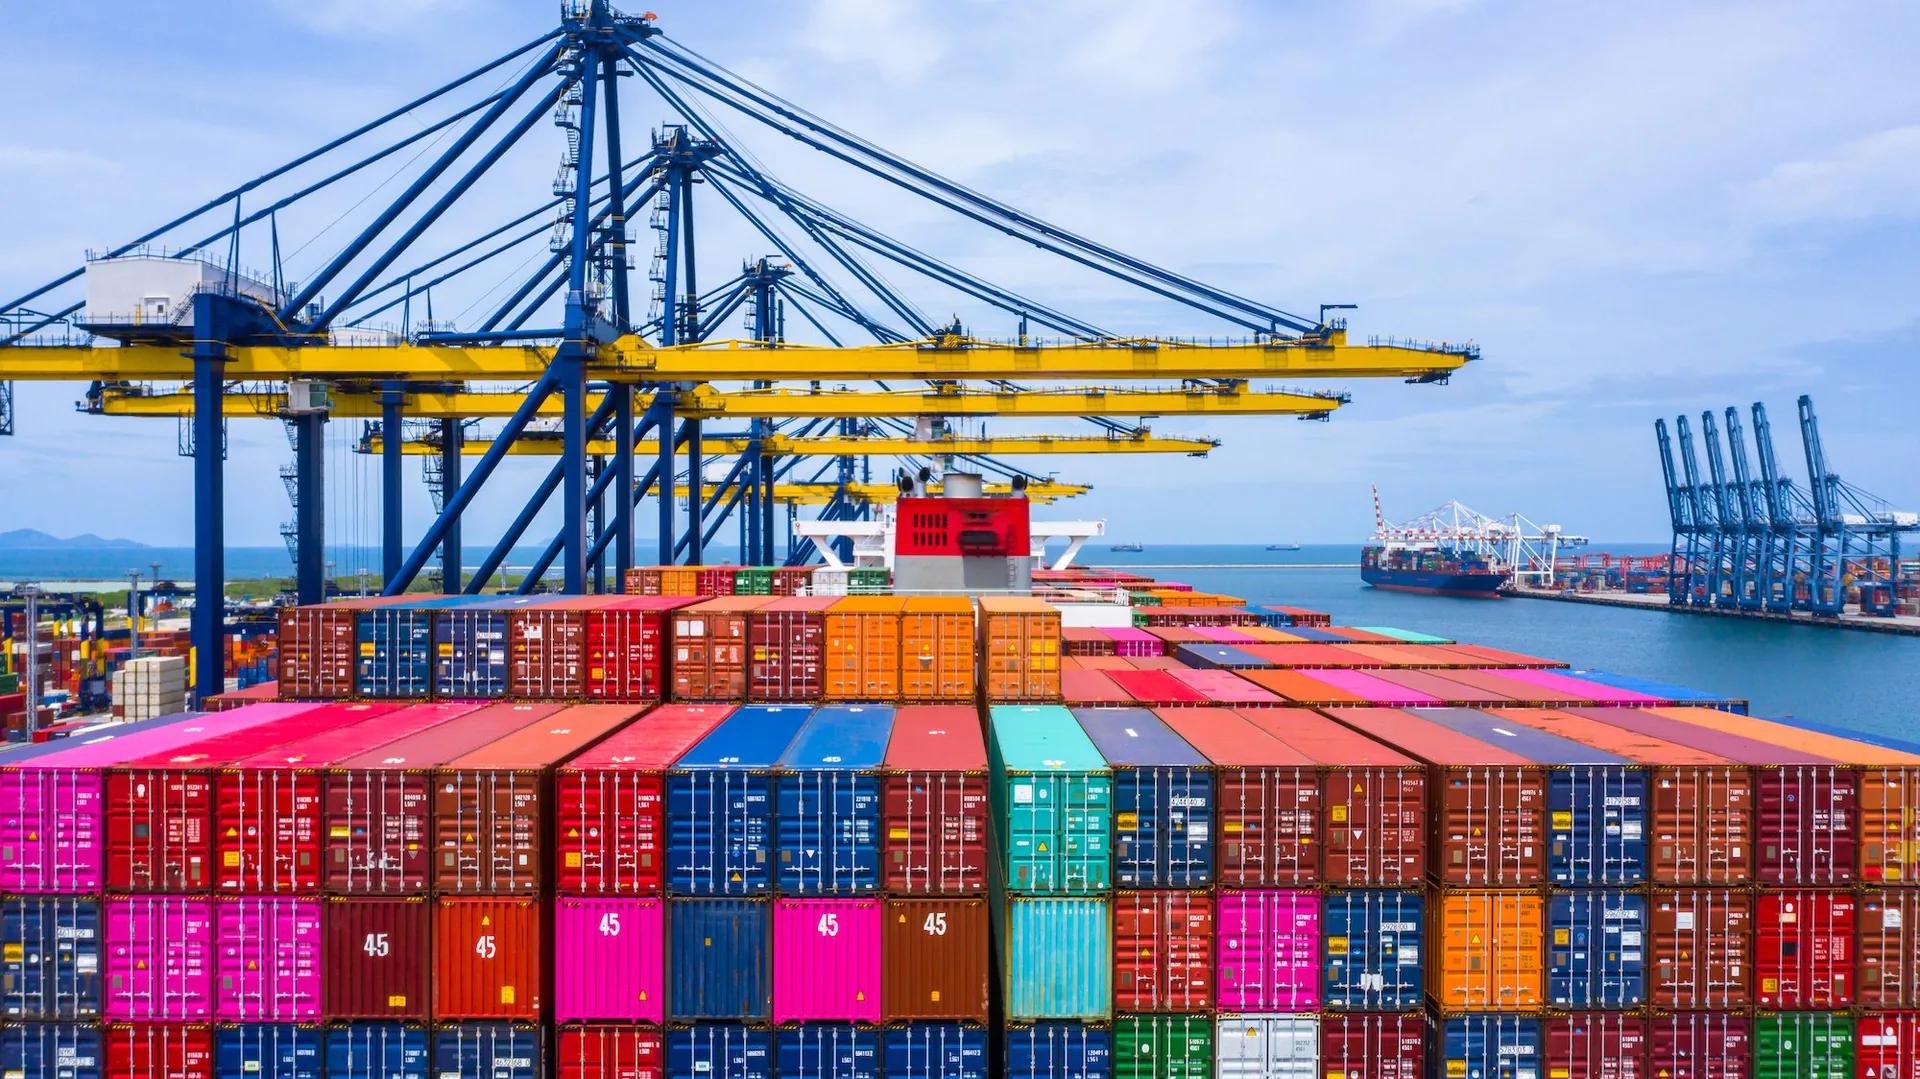
A working capital loan pays the supplier and clears the shipment months before the stock sells through and the customer settles. We lend against the warehouse where it is owned, and against a director's property where the premises are leased.
It is repaid as the stock sells through, or when the debtor pays. The practical effect is that the order goes in at the size the season actually needs, rather than the size the last container left room for.
A working capital loan can help you:
- Pay a supplier months before the stock sells through
- Cover customs, freight and storage on goods already in transit
- Bridge the gap between paying a supplier and being paid by a customer
- Order at the size the season needs rather than the size the account allows
- Carry the extended terms a major customer has negotiated
- Borrow against the warehouse, or a director's property on a leased site
Working capital for retailers
A working capital loan buys peak season stock in the months before the takings arrive, and covers rent, wages and supplier accounts through the quiet part of the year. Most retailers lease their space, so the security is usually a director's home or an investment property rather than the shop.
It is repaid out of the season the stock was bought for. That means the range is set by what the season will sell rather than by what a slow quarter left in the account, and a discount that only holds for a short window can be taken rather than watched.
A working capital loan can help you:
- Buy peak season stock months before the takings arrive
- Cover rent and wages through the quiet part of the trading year
- Take a supplier discount that only holds for a short window
- Fund a range expansion ahead of the season that pays for it
- Clear supplier accounts that have drifted past terms
- Borrow against a director's home or investment property, not the shop
Working capital for software and technology companies
A working capital loan covers salaries, cloud and licensing costs, and customer acquisition spend across the months between delivering the work and collecting the fee. In technology that gap is structural: enterprise customers pay on 60 and 90 day terms, and the payroll behind the work runs fortnightly.
It is repaid as the invoices are collected, or by a raise or a refinance once the run rate supports one. The company can hire against work it has already won rather than waiting for its slowest customer to pay.
A working capital loan can help you:
- Pay salaries while enterprise invoices sit on 60 and 90 day terms
- Carry annual cloud and licensing commitments billed in advance
- Fund customer acquisition spend recovered over the life of the customer
- Deliver a contract that bills only on acceptance
- Onboard a large customer whose implementation runs for months
- Cover a payroll that runs fortnightly against revenue that arrives quarterly
Working capital for manufacturers
A working capital loan funds the materials, tooling and labour on an order the customer will not pay for until delivery. Owner occupiers secure against the industrial property. Leaseholders secure against a director's property, which is the usual pattern on a leased site.
It is repaid when the customer pays on delivery, or by a longer-term facility once the order is invoiced. A large order is accepted rather than turned away because the build cycle is longer than the working capital line can stretch.
A working capital loan can help you:
- Fund materials, tooling and labour on an order paid only on delivery
- Take on an order larger than the current working capital line allows
- Cover a long build cycle where payment comes only at the end
- Absorb a raw material price rise partway through a contract
- Keep production running through a customer paying late
- Release equity from the factory without stopping the line
Working capital for transport and logistics operators
A working capital loan covers fuel, wages and maintenance across the 30 to 60 days between running the freight and being paid for it. We lend against the depot or warehouse, and against a director's property where the site is leased. We lend against property, not against the trucks.
It is repaid from contract receipts, or by a refinance once the run is established. A contract that has been won starts on its start date rather than when the previous one finally pays.
A working capital loan can help you:
- Cover fuel, wages and maintenance across a 60-day payment cycle
- Start a new contract before the previous one has paid
- Meet a fleet compliance or registration bill that cannot wait
- Fund a seasonal freight peak
- Bridge the gap between winning the work and being paid for it
- Borrow against the depot, or a director's property on a leased site
Topping up working capital for pubs, hotels and venues
A working capital loan tops up the venue's cash through a quiet season, when takings fall but wages, rent and supplier bills are still due every week. Where supplier costs have gone up, it covers the difference until trade picks up again.
It is repaid out of the trading season that follows, or from a refinance. Your staff are paid on time and your suppliers stay on terms, and a quiet winter is read as a timing pattern rather than a credit weakness.
A working capital loan can help you:
- Pay wages on time while takings are down in the off season
- Keep supplier accounts paid on time through the quiet months
- Carry rent and outgoings between trading peaks
- Stock up ahead of a function season or a major local event
- Clear supplier accounts before the busy period starts
- Fund a refurbishment in the months the venue is quiet
Working capital for property developers
A working capital loan covers rates, land tax, interest and consultants while a project runs and before any stock settles. We lend against the land, the completed stock, or another property in the portfolio, as a first or second mortgage.
It is repaid when the stock settles or a construction facility takes over. Holding costs on the current project stop being funded by discounting the last few lots of the previous one.
A working capital loan can help you:
- Cover rates, land tax and holding costs while a project runs
- Pay planners and consultants before any stock has settled
- Carry interest on a site through an approval delay
- Fund the marketing and display campaign ahead of a sell-down
- Cover the gap between a construction drawdown and the bills it pays
- Avoid discounting the last lots of the previous project to raise cash
Working capital for practices and professional firms
A working capital loan covers salaries, rent and equipment across the months between doing the work and collecting the fee, which in these firms is often long. Rooms and offices are almost always leased, so the security is a director's home or investment property.
It is repaid as the fees are collected, or by a practice facility once the year is on the books. The firm is not forced to chase its own clients harder than the relationship can stand.
A working capital loan can help you:
- Pay salaries while fees are still sitting in work in progress
- Carry rent and outgoings through a slow collection cycle
- Fund equipment or a fit-out ahead of the revenue it generates
- Cover partner drawings while a long matter runs to completion
- Meet an ATO or superannuation obligation on the due date
- Borrow against a director's home or investment property
Working capital for agencies and property investors
A working capital loan covers wages, marketing and office costs across the months between winning a listing and the commission arriving at settlement. Agencies lease their offices, so the security is a director's own home or a property held in the investment portfolio.
It is repaid on settlement, or by rent once an investment asset is tenanted. Campaign spend is then set by what the property needs to sell, rather than by what last month happened to settle.
A working capital loan can help you:
- Pay wages and marketing between winning a listing and settlement
- Fund a campaign on a property that will not settle for months
- Carry an agency through a slow quarter of settlements
- Cover holding costs on an investment property between tenants
- Fund a renovation that brings a property up to a rentable standard
- Borrow against the portfolio, or a director's own property
Working capital for childcare and early learning centres
A working capital loan covers wages, superannuation and supplier costs while Child Care Subsidy payments follow later, part of a payment is withheld, or the subsidy for a family stops until its details are updated. Educators are paid weekly or fortnightly, so a centre can be full and still be short of cash on payday.
It is repaid from trading income once the subsidy payments arrive, or by a refinance. The loan is interest only, so there are no monthly repayments drawing on the same cash the centre needs for payroll.
A working capital loan can help you:
- Pay educators on the normal payroll date before subsidy payments arrive
- Cover the part of a subsidy payment that has been withheld
- Meet the required educator-to-child ratios while cash is short
- Fund the first months of a new centre while enrolments build
- Pay suppliers on time when a family's subsidy has stopped
- Repay from trading income once the subsidy payments are made
Working capital for medical, dental and allied health practices
A working capital loan covers wages for nurses, receptionists and practice managers, rent, insurance and equipment leases, while health fund payments and patient accounts arrive on their own timetable. It also carries the cost of a new practitioner for the months it takes to build a full appointment book.
It is repaid from practice income, or by a bank refinance once the busier months are on record. The same loan can consolidate several business debts into one, so the practice deals with one lender instead of several.
A working capital loan can help you:
- Pay nurses and receptionists while health fund payments are outstanding
- Carry a new practitioner until their appointment book is full
- Meet rent, insurance and equipment lease payments each month
- Roll several practice debts into one loan
- Cover running costs at a new location before its rooms bill patients
- Move to a bank refinance once the busier months are on record
Working capital for dealers, workshops and panel beaters
A working capital loan covers wages, parts suppliers and rent while insurer and fleet customer payments take weeks to arrive, and carries staff and marketing costs through a quiet sales quarter. It is paid to the company as a lump sum and kept separate from the floor plan, which stays with its own lender.
It is repaid by a refinance or by a sale and leaseback of the premises property. We release capital against property, never against the vehicles, the parts stock or the dealer agreement.
A working capital loan can help you:
- Pay workshop wages while insurer payments are outstanding
- Cover parts supplier accounts during a wait on fleet customers
- Carry staff and marketing costs through a quiet sales quarter
- Fund working capital without changing how your vehicles are financed
- Take on a larger repair workload before it is invoiced
- Repay from a refinance or a sale and leaseback of the premises
"Most working capital deals we do are for businesses trading perfectly well that are simply waiting to be paid. A builder whose progress claim has not been certified yet. A wholesaler who has paid for a container that is still on the water. Tell us the amount you need, the property you can offer and roughly when the money comes in, and we can usually get terms back to you the same day."
Gino Tabila
Associate Director
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
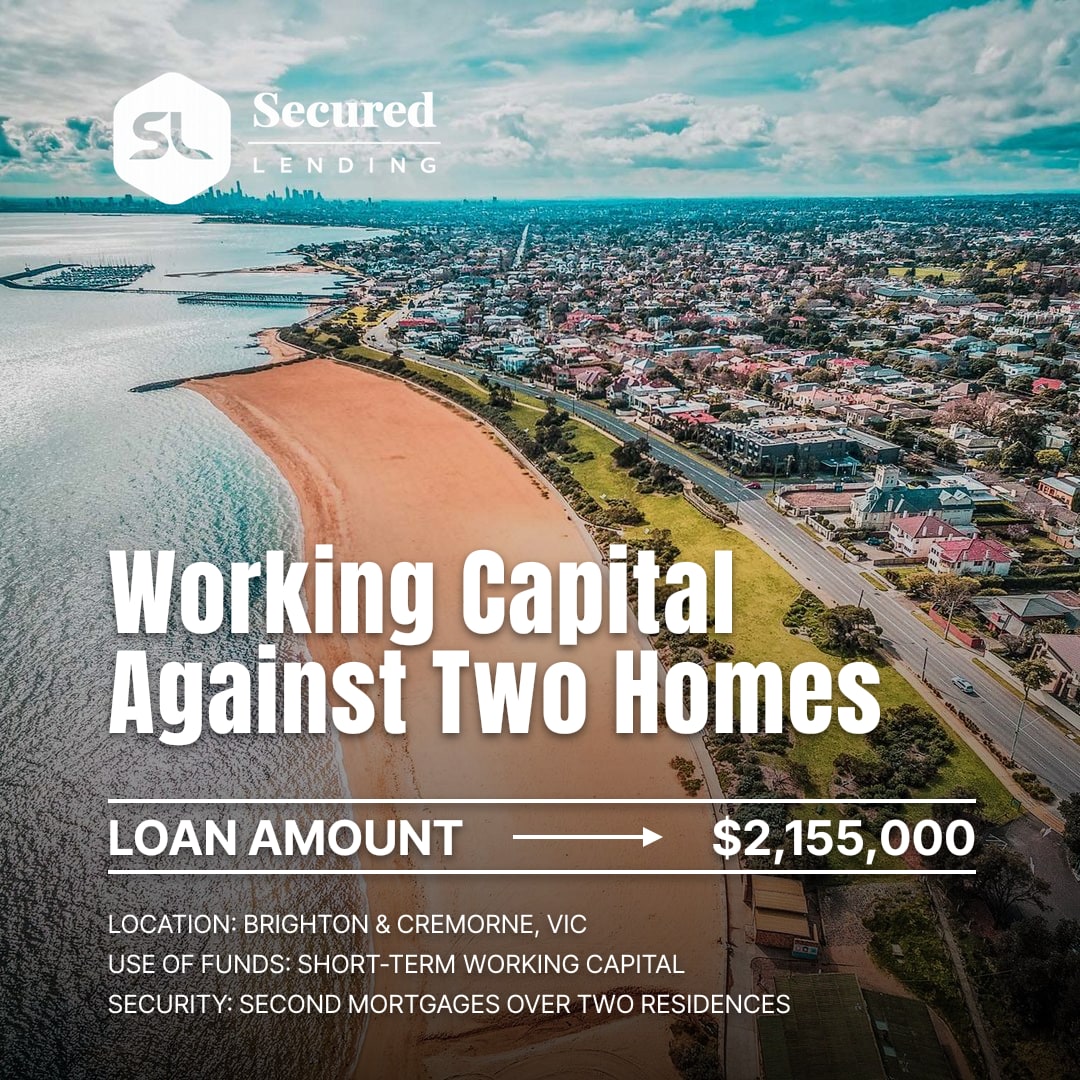
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
Recently Asked Questions
Related Products
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Working Capital Scenarios We Fund
Grouped by which side of the cash-flow cycle opened the gap. Each one is written up in full.