Private Lender for Healthcare and Medical Practices
Settle the practice, the premises or the fit-out on the date it is due, with a loan secured by property
Experts in strategic, short-term secured finance
Secured Lending is a private lender, and we work with medical, dental, allied health, pharmacy and veterinary practices across Australia. When a practice purchase, a fit-out or a tax bill has a date, a bank can take months to say yes. We lend our own funds from $250,000, secured by real property your company or a director owns, and we can make a decision in hours. If your practice has a date to meet, we would be glad to help.
Who We Help
- General practices and medical centres, including a practice buying the centre it has leased for years
- Dental and orthodontic practices, from a single surgery to a group across several sites
- Specialists, day surgeries and day hospitals adding a procedure room, a theatre or a second suite
- Allied health practices in physiotherapy, psychology, podiatry, optometry and diagnostic imaging
- Pharmacists buying a pharmacy or the building it trades from, through a company the state ownership rules permit
- Veterinary clinics and animal hospitals fitting out surgical and imaging rooms
- Practitioners buying a retiring principal's practice, or the shares of a departing partner
- Practices owing pay as you go withholding, goods and services tax or superannuation to the Australian Taxation Office
How We Can Help You
- Settle a practice or pharmacy purchase on the date written into the contract, with a decision usually within hours of a complete enquiry
- Pay for goodwill, a fit-out, dental chairs or imaging equipment as a lump sum at settlement
- Keep your existing bank loan in place, because a second mortgage sits behind it rather than replacing it
- Borrow where the practice leases its rooms, using a director's home or investment property as the security
- Clear a tax debt in one payment so the general interest charge stops building on the balance
- Choose a term from 1 to 24 months, typically 3 to 6 months while longer-term finance is approved
Healthcare Finance Scenarios We Fund
A dentist buying a retiring principal's surgery needs a different loan to a pharmacist relocating, or a veterinary hospital building a new theatre. Below are the situations practices bring to us most often.
Buying a practice or a partner's share
A practice sale usually has a settlement date set around a retiring principal or the end of a lease, and much of the price is goodwill. The same applies when a partner leaves and the practice agreement fixes the date and the price of their shares. The buyer often has equity in a home and very little of the price in cash.
We fund general practitioners, dentists, specialists and allied health practitioners buying practices, medical centres and the shares of departing partners. The loan pays the purchase price, the fit-out and the equipment at settlement, and your practice repays us with longer-term finance once the first months of trading under the new ownership are on record.
- Funds goodwill, a fit-out, equipment or a partner's shares
- Settles on the date in the sale contract or practice agreement
- Decision usually within hours of a complete enquiry
- Lending to companies, including a company acting as trustee
- Second mortgage available behind an existing bank loan
- Exit is longer-term finance once trading is on record
Buying a pharmacy
A pharmacy purchase has steps most business sales do not. State laws restrict who may own a pharmacy, and in New South Wales a pharmacist cannot hold an interest in more than five pharmacies. The new owner must also apply for approval to supply medicines under the Pharmaceutical Benefits Scheme, and the Department of Health asks for that application at least 30 days before settlement.
We lend to companies whose directors and shareholders are registered pharmacists where the state allows it, and we cannot fund a purchase by anyone the law does not permit to own the pharmacy. Our loan documents give us no control of the pharmacy and no share of its profits. Your lawyer confirms how the rules in your state apply, and your company repays us once longer-term finance is in place after the approval is issued.
- Funds the purchase price, the stock and a fit-out at settlement
- Only for buyers the state ownership rules permit
- No control of the pharmacy and no share of its profits
- Your lawyer confirms the ownership rules in your state
- Term set to cover the approval and the refinance
- Exit is longer-term finance or the sale of another property
Buying the centre or suite you lease
A landlord decides to sell the medical centre, the strata suite or the clinic building the practice has traded from for years, and offers it to the tenant first. The offer has a deadline, and losing the building can mean losing the location patients know.
We fund the purchase of the property, and the property being bought can secure the loan alongside another property you or your company own. Our valuation team is in-house, so a medical centre or a specialised clinical building is valued directly rather than waiting in an external valuer's queue. The exit is a long-term commercial loan once the purchase has settled.
- Funds a medical centre, a strata suite or a clinic building
- The property being bought can secure the loan
- In-house valuation of specialised clinical property
- Up to a 70% loan-to-value ratio across all mortgages
- Settles on the date in the landlord's offer
- Exit is a long-term commercial loan
Fit-outs, new rooms and equipment
A day surgery adds a procedure room, a dental group opens another site, an imaging practice installs a new scanner, or a veterinary hospital fits out a surgical theatre. The builder, the equipment supplier and the new staff are all paid before the new rooms bill a single patient.
The loan is paid as a lump sum, so the fit-out finishes on schedule and the equipment is installed when the rooms open. Services Australia says a practitioner needs an additional provider number to work at a new practice location, so that application runs alongside the build. Your practice repays us from longer-term finance once the new rooms are trading.
- Funds building work, chairs, scanners and surgical equipment
- Paid as a lump sum when the work needs paying
- Provider number application runs alongside the build
- Suits day surgeries, dental groups, imaging and veterinary practices
- Terms from 1 to 24 months, most 3 to 6
- Exit is longer-term finance once the rooms are trading
Bridging finance for a practice move
A practice buys larger rooms before its current freehold is sold, or a pharmacy relocates and needs the new premises secured first. The purchase and the sale rarely settle on the same day.
A bridging loan pays for the new premises on the contract date, and your practice sells the old property at a fair price rather than discounting it to meet a deadline. Bridging is one of our core products, and the loan is repaid from the sale proceeds or from the long-term loan on the new premises.
- Funds the new premises before the old property sells
- The old property sells at a fair price, not a forced one
- Both properties can secure the loan together
- Fit-out of the new rooms can be funded at the same time
- Settlement within 24 hours on a complete file
- Exit is the sale proceeds or a long-term loan
Refinancing a bank loan
A bank can reduce or withdraw a practice loan at review, even where every repayment has been made, because profits paid out to the principals leave less on the page than the practice actually earns. A bank's health team can also take months to approve a new loan after a change of ownership.
We refinance the bank loan so your practice meets the date in the bank's letter. That gives you time to arrange the next long-term loan properly rather than accepting the first offer made under a deadline.
- Refinances an expiring, reduced or withdrawn bank loan
- Meets the date in the bank's letter
- First or second mortgage, depending on what is registered
- Time to compare long-term lenders before choosing one
- No practice or personal assets sold to meet a review date
- Exit is a refinance to a bank or a specialist health lender
ATO tax debt
Pay as you go withholding on a large staff payroll and superannuation for employed staff can build into a large ATO balance, and the general interest charge keeps adding to it. Once a payment plan is broken, recovery action can escalate to a garnishee notice or a director penalty notice.
The loan is paid to your practice company, which pays the ATO in full in one payment. One loan can cover income tax, activity statement debts and the superannuation guarantee charge together, and we can still lend after a director penalty notice or a garnishee notice has arrived.
- Clears the full ATO balance in one payment
- Stops the general interest charge building on the debt
- Covers income tax, activity statements and superannuation
- Available after a director penalty notice has arrived
- Clears the tax debt ahead of a bank refinance
- Exit is a refinance or the sale of a property
Working capital for a practice
Wages for nurses, receptionists and practice managers, rent, insurance and equipment leases fall due every month, while health fund payments and patient accounts arrive on their own timetable. A new practitioner can take months to build a full appointment book, and the practice pays their costs from the first day.
We provide a lump sum that covers wages and running costs through that period, and the loan can also consolidate several business debts into one. Your practice repays us from its income or from a bank refinance once the busier months are on record.
- Covers wages, rent, insurance and equipment leases
- Consolidates several business debts into one loan
- Second mortgage leaves the first mortgage untouched
- Covers a new practitioner's costs until their book is full
- Terms from 1 to 24 months, most 3 to 6
- Exit is practice income or a bank refinance
Our Loan Products
- First mortgage: from 9.7% p.a., over the medical centre, consulting suite or clinic property your company owns, or over an unencumbered home or investment property
- Second mortgage: from 11.95% p.a., sitting behind your existing bank loan so it does not need to be refinanced to fund a purchase or a fit-out
- Bridging loans: for buying new rooms or a relocated pharmacy before your current property sells
- Caveat loans: our fastest product, lodging a caveat over the property rather than registering a full mortgage, for a settlement or tax deadline days away
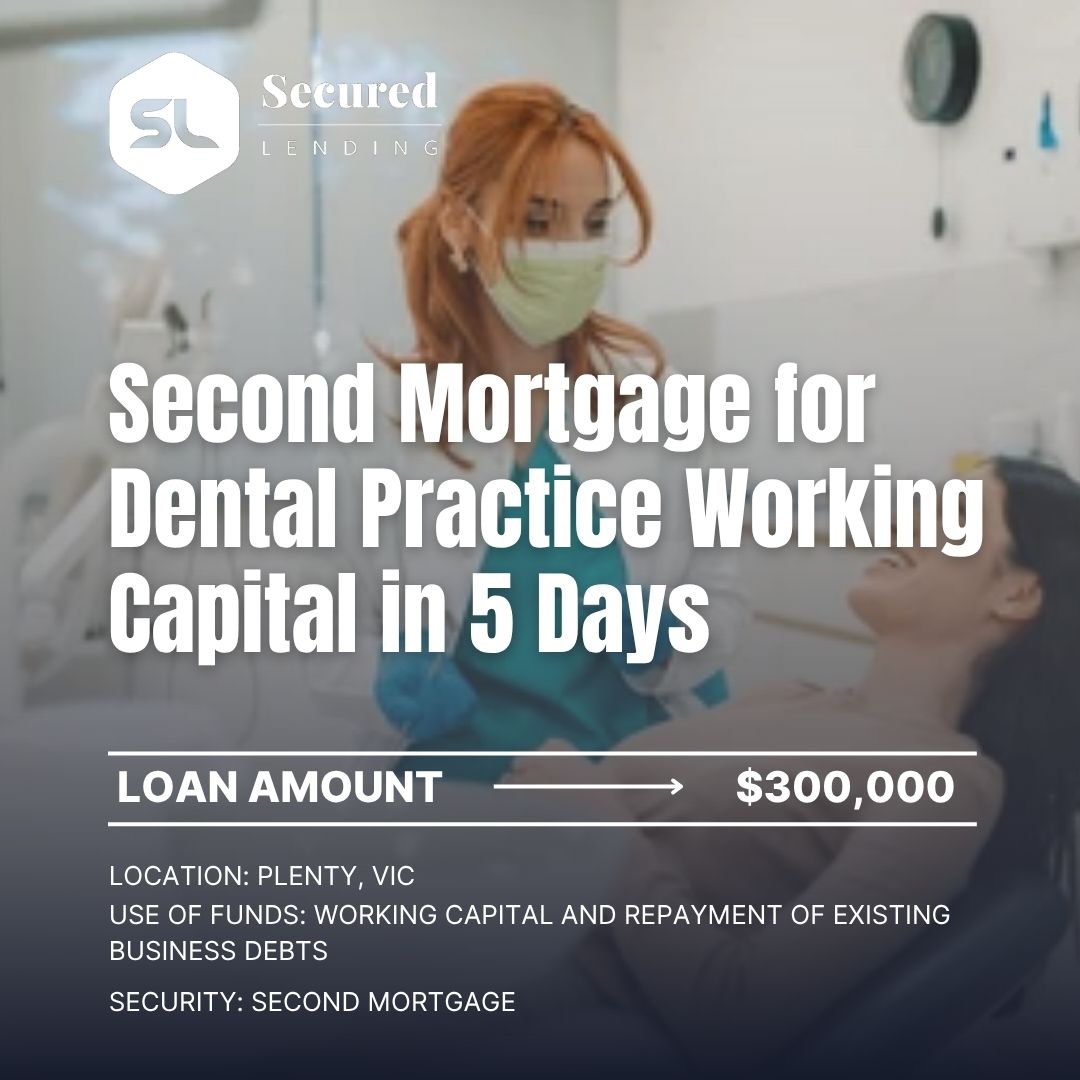
Case study: $300,000 for a dental practice in 5 business days
A dental practice in Plenty, Victoria, needed working capital and wanted to consolidate several existing business debts, with a refinance to a major bank planned within 12 months. We issued indicative terms within 1 hour of the enquiry and a letter of offer within 3 hours, and a $300,000 second mortgage settled within 5 business days. The second mortgage left the existing first mortgage in place, and the planned bank refinance is the exit.
Related Reading
- →Urgent short term finance to buy a medical or dental practice
- →Urgent short term loans for pharmacists buying a pharmacy
- →Private lender for medical practice finance
- →Private lender for a medical centre acquisition
- →Private lender for dental clinic finance
- →Private lender for allied health practice finance
- →Private lender for veterinary practice finance
"Most practices that come to us are busy and profitable. What holds them up is timing. A retiring principal has a settlement date, a landlord wants an answer on the building, and the bank wants a specialist valuation and months of trading before it will lend. We lend our own funds and value the property in-house, so the practice can settle on the contract date and move to bank finance once the bank has what it needs. We are always glad to talk a purchase through early, well before the settlement date gets close."
Gino Tabila
Associate Director
Recently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
$2.155M Second Mortgage Working Capital Facility Across Brighton and Cremorne
$280K Second Mortgage for Short-Term Cash Flow in Kooyong
$545K Bridging Loan Across Three Suburbs in Melbourne's North-West
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours