Urgent Short Term Finance to Pay Your ATO Debt Before the Deadline
Pay the ATO in full, stop the interest charges, and repay us on terms that suit your business
Experts in strategic, short-term finance
A tax debt can build up quickly when cash flow is uneven, and the ATO has become much firmer about collecting it. If you have received a garnishee notice, a director penalty notice or a warning that your payment plan will be cancelled, we can fund the full amount in as little as 24 hours.
Paying the ATO in one amount stops the general interest charge and ends the recovery action. You then repay us within 1 to 24 months, usually from a bank refinance once the debt is cleared or from the sale of a property, on terms agreed before you sign.
Tax debts the loan can clear
- •Company and income tax debts
- •BAS debts, including GST and PAYG withholding
- •Superannuation guarantee charge owed to the ATO
- •The general interest charge and penalties added to your ATO account
- •ATO debts owed by more than one business in your group
- •A lump sum the ATO has asked for before it will agree to a payment plan
Deadlines we help with
- •Director penalty notice: 21 days from the day the ATO posts the notice. If the company reported the debt more than 3 months late, or never reported it, paying it in full is the only way to have the penalty remitted
- •Garnishee notice: the ATO can collect directly from your bank account or from customers who owe you money until the debt is paid
- •Payment plan default: a missed instalment can cancel the plan and make the full balance payable
- •Statutory demand: 21 days to pay before the ATO can apply to wind up the company
- •Credit reporting: the ATO can report an overdue business tax debt of $100,000 or more to credit reporting bureaus if the business is not working with it to manage the debt
- •A bank refinance on hold, because the bank will not lend while the ATO debt is unpaid
We do not give insolvency advice. If you are unsure whether the company can pay its debts as they fall due, we can connect you with insolvency specialists in our network before you borrow.
Why waiting costs more
The general interest charge is calculated daily on the unpaid balance, and since 1 July 2025 it is no longer tax deductible. Interest on a loan used for business purposes generally is, so a short term loan can cost less than the headline rate suggests. Your accountant can confirm how this applies to your business.
From first call to paying the ATO
Today. Send us your ATO statement of account and any notice you have received. We call you back within hours with an indicative offer.
Within a day. Our valuers assess the property you are offering.
Letter of offer. Once you accept the terms, we issue the letter of offer straight away.
Settlement. Funds are released at settlement so the ATO can be paid the same day, in as little as 24 hours from a signed letter of offer.
What we need to see
- •Your ATO statement of account showing the current balance
- •Any DPN, garnishee notice, statutory demand or payment plan letter
- •The address of the property you can offer as security, and the balance of any existing mortgage
- •How you plan to repay the loan, for example a bank refinance or a property sale
- •Your accountant's contact details, if you would like us to work with them
Loans that can pay the ATO
- •ATO tax debt loans: our dedicated loan for clearing tax debts
- •Caveat loans: the fastest option when a deadline is days away
- •Second mortgage: behind your bank loan, without refinancing it
- •First mortgage: over an unencumbered property you own
- •Secured business line of credit: to cover future BAS and super payments as they fall due
Loan terms for ATO debt
| Loan feature | Detail |
|---|---|
| Loan size | $250,000 to $10,000,000 |
| Interest rate | From 9.7% p.a. (first mortgage), from 11.95% p.a. (second mortgage) |
| Term | 1 to 24 months, interest only |
| Repayments | Interest paid monthly, in advance or capitalised into the loan |
| Maximum LVR | 70%, including any existing mortgage |
| Security | A first or second mortgage over residential, commercial or industrial property, such as the business premises, your home or an investment property |
| Settlement | From 24 hours |
How you repay us
The repayment plan is agreed with you before settlement. The most common plans are a bank refinance once the tax debt is cleared, the sale of a property, or a known payment due to the business, such as the proceeds of a business sale. In many cases, borrowers move to a bank loan within 6 to 12 months.
ATO debts we have cleared
“Most business owners who call us about an ATO debt have a profitable business and a property with equity. The difficulty is timing: the ATO wants payment now, and the bank will not help while the debt is outstanding. We pay the ATO first, and the bank refinance can then go ahead.”
Gino Tabila
Associate Director
Frequently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
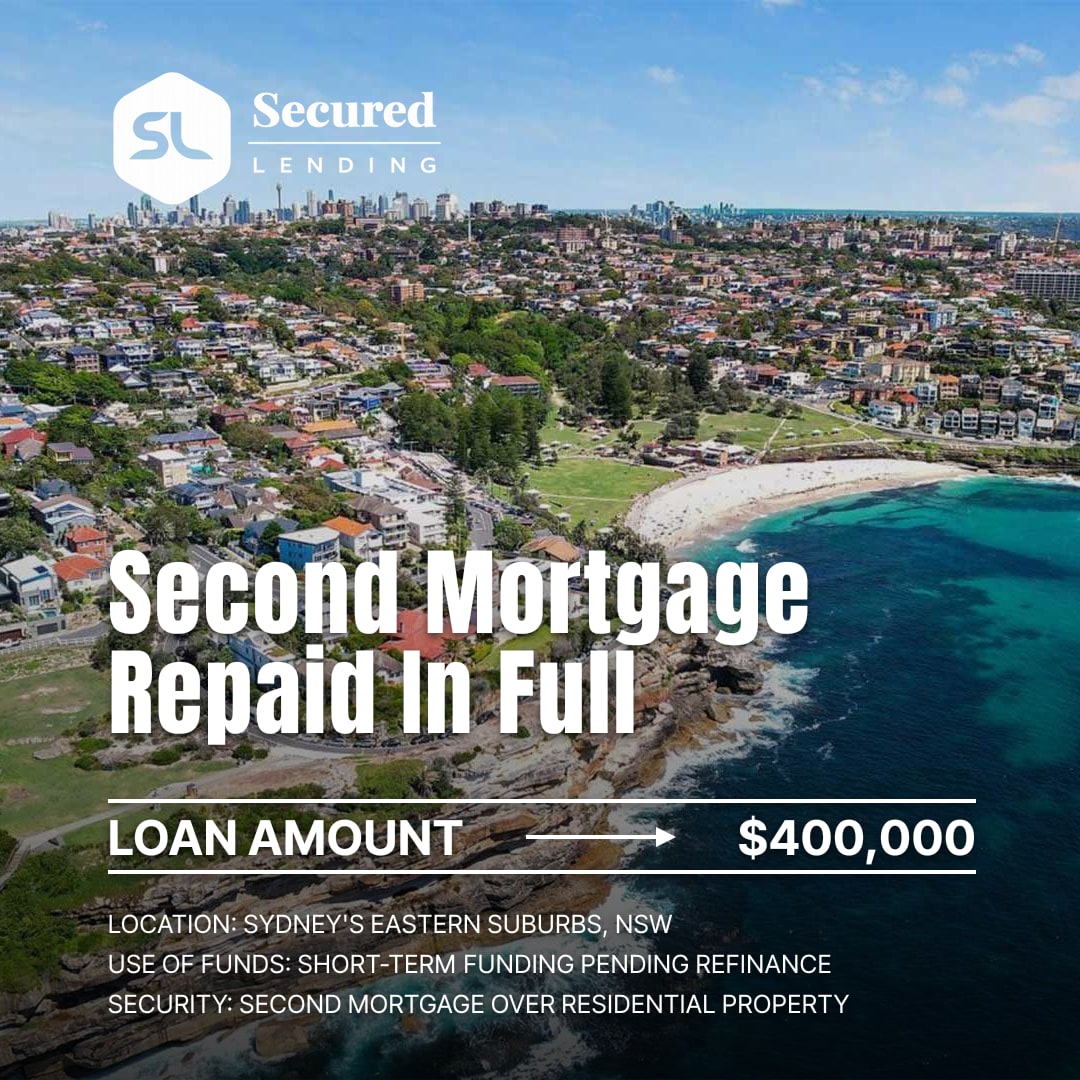
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
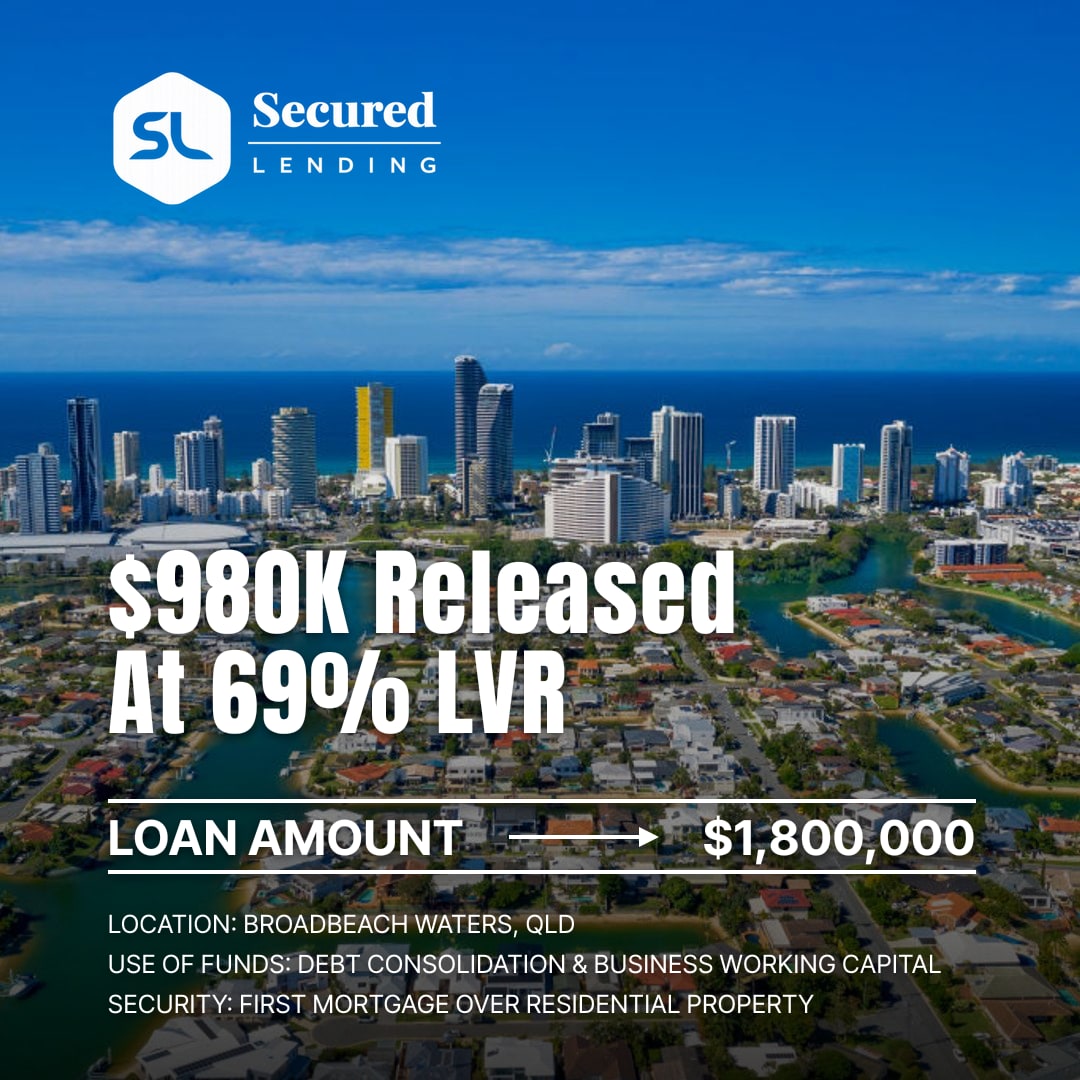
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
$700K Working Capital for a Technology Start-Up Settled in 72 Hours
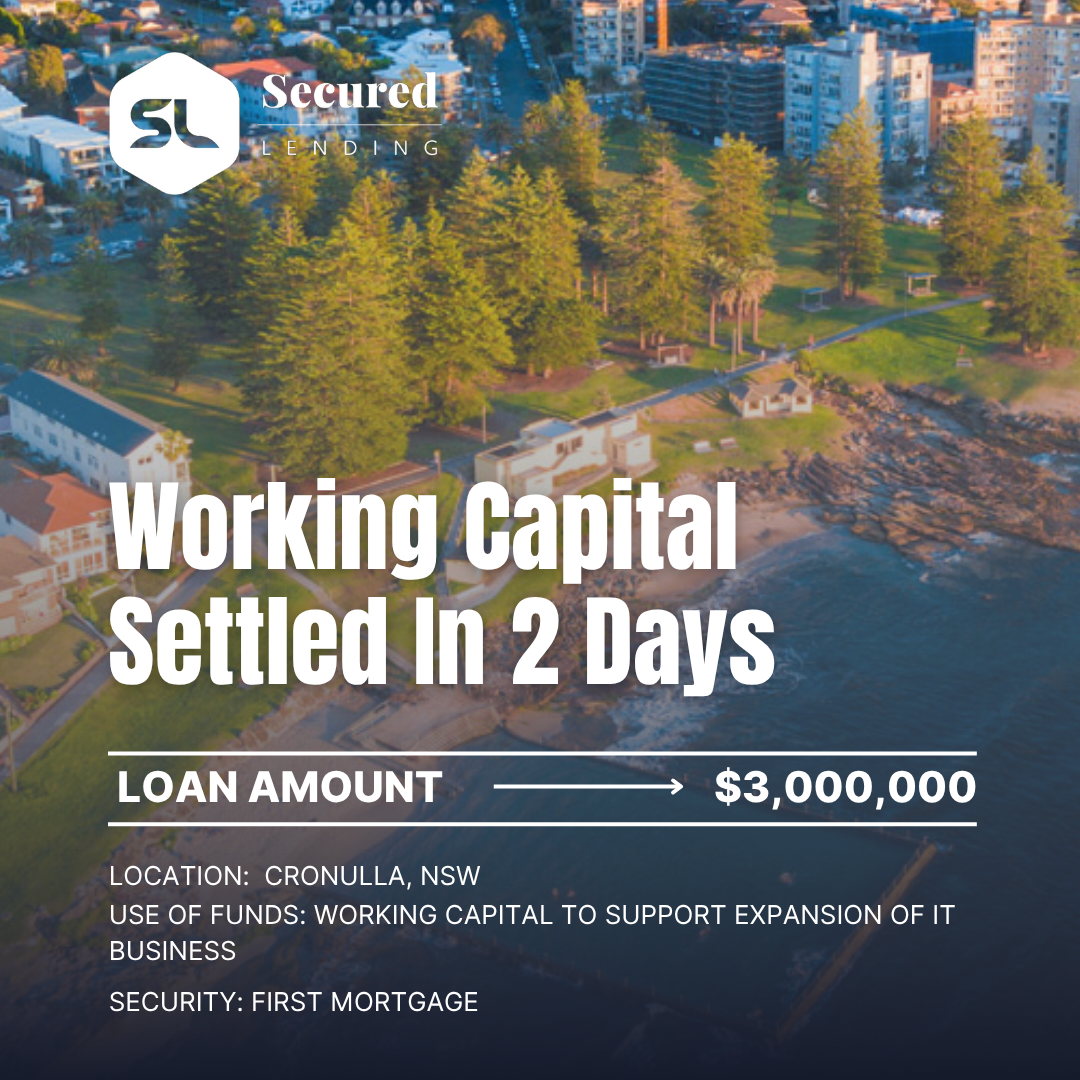
$3M Working Capital for IT Business Expansion Settled in 2 Business Days
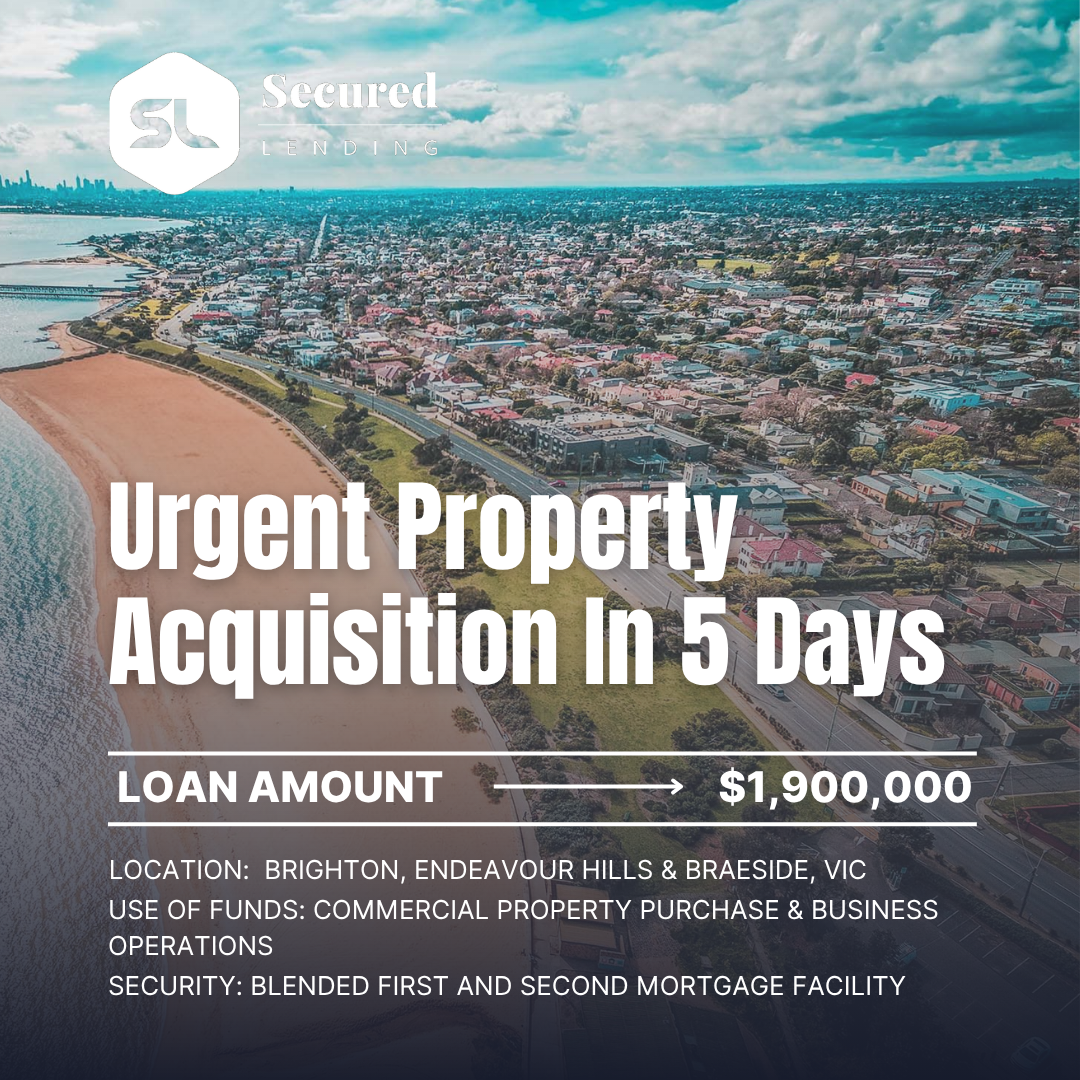
$1.9M Commercial Property Acquisition for Growing Doggy Daycare Business
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Other Urgent Loans We Fund
Each page covers one deadline: what we fund, what to send us and how quickly we can settle.