Director Penalty Notice? Urgent Short Term Finance to Pay Within 21 Days
Pay the company debt within the 21 days, using equity in property you or the company already own
Experts in strategic, short-term finance
A director penalty notice tells you the ATO holds you personally liable for certain unpaid company tax debts, and it gives you 21 days to act. We understand how unsettling that is. Paying the company debt in full is one of the ways the ATO says the penalty can be remitted, and we can fund that payment in as little as 24 hours.
We fund DPN payments for directors of companies across Australia, from $250,000 to $10 million, for 1 to 24 months. We do not give insolvency advice, but we can connect you with insolvency specialists in our network if you are unsure which step is right for your company. A loan adds a new debt, and a payment made while the company is insolvent can be recovered by a liquidator as an unfair preference.
What a director penalty notice covers
The ATO says a director can become personally liable for the company's unpaid PAYG withholding, GST and super guarantee charge.
Late lodgement changes your options
If the company reported the debt within 3 months of its due date, the ATO lists four ways the penalty can be remitted within the 21 days: paying the debt in full, appointing an administrator, appointing a small business restructuring practitioner, or the company beginning to be wound up. If the debt was reported more than 3 months after it was due, or never reported, paying it in full is the only way. The ATO treats its own estimates of PAYG withholding and GST as amounts that were never reported.
Why directors act inside the 21 days
- •After the 21 days, the ATO may take action against the director personally to recover the penalty
- •The ATO says resigning as a director does not remove the liability
- •The ATO can offset the penalty against your personal tax refunds, issue garnishee notices or start legal proceedings
How the loan is used
- •Paying the company's PAYG withholding, GST or super guarantee charge in full
- •Paying the general interest charge and penalties on the company's ATO account
- •Clearing the ATO debts of more than one company you are a director of
- •Adding working capital for the business once the ATO is paid
Inside the 21 days
Day of the call. Tell us the amount on the notice, the date on it and the property you can offer. Terms can be agreed the same day where the scenario allows.
Valuation. Our valuers assess the property, usually within a day or two.
Letter of offer. The letter of offer can be signed as soon as the terms are agreed.
Settlement. The company's ATO payment is made from the settlement funds, within 24 hours of the letter of offer being signed.
What to send with your enquiry
- •The director penalty notice, including its date
- •The company's ATO statement of account
- •When the company lodged the BAS and super reports behind the debt
- •The property you can offer, and any existing loan on it
- •How you plan to repay us
Loans that can pay a DPN
- •ATO tax debt loans: our product built for company tax debts
- •Caveat loans: the fastest option when the 21 days are nearly up
- •Second mortgage: behind your existing home or business loan
- •First mortgage: over a property with no loan on it
- •Bridging loans: where a property sale will repay us
DPN loan terms
| Loan feature | Detail |
|---|---|
| Loan size | $250,000 to $10,000,000 |
| Interest rate | From 9.7% p.a. on a first mortgage, from 11.95% p.a. on a second mortgage |
| Term | 1 to 24 months, interest only |
| Maximum LVR | 70%, including any existing mortgage on the property |
| Security | A first or second mortgage, or a caveat, over residential, commercial or industrial property owned by you or the company |
| Settlement | From 24 hours |
Repaying after the ATO is paid
DPN loans are usually repaid by refinancing to a bank once the ATO account is clear, the sale of a property, or a known payment due to the company. We confirm which plan applies with you before settlement.
Director and ATO debts we have funded
“A DPN gives a director 21 days, and a valuation and loan documents take some of them. Send us the notice and the property details on the day it arrives. Once the company debt is paid in full within the 21 days, the penalty is remitted, and you can get on with running the company.”
Gino Tabila
Associate Director
Frequently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
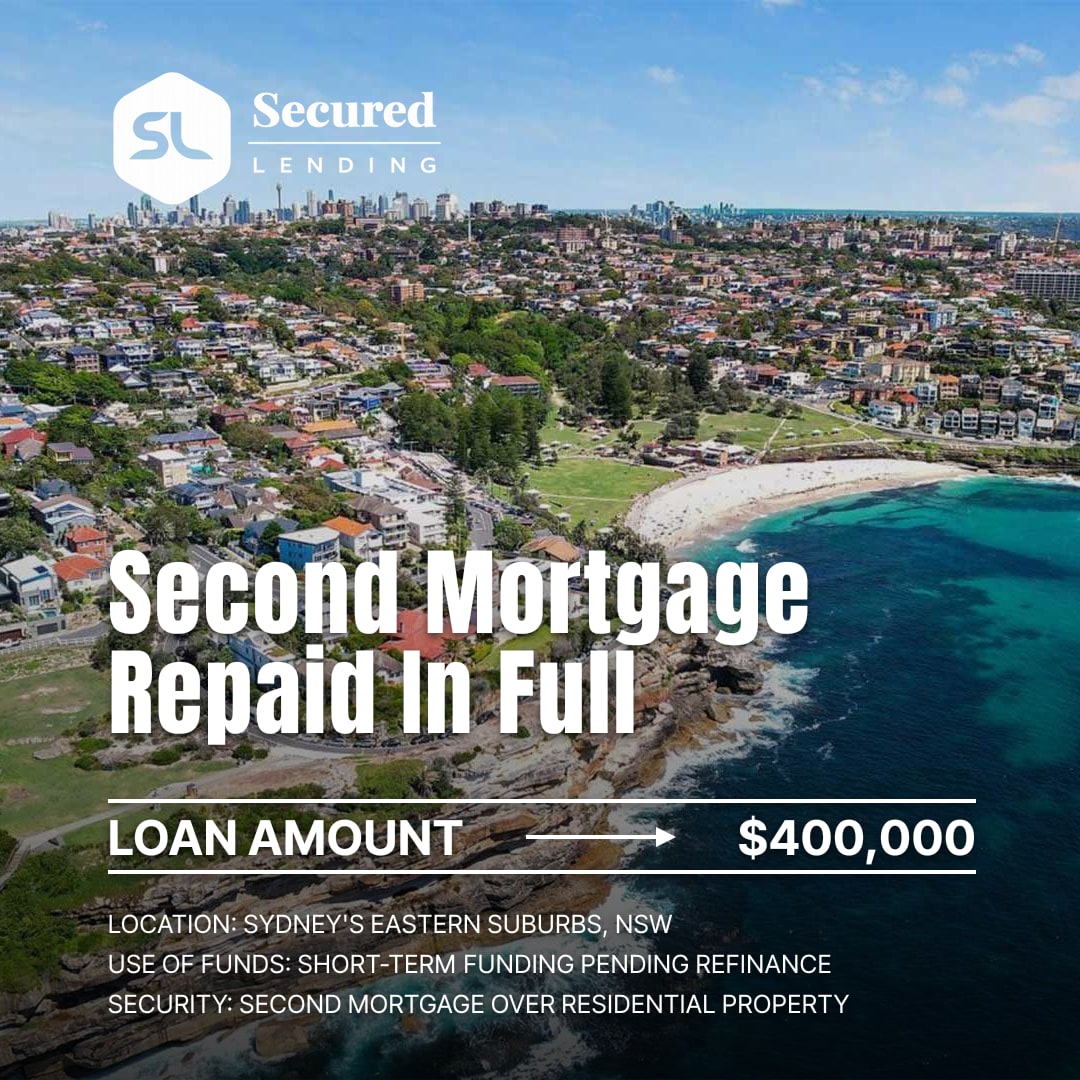
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
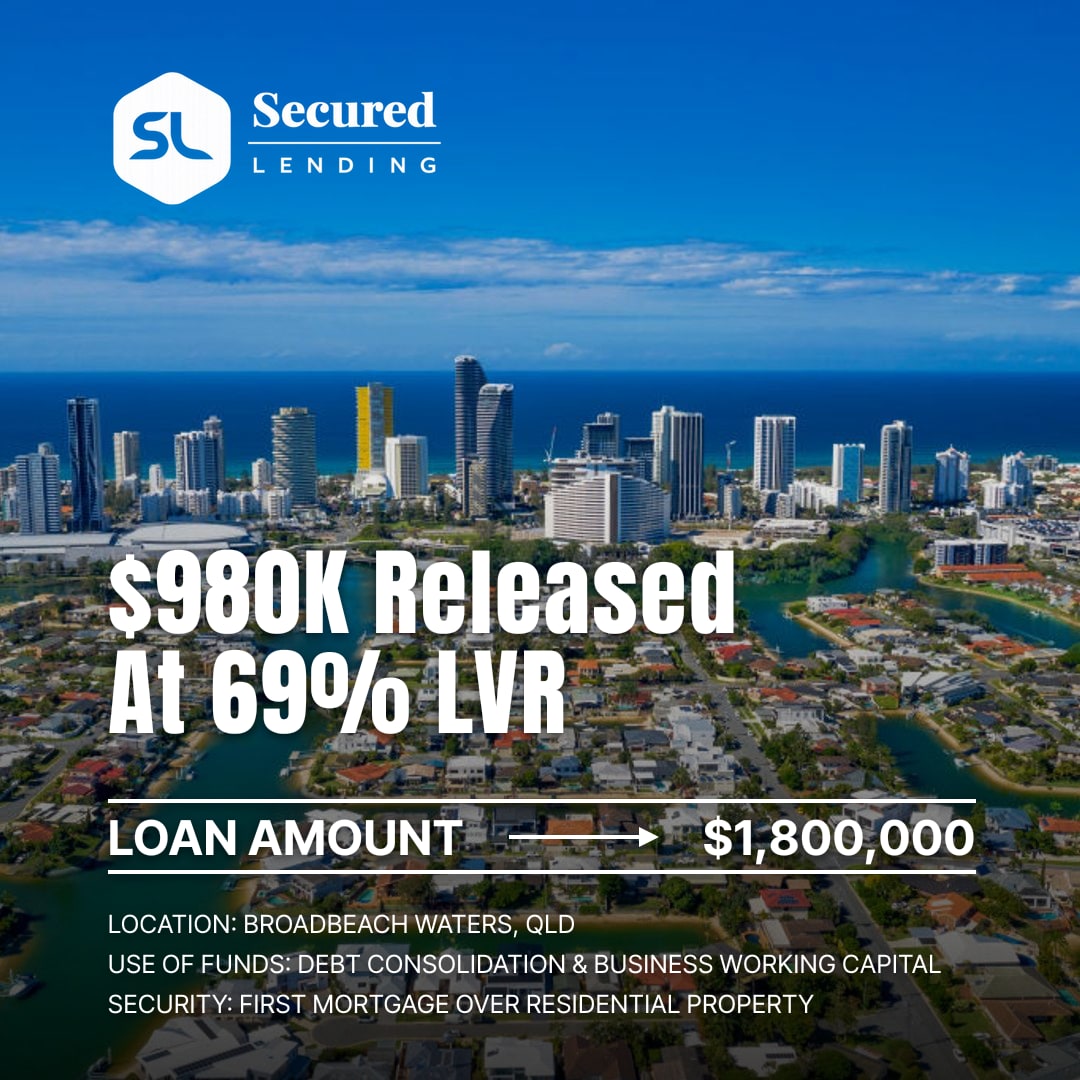
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
$700K Working Capital for a Technology Start-Up Settled in 72 Hours
$3M Working Capital for IT Business Expansion Settled in 2 Business Days
$1.9M Commercial Property Acquisition for Growing Doggy Daycare Business
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Other Urgent Loans We Fund
Each page covers one deadline: what we fund, what to send us and how quickly we can settle.