Urgent $10 Million Business Loan Private Finance

$10 million private funding for businesses in Australia
Expert
Expert
Expert

Experts in strategic, short-term finance
Finance within 24 hours
Loans from $1M
Rates from 9.7% p.a.
1 to 24 month terms
Secured Lending

ExcellentRated 5 out of 5 on Google

Rated 5 out of 5Jason V

Hands down, the best private lenders in the biz

Gino, Alec and Finn are exceptional at what they do. Top tier communication and transparent service.

Rated 5 out of 5Rhowell Dela Rosa

Every settlement has been smooth

Gino and the team at Secured Lending are our go-to when a deal needs to move fast or fall outside bank criteria.

Rated 5 out of 5Rory Mcgrath

Always my top choice for nearly all private lending scenarios

I run and operate a private lending brokerage and have worked with Mark and the team for years.

Rated 5 out of 5Luke Egan

Speed to market on lending advances second to none

The owner is also one of best commentators on LinkedIn calling out poor lending and recovery practices.

Rated 5 out of 5amal maharaj

True professionals in the non bank lending space

Straight forward application and assessment process with clear communication till loan settlement.

Rated 5 out of 5Sam Algeri

Excellent service, quick approvals and seamless settlements

The team at Secured Lending, particularly Gino and Finn, are fantastic to work with.

Rated 5 out of 5sebastian wright

Speed, reliability, transparency

Exceptional team. Exceptional Service. Loved working with the team at Secured Lending.

Rated 5 out of 5Jordan Thomas

Gino & Finn are the best in the business

Quick and painless to deal with, keep up the great work SL team!

Rated 5 out of 5Wayne McCarthy

Always willing to think outside the box to get deals done

We've had a great experience working with Secured Lending.

Rated 5 out of 5JP G

Quick, responsive and reasonable

With all the shady characters in the private lending market, its refreshing to find good people to deal with.

Rated 5 out of 5Joel Togo

Always thorough on assessment and will give you a prompt answer

With clients that are in time sensitive situations, this is crucial.

Rated 5 out of 5David Pruscino

Always professional and supportive

It's a pleasure dealing with the Secured team.

Rated 5 out of 5Monica Monsigneur

A professional and common sense lender who delivers

Rated 5 out of 5Thomas de Fegely

Great options in the private space

Have been dealing with Finn from Secured Lending, he has been very responsive.

Rated 5 out of 5Andrew Soo

A very reliable funding partner

Highly recommended.

Rated 5 out of 5Phil Boyle

Very efficient, responsive

Finn was a great help to assist in a very timely manner.

$10 Million Business Loans with Speed, Certainty, and Commercial Focus

Secured Lending specialises in high-value property-secured financing from $1 million, with larger loans assessed case by case. We are a non-bank alternative offering faster approvals than traditional institutions: no committees, no extended review processes, and deep commercial understanding of deal urgency and settlement timelines.

Key Features of Our $10 Million Facilities

  • •Loan amounts from $1M, larger loans assessed case by case
  • •$10M facilities for acquisitions, refinance, and equity release
  • •Short-term funding options: caveats, bridging, first and second mortgages
  • •Terms from 1 to 24 months
  • •Rates from 9.7% p.a.
  • •Approval and settlement in 24 to 48 hours for urgent deals

Common Use Cases for $10 Million Loans

  • •Acquisition finance for commercial or mixed-use assets
  • •Capital extraction from existing property portfolios
  • •Business restructure and liability management
  • •Bridging major deals awaiting longer-term finance
  • •Distressed debt refinance from other lenders

Why Clients Choose Us for $10 Million Loans

We understand the pressures of large transactions: execution confidence, complex deal structuring, multi-asset security arrangements, and tight timelines. Our team has the capability and experience to fund at scale without the delays of institutional credit processes.

Property Security Requirements

  • •High-value commercial or mixed-use property in metro areas
  • •Residential portfolios with cross-collateral security
  • •Regional assets with strong valuations considered
  • •First or second mortgage positions depending on LVR

Million Dollar Loans We Have Funded

  • Client success #1: $4M, land bank site acquisition after the original lender pulled out, settled in 24 hours, NSW
  • Client success #2: $3M, working capital for an IT business expansion, settled in 2 business days, Cronulla NSW
  • Client success #3: $2.4M, working capital for wages and supplier invoices, settled in 4 business days, Western Sydney NSW
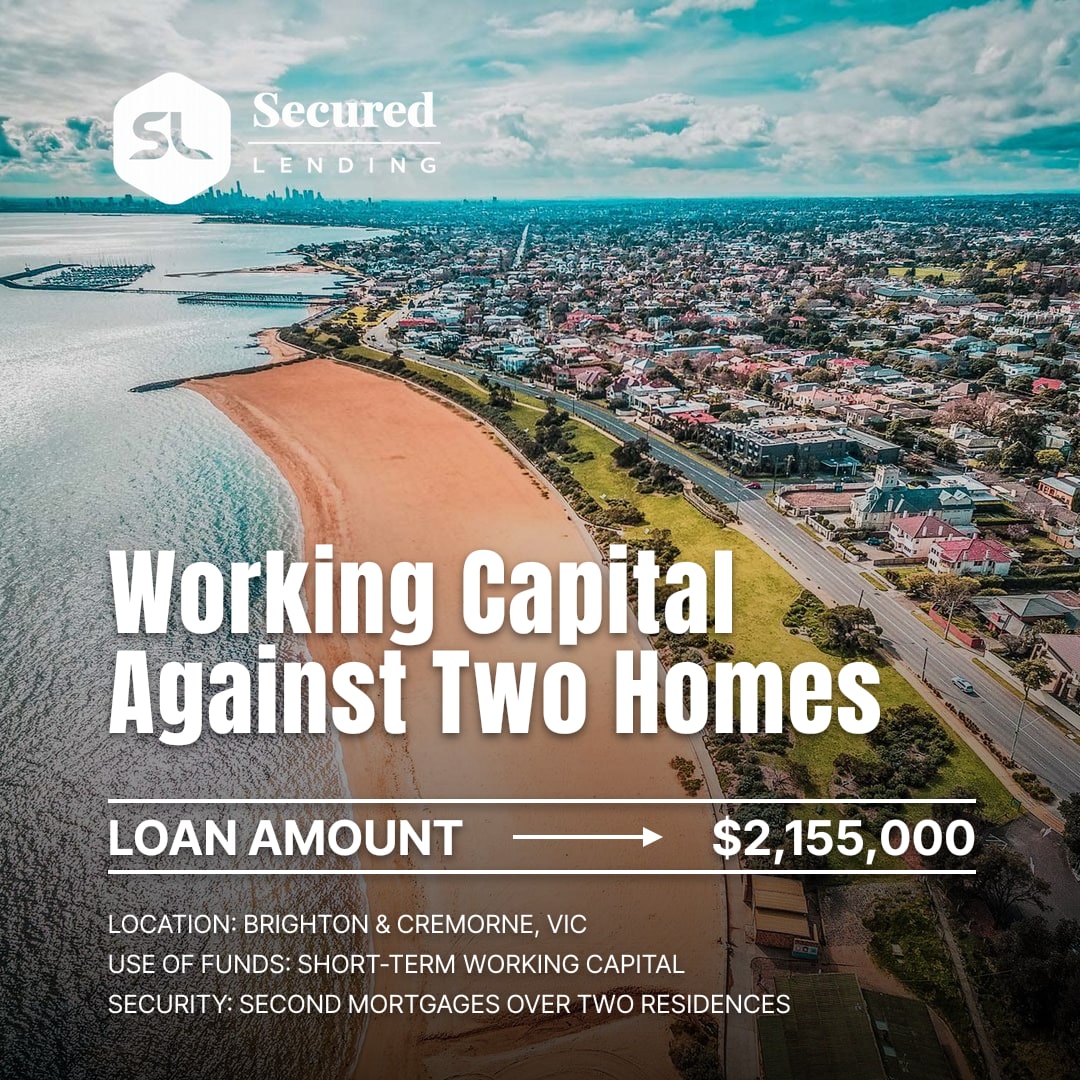
  • Client success #4: $1.9M, commercial property acquisition, settled in 5 business days, Brighton VIC
  • Client success #5: $1.88M, bridging loan to rescue a settlement, settled in 48 hours, Gymea Bay NSW
  • Client success #6: $1.2M, second mortgage equity release for a time-critical commercial deal, settled in 24 hours, Inner Sydney NSW
  • Client success #7: $1.15M, ATO tax debt cleared for a pub operator, settled in 4 business days, Prahran VIC
  • Client success #8: $1.1M, developer cash injection after bank progress payments stalled, settled in 72 hours, Granville NSW

$10 Million Facilities and Bad Credit History

A facility at this level is written against a property portfolio and a defined exit, not a credit score. Borrowers reaching us at $10 million are often mid-transaction with a lender that changed its appetite, and the file shows the strain. We assess the combined position inside 70% LVR, value the security with our own team, and decide in-house.

"At $10 million we are typically working with a cross-collateralised structure across multiple properties, often a mix of first and second mortgage positions depending on the existing debt on each asset. We model the blended LVR across the full security pool, stress-test the exit against realistic timelines, and structure the facility to sit comfortably inside 70% on a portfolio basis. That level of structuring is where genuine credit capability shows, and it is the kind of deal we really enjoy getting right with our clients."
Gino Tabila

Gino Tabila

Associate Director

Recently Asked Questions

No. $10,000,000 is not a maximum, and we can lend more than $10,000,000, including the full $11,000,000. On a loan this size we need to understand the scenario fully: the property that secures it, its value, any other mortgages on it and how the loan will be repaid. Our 70% limit applies across all mortgages, so if part of the money comes from another lender with a mortgage over the same property, its loan counts toward that limit. For $11,000,000 of combined debt, the property needs to be worth about $15.71 million.

Not the full $10 million. Seventy percent of $16,000,000 is $11,200,000, and after the bank's $3,000,000, about $8,200,000 could be raised as a second mortgage, with rates from 11.95% p.a. Repaying the bank and taking one first mortgage does not raise more, because total debt still has to sit inside $11,200,000. To reach $10,000,000 of new money, the group would need more property in the security.

We take the freehold property as security. A going-concern valuation is the standard way to value a trading hotel, but the security is still the freehold. Seventy percent of $15,000,000 is $10,500,000, so a $10,000,000 loan fits if there is no other debt on the hotel. The hotel licence and the business are not security. We will ask for the trading figures the valuer relies on, and the plan to repay the loan.

It can. Because the bank has not approved the refinance yet, we will assess the exit on more than the bank alone, so tell us what the second option is, such as the sale of a property. Our terms run from 1 to 24 months, which leaves room if the bank takes longer. Send us the current lender's payout figure, the bank's correspondence and the property details today. For $10,000,000, the security needs to be worth about $14.29 million after any other debt.

Yes. Property held in a company can be security, and further properties can be added as additional security. One company in the group is the borrower, and each company that owns a building signs a mortgage over its own property. The 70% limit is tested across all the buildings together, so they need to be worth about $14.29 million after existing debt. Have your solicitor confirm each company's authority to give the mortgage before we prepare documents.

Not quite. Seventy percent of $14,000,000 is $9,800,000, so the building alone supports up to $9,800,000, and your cash also has to cover stamp duty and the other purchase costs. To borrow the full $10,000,000, add a second property as additional security. Send us the contract, your cash position and any other property you own, and we will tell you the structure that settles on time.

Our in-house valuation team values the property. That team assesses commercial, industrial and residential property directly, which is why we do not wait on an outside valuer's booking. Send us the bank's report as well. It gives our valuers more information, and if their figure differs from the bank's, we can explain why.

It can, where the evidence supports the price. We will look at the agent's appraisal, the inquiries so far and recent sales of similar centres, and decide whether the sale can be completed within the loan term. Our terms run up to 24 months, so a longer term can allow for a slow sale. If the price may need to come down, tell us what the lowest acceptable price is, because the loan has to be repaid from that figure.

It can, where the property and the exit fit inside our limits. We assess the security, the 70% limit and the plan to repay us, and the review does not stop us assessing those. Tell the bank you are arranging a refinance and ask for a payout figure. Send us the property details and the bank's correspondence, and we will tell you within hours whether we can proceed.

Yes. A $9,000,000 loan is inside our range, and under our 70% limit the properties need to be worth about $12.86 million after any existing debt. The company that owes the debt is the borrower, receives the loan funds and pays the ATO itself. Ask your accountant whether to lodge an objection to the assessment as well, and send us the assessment, the property list and the plan to repay the loan.

For urgent deals with clean security and a defined exit, approval and settlement within 48 hours is possible. We assess based on security strength and exit viability, not lengthy approval committees.

High-value commercial, mixed-use residential, industrial portfolios, and multi-asset cross-collateralised securities are all accepted. We also consider regional assets with strong valuations.

Yes, subject to the combined LVR across first and second mortgage positions being within acceptable limits for the security type.

The maximum is 70% LVR, the same ceiling that applies at every loan size. Larger facilities are assessed on the strength of the security and the exit, not on a different LVR band.

Yes. We work extensively with finance brokers for large transactions. Submit a deal summary and we will respond with an indicative position quickly.

Acquisitions, capital extraction, business restructuring, major deal bridging, and distressed debt refinance are the most common purposes at this loan level.

No. What sets the timeline at $10 million is the number of titles, whether company or trust borrowers need resolutions, and how quickly payout figures come back from outgoing lenders. Straightforward files settle within 24 to 72 hours. A credit report is read once, early, and never sits in the settlement path.

Expert
Expert
Expert
$500M+ funded

Get an indicative offer within hours, not weeks.

No credit check. No obligation.

Why Secured Lending?

✓Australian private lender, $500M+ funded
✓We use our own funds for fast decisions
✓24-hour settlements, loans from $250k
✓Rates from 9.7% p.a. | Terms 1–24 months

Are you a broker? Find out why brokers love working with us.

The team

Who you will be dealing with

On a facility of this size you deal directly with the people who make the credit decision. There is no call centre, and no committee sitting between you and an answer.

Mark Hutchins

Mark Hutchins

Mark is the Managing Director of Secured Lending and is responsible for the group’s strategies, operations and growth of the loan portfolio.

Gino Tabila

Gino Tabila

Gino has over 15 years’ experience in corporate accountancy, financing and turnaround work. He has worked in alternative lending for the past 5 years, with considerable experience in finding short-term finance solutions for clients and a depth of knowledge as to the speed and requirements involved.

Daniel Juratowitch

Daniel Juratowitch

Daniel brings a wealth of distressed-asset experience, having been a registered liquidator and trustee in bankruptcy for over 20 years. He is also a Chartered Accountant and CEO of Cor Cordis, a leading insolvency firm in Australia. Daniel brings firsthand experience with enforcement for lenders and understands intricately the relationship between an asset’s market value and its worth under distressed situations.

Success Stories

Case Studies

View all case studies