Property-secured finance across the Eastern Suburbs, assessed in-house and funded within 24 hours
Experts in strategic, short-term finance
24hrsFast funding solutions
$250K-$10MLoan range
9.7% p.aInterest rates starting from
1-24 monthsShort term funding
Rated 5 out of 5Jason V
Hands down, the best private lenders in the biz
Gino, Alec and Finn are exceptional at what they do. Top tier communication and transparent service.
Rated 5 out of 5Rhowell Dela Rosa
Every settlement has been smooth
Gino and the team at Secured Lending are our go-to when a deal needs to move fast or fall outside bank criteria.
Rated 5 out of 5Rory Mcgrath
Always my top choice for nearly all private lending scenarios
I run and operate a private lending brokerage and have worked with Mark and the team for years.
Rated 5 out of 5Luke Egan
Speed to market on lending advances second to none
The owner is also one of best commentators on LinkedIn calling out poor lending and recovery practices.
Rated 5 out of 5amal maharaj
True professionals in the non bank lending space
Straight forward application and assessment process with clear communication till loan settlement.
Rated 5 out of 5Sam Algeri
Excellent service, quick approvals and seamless settlements
The team at Secured Lending, particularly Gino and Finn, are fantastic to work with.
Rated 5 out of 5sebastian wright
Speed, reliability, transparency
Exceptional team. Exceptional Service. Loved working with the team at Secured Lending.
Rated 5 out of 5Jordan Thomas
Gino & Finn are the best in the business
Quick and painless to deal with, keep up the great work SL team!
Rated 5 out of 5Wayne McCarthy
Always willing to think outside the box to get deals done
We've had a great experience working with Secured Lending.
Rated 5 out of 5JP G
Quick, responsive and reasonable
With all the shady characters in the private lending market, its refreshing to find good people to deal with.
Rated 5 out of 5Joel Togo
Always thorough on assessment and will give you a prompt answer
With clients that are in time sensitive situations, this is crucial.
Rated 5 out of 5David Pruscino
Always professional and supportive
It's a pleasure dealing with the Secured team.
Rated 5 out of 5Monica Monsigneur
A professional and common sense lender who delivers
Rated 5 out of 5Thomas de Fegely
Great options in the private space
Have been dealing with Finn from Secured Lending, he has been very responsive.
Rated 5 out of 5Andrew Soo
A very reliable funding partner
Highly recommended.
Rated 5 out of 5Phil Boyle
Very efficient, responsive
Finn was a great help to assist in a very timely manner.
Secured Lending is a private, non-bank lender based in Barangaroo that funds its own loans. We provide property-secured finance from $250,000 for businesses, investors, and developers across the Eastern Suburbs, often settled within 24 hours. When a bank has said no or cannot move quickly enough, we assess the deal on the value of your security and a clear plan to repay, not a serviceability score. Much of the wealth here sits in premium homes, and putting that equity to work quietly is what a good share of our local borrowers come to us for.
Our Private Lending Products
•First and second mortgages
•Bridging finance between property settlements
•Caveat loans for fast, short-term funding
•Business-purpose and cash-out loans
•Refinance of expensive short-term debt
•ATO and creditor payout finance
Why Use a Private Lender in the Eastern Suburbs
Banks assess income and serviceability, run every file past a credit committee, and often decline good borrowers whose income is lumpy or held through a company or trust. We work the other way. Across the Eastern Suburbs, where many investors hold premium property through trusts and self-managed super funds, we look at the property offered as security and how the loan will be repaid, which lets us commit quickly and fund when it matters.
•Approvals in hours and funding within 24 hours on a clean file
•Assessed on the value of your security and your exit, not a serviceability test
•Complex, self-employed, and non-conforming income welcome
•Company, trust, and SMSF borrowers are no obstacle
•Short-term, interest-only funding available
•Business-purpose and cash-out loans welcome
Who We Help
•Property owners and investors
•Developers and commercial property owners
•Mortgage brokers and finance advisers
•Lawyers and accountants referring clients
•Business owners who need urgent capital
We lend for business purposes only, to companies, not to individuals, and never for personal home loans or consumer credit.
Our Rates, Terms and Lending Criteria
•Loan size: from $250,000, with larger loans assessed case by case
•Term: 1 to 24 months, typically 3 to 6
•Rates: from 9.7% p.a., with every cost set out in the letter of offer
•LVR: up to 70%
•Security: a registered first or second mortgage over property
•Exit strategy: required on every loan, by sale, refinance, or incoming funds
The exit is the single most important factor we assess. A loan is only as sound as the plan to repay it, so we map that first and build the rest of the decision around it. Property held in companies, trusts, or SMSFs is fine, and we take residential, commercial, industrial, and development security.
Private Mortgage Lender in the Eastern Suburbs
As a private mortgage lender, we write registered first and second mortgages over property and fund every loan from our own capital, so there is no bank behind us dictating the terms. We are a non-bank lender, and we lend from $250,000 strictly for business purposes. On a clean file, that funding can reach your account within 24 hours.
A private mortgage lender works differently to a bank. We assess the property offered and your exit rather than a serviceability score, we can commit in hours instead of weeks, and we build loans short-term and interest-only so they fit a bridge or a quick acquisition. That flexibility matters most to the SMSF and trust investors who hold so much of the property here, and to borrowers a bank has already declined. Across the Eastern Suburbs, those are the people who call us most.
Bad Credit Business Loans in the Eastern Suburbs
A discharged bankruptcy or an old default sits on a credit file for years after it stops meaning anything commercially, and it will close a bank application on sight. In the Eastern Suburbs it usually sits alongside substantial property equity. We lend against the equity in that property, to 70% LVR, and assess the exit rather than the history.
“A great deal of the wealth here is already sitting in the family home, doing nothing in particular. Releasing some of it quietly to fund the next purchase is the most common reason people in the Eastern Suburbs call us, and premium, easily sold security gives us room to be flexible on LVR. Most of these deals sit in a company, a trust, or an SMSF, which is the structure we are built for rather than an exception we tolerate.”
We fund clients right across the Eastern Suburbs, from the premium homes of Double Bay and Vaucluse to the shops and offices around Bondi Junction, Randwick, and Woollahra. Wherever your business trades or your security sits, we can move quickly.
Recently Asked Questions
Yes. Your company is the borrower, and your house in Rose Bay is the property that secures the loan, within 70% of its value. Our loan repays the bank at settlement, and the bank is then asked to release both its mortgage over your house and its security over the company.
Ask the bank for a written payout figure and a list of every security it holds, and have your solicitor check that list before settlement. Send us the payout figure and your plan for repaying us, such as a sale or a bank refinance after a better trading year.
By a plan that does not depend on the business earning in the next few months. That is usually a refinance to a bank once the business is established, or the sale of a property, and we set the term to match it.
In Maroubra we lent $700,000 on a first mortgage to fund a new technology business with no trading history, settled in 72 hours, with a bank refinance as the repayment plan. The apartment needs to be worth at least about $857,000, after any existing mortgage, to support $600,000 within our 70% limit.
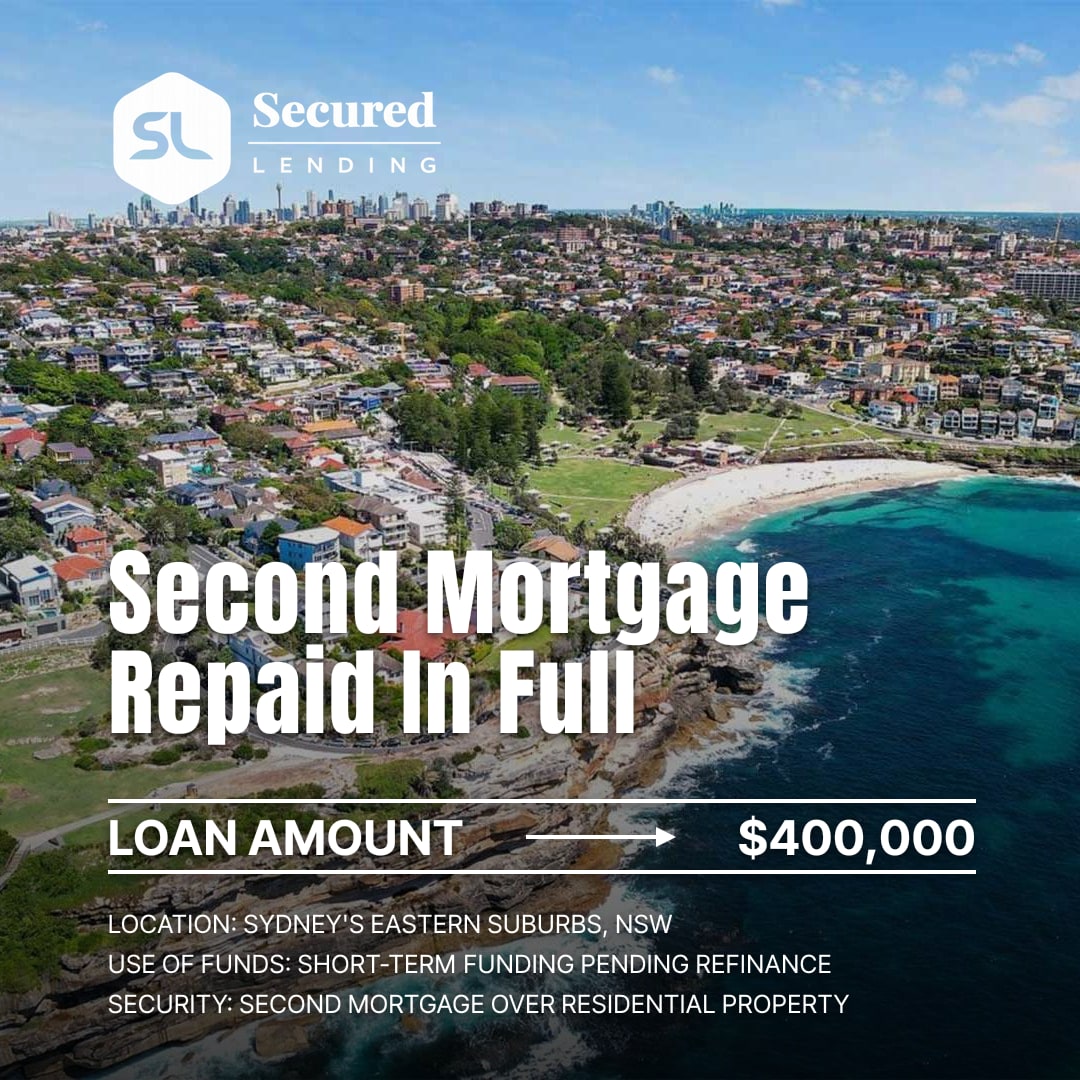
Tell your lender now, before the term ends. On one of our Eastern Suburbs loans, a $400,000 second mortgage, the incoming lender's refinance was delayed through no fault of the borrower, and we extended the term so the refinance could finish. The loan was then repaid in full.
Any extension is agreed case by case. Send the incoming lender's name and its expected settlement date, so the new date is based on facts.
Yes, as part of a larger loan. Our minimum loan is $250,000, so the $180,000 tax debt alone is below it, but one loan can cover the tax debt and the working capital the business also needs. For a café in Paddington with a $180,000 tax debt we lent $450,000 against its commercial property, valued at $1.2 million, which cleared the ATO debt and gave it working capital.
The loan funds are paid to the business, which pays the ATO. Before it borrows, ask your accountant whether the business can pay its debts, because a payment made while it is insolvent can be recovered by a liquidator.
Yes. A block of units on one title is one residential property, so it can secure one loan. To borrow $1.5 million, the block needs to be worth at least about $2.15 million after any mortgage already on it, because all loans must stay within 70% of its value.
Tell us what is owed on the block and the price and settlement date of the property you are buying, and we can confirm the amount.
No. $10 million is not our maximum, and we can lend more. 70% of $18 million is $12.6 million, so a $12 million loan to the company, secured by your home, sits inside our 70% limit.
On a loan this size we need to understand the scenario fully, so send us the acquisition details, the home's address and how the loan will be repaid.
Yes. A short loan secured by property you own can pay the supplier now, and the refinance repays us when it settles. We set the term to the date the new bank expects to settle.
Send us the name of the incoming lender, how far its approval has gone, and the address of the property offered as security. The loan funds are paid to the business, which pays the supplier.
No. 70% of $700,000 is $490,000, and with $300,000 owing to the bank, that leaves room for about $190,000, below our $250,000 minimum.
If you own a second property, or a business partner owns one, adding it as security can lift the total above $250,000. Tell us what else is available and we can do the arithmetic with you.
Either works. A first mortgage starts from 9.7% p.a., and our loan repays the $200,000 bank loan as part of the amount you borrow. A second mortgage starts from 11.95% p.a. and leaves the bank loan in place.
The choice usually turns on whether you want to keep the bank loan, for example for its rate or its term. Both options are limited to 70% of the house's value across all loans.
Yes, where the trustee is a company. The company borrows as trustee of the existing trust to buy a commercial property for the trust's business, and the house the trust already owns can secure the loan. On a house worth $3 million with no mortgage, the trustee company could borrow up to $2.1 million against it.
Tell us the trust's name and its trustee when you send the purchase contract. Your accountant or solicitor should confirm that the trust deed allows the borrowing.
No. Our loans are for business purposes, not for personal or home loans, so a renovation of the home you live in cannot be funded by our loan. The business part can be, secured by the same home.
For the renovation, speak to a bank or a mortgage broker. Tell us the business amount and what it is for, and we can work out what the home supports within our 70% limit.
Yes. Payroll in the Eastern Suburbs can be tight in the week super falls due, and missing the 7 business day window turns unpaid super into a Superannuation Guarantee Charge owed to the ATO. We provide fast, property-secured payday super finance so the payment lands on time.
Rates start from 9.7% p.a. and are priced to the term, the security, and the risk of the individual deal. Every cost, including any establishment fee, is set out in the letter of offer before you commit, with nothing hidden.
Often, yes. A good share of our Eastern Suburbs borrowers come to us after a bank has gone quiet or said no, usually because their income is lumpy, self-employed, or held through a company or trust. We assess the property you can offer as security and your plan to repay, not a serviceability score, and on a clean file we can fund within 24 hours.
Yes. Many Eastern Suburbs investors hold premium property through companies, trusts, and self-managed super funds, and that is no obstacle for us. We assess the asset offered and the repayment plan rather than the structure around it, and we work through the detail with your accountant or solicitor so the security and the borrowing entity line up cleanly.
We lend up to 70% of value on most residential and commercial security. On premium, easily sold homes across the Eastern Suburbs the figure is decided case by case within that ceiling. Loans start from $250,000, and our own valuers set the figure against current local sales rather than an outsourced desktop estimate.
Yes. Releasing equity from a home or investment property to fund the next purchase is one of the most common reasons people here call us. If you hold an Eastern Suburbs property with room beneath any existing loan, we can lend against that equity to bridge a settlement or move on an acquisition, provided the purpose is business and there is a clear exit.
No. We lend for business purposes only, to companies, not to individuals, and never for personal home loans or consumer credit. The loan must be for a genuine business purpose and secured by property.
Yes. We are a private mortgage lender and take a registered first or second mortgage over Eastern Suburbs property, lending only for business purposes. Loans start from $250,000, and on a clean file we can fund within 24 hours.
Yes. The Eastern Suburbs is one part of our Sydney book. Our main Sydney guide covers the wider metro area, our Private Lender Australia overview sets out our national reach, and our North Sydney guide covers the harbour north side.
Yes, for a business purpose. We need to see the discharge, understand what the funds are for, and be satisfied the exit is real. The Eastern Suburbs property still has to carry the loan inside 70% LVR. An undischarged bankruptcy is a different matter, and we cannot lend into one.
Yes, for business purposes. A high-value property can take longer to value, so send the contract early.