Urgent Short Term Finance for Aged Care and Retirement Village Property
Settle or refinance the property on time, then move to a long-term sector lender
Experts in strategic, short-term finance
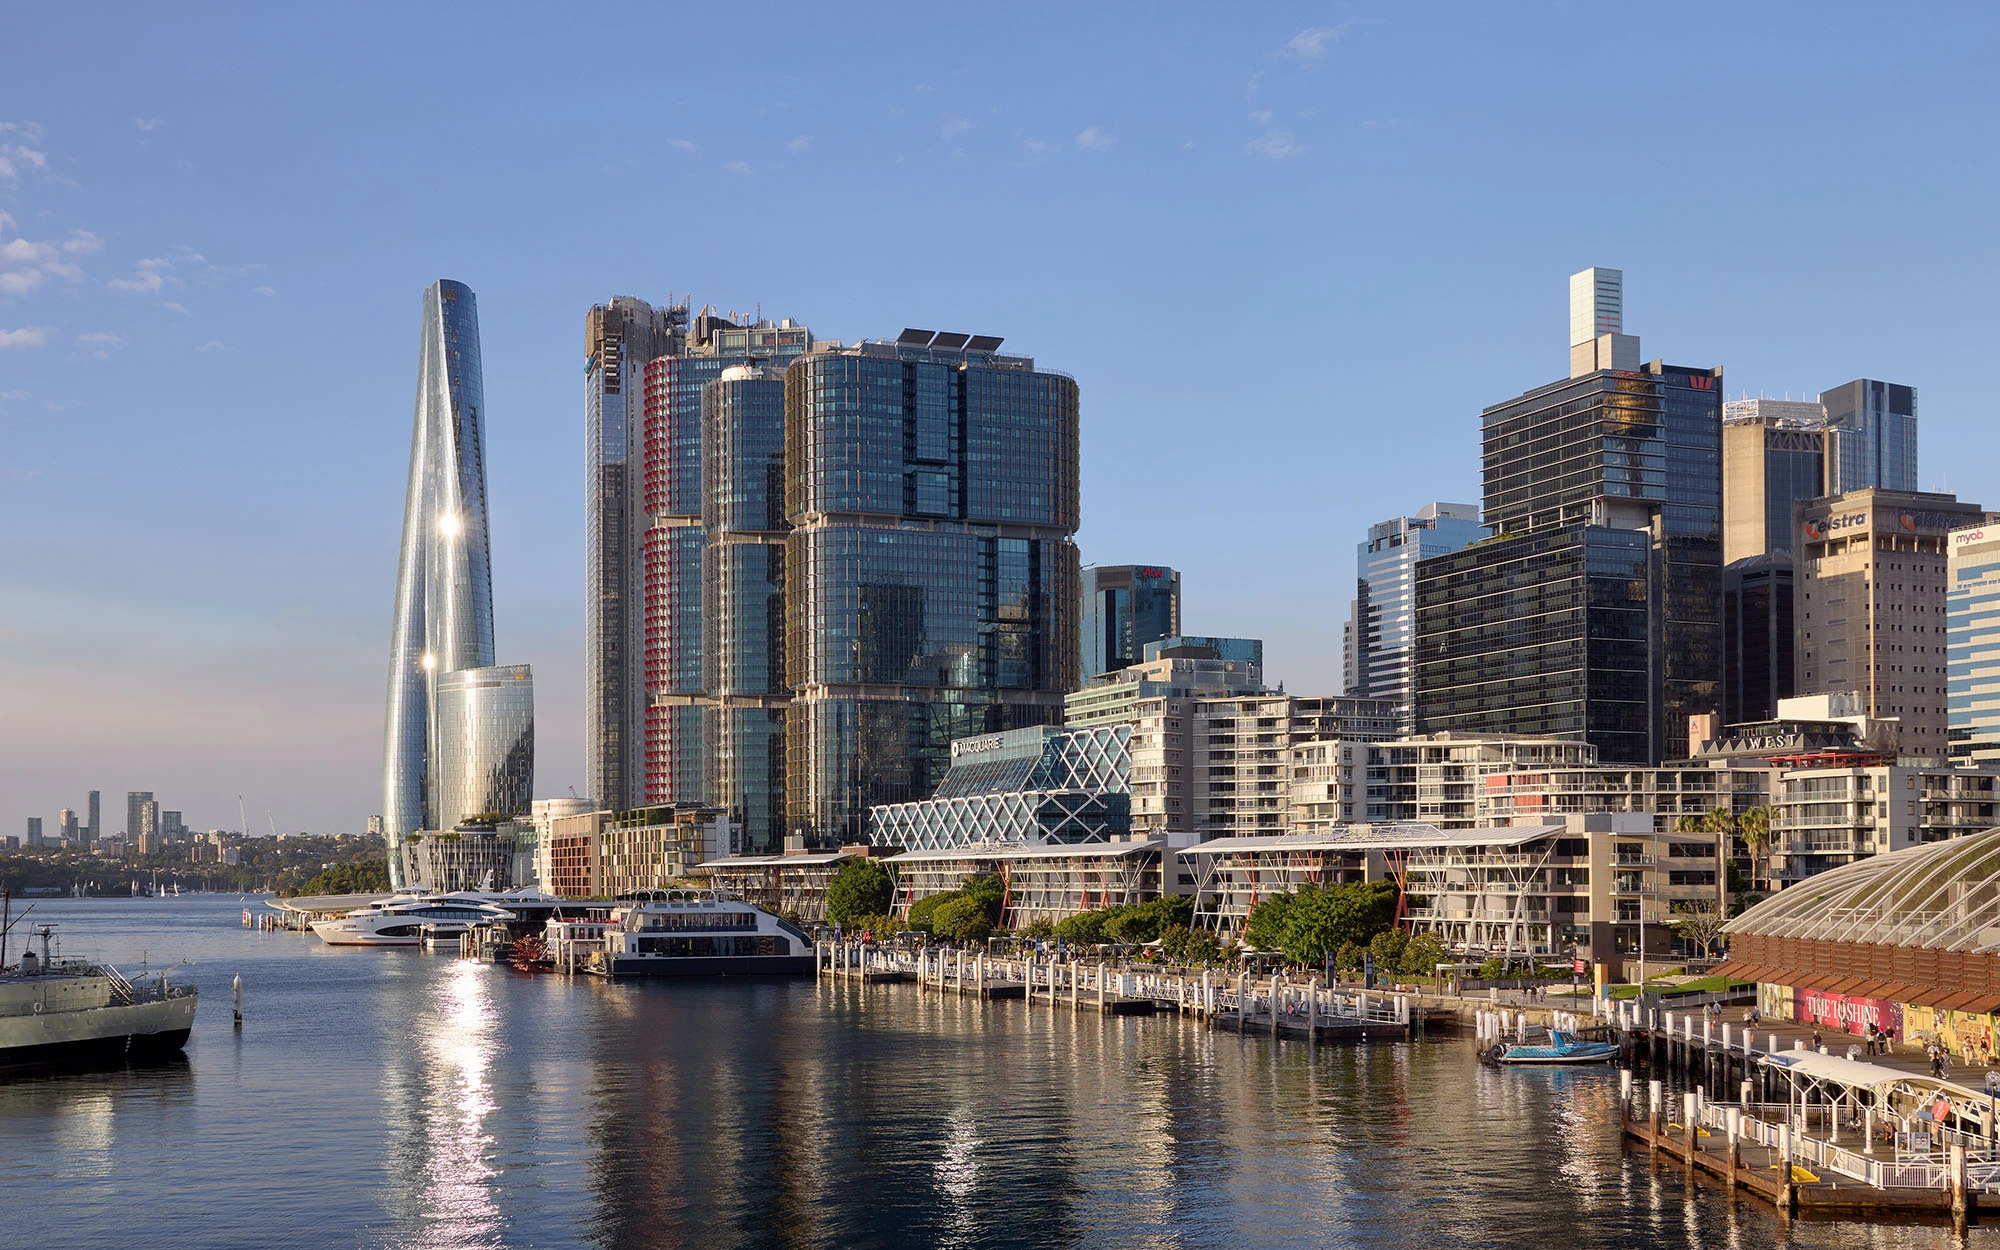
Aged care and retirement village property sits in a specialised part of the market, and bank approvals can take longer than a settlement date allows. When an operator needs to settle an acquisition or refinance a facility on a fixed date, we can fund it in as little as 24 hours.
We lend to operators and owners on the freehold property of aged care facilities and retirement villages across Australia. Our loans are made to the operator, and they do not change residents' rights.
The rules that shape these loans
- •The Aged Care Act 2024 started on 1 November 2025, and providers must be registered to receive government funding
- •Residential aged care places allocated under the former system ceased to exist on 1 November 2025
- •A refundable accommodation deposit must be refunded within 14 days after the resident leaves, or within 14 days after notice where up to 14 days' notice is given
- •The permitted uses of refundable deposits include repaying debt related to buying or building aged care premises
- •In Queensland, the residents' statutory charge over retirement village land ranks ahead of registered mortgages
Because a residents' charge ranks ahead of a mortgage in Queensland, it reduces the amount we can lend on a village there. Rules differ between states, so your lawyer should confirm how they apply to your property.
When operators call us
- •An acquisition of a facility or village has a fixed settlement date
- •The current lender is leaving the sector, or will not renew
- •Refurbishment is needed to meet standards, funded as a lump sum at settlement
- •A deposit is due on land for a new facility
- •Seller finance on a past acquisition is falling due
Funding aged care and retirement property
Enquiry. Send the contract or current loan details and a summary of the operator's registration. Indicative terms come back within hours.
Valuation. Our valuers assess the property on a going-concern basis, taking account of any residents' charges.
Due diligence. We review the operator's registration and any statutory interests on the title with your solicitor.
Settlement. Settlement is possible within 24 hours once the letter of offer is signed.
What our credit team needs
- •The contract of sale or current loan statement
- •The operator's registration details
- •Occupancy and financial figures for the facility
- •Details of residents' charges or other statutory interests on the title
- •Your repayment plan
Loan options for operators
- •First mortgage: over the freehold, valued on a going-concern basis
- •Second mortgage: over other property, where residents' charges reduce the loan on the site
- •Bridging loans: where a sector lender is expected to refinance
- •Secured business loans: a lump sum for refurbishment at settlement
Terms for aged care and village property
| Loan feature | Detail |
|---|---|
| Loan size | $250,000 to $10,000,000 |
| Interest rate | From 9.7% p.a. on a first mortgage, from 11.95% p.a. on a second mortgage |
| Term | 1 to 24 months, interest only |
| Maximum LVR | 70% of the property value after any residents' charges, or of the lower of value and price on a purchase |
| Security | A first or second mortgage over the freehold property, valued on a going-concern basis. Never provider registration, refundable deposits or other residents' funds |
| Settlement | From 24 hours |
Refinancing with a sector lender
Our loan is usually repaid by a bank or specialist aged care lender once an acquisition has settled or a refurbishment is complete. Where refundable deposits are used to repay acquisition or building debt, the permitted-use rules must be followed. Some operators repay from the sale of another property.
“Aged care and retirement property is specialised, and banks take their time with it. We lend to the operator, with any residents' charges taken into account, so an acquisition or refinance can settle on time, and residents' rights are not changed by our loan. Send us the contract and the facility's figures, and we will tell you what we can lend.”
Gino Tabila
Associate Director
Frequently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
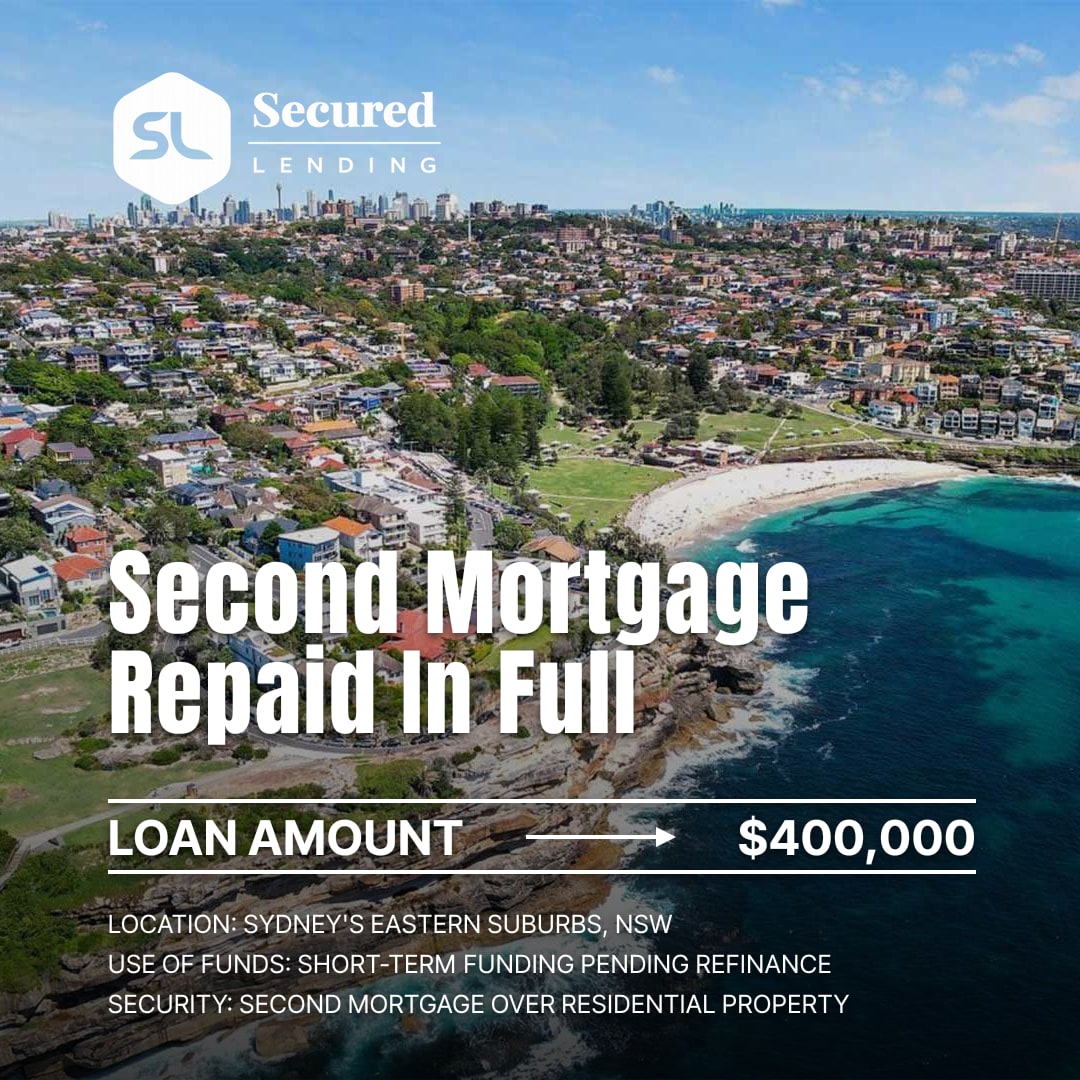
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
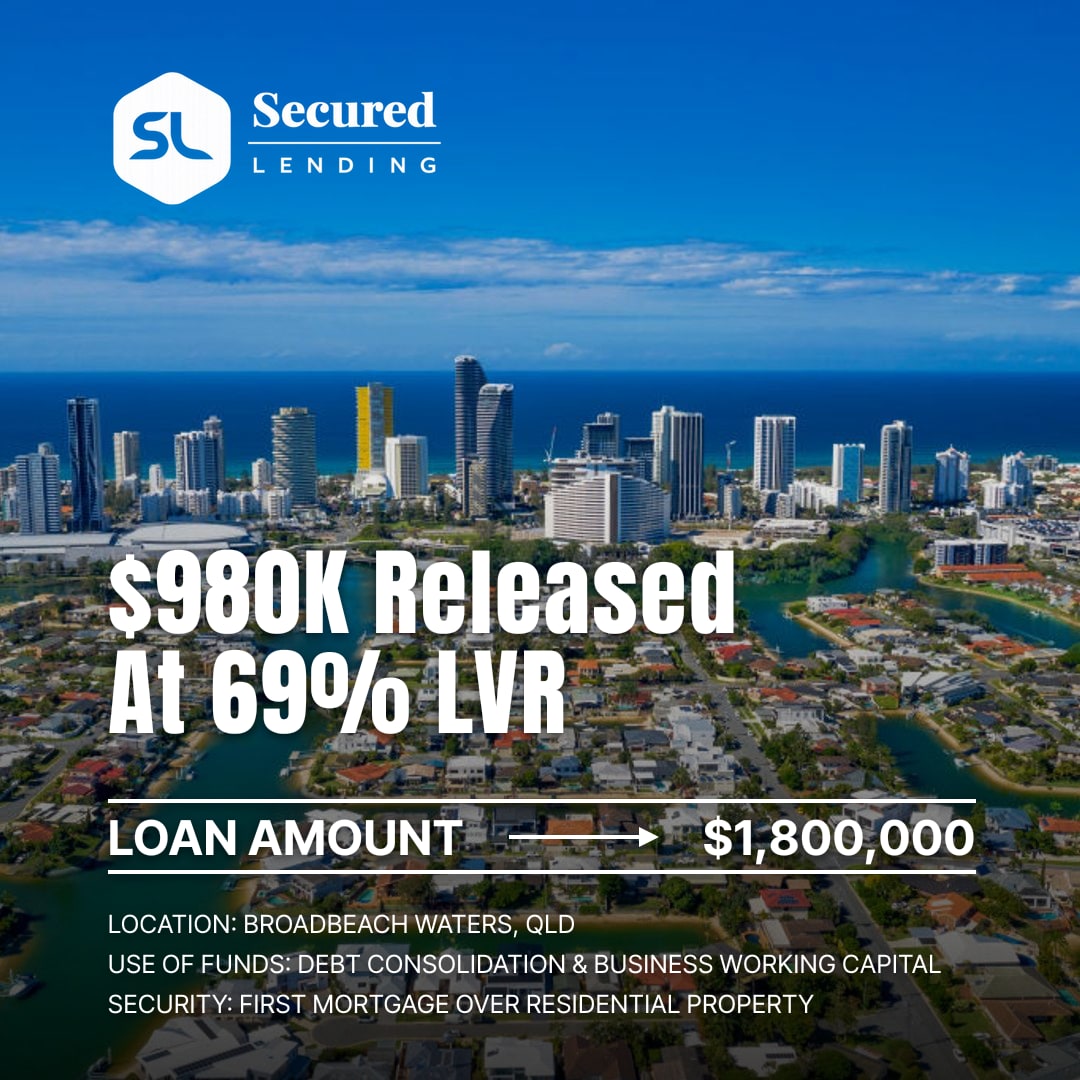
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
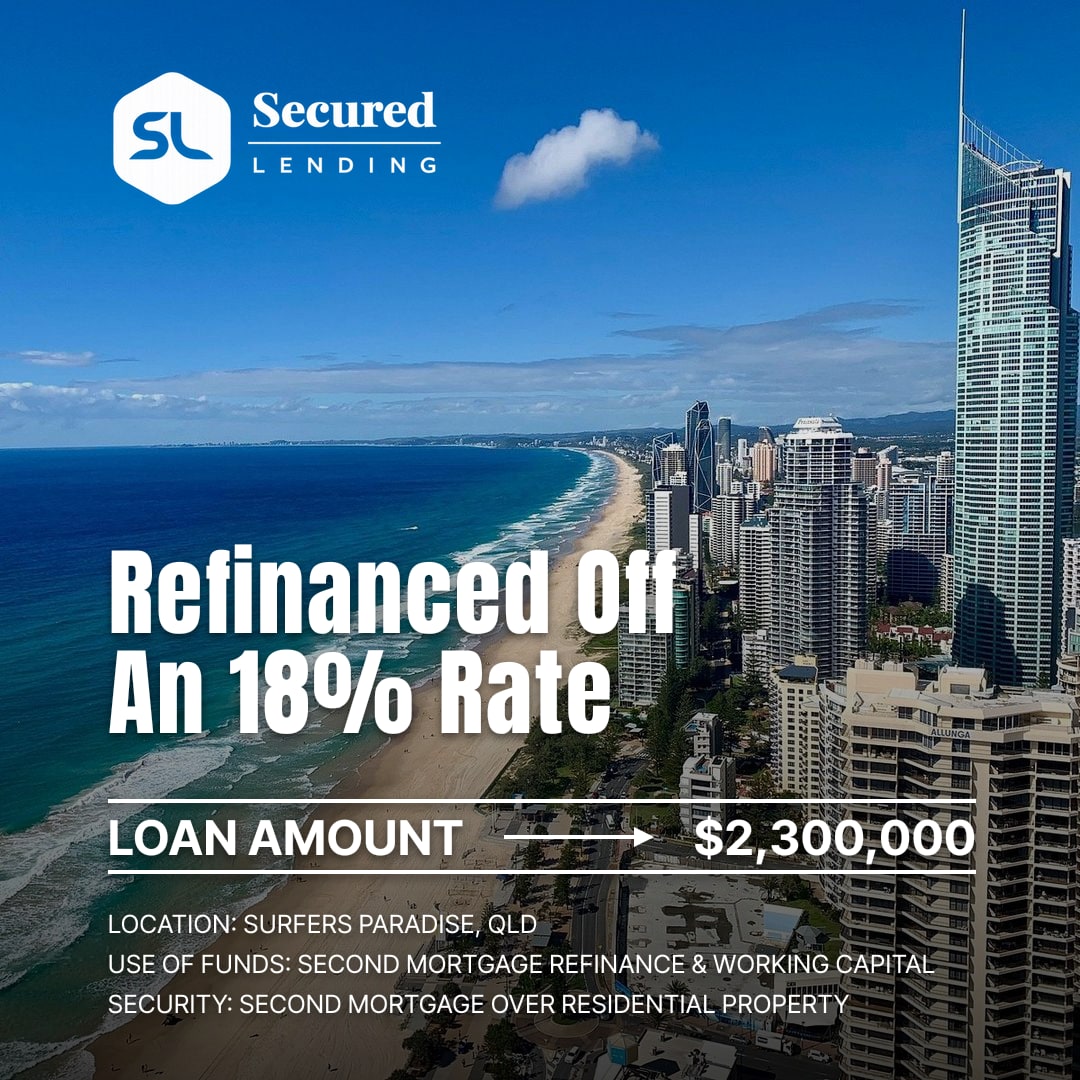
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
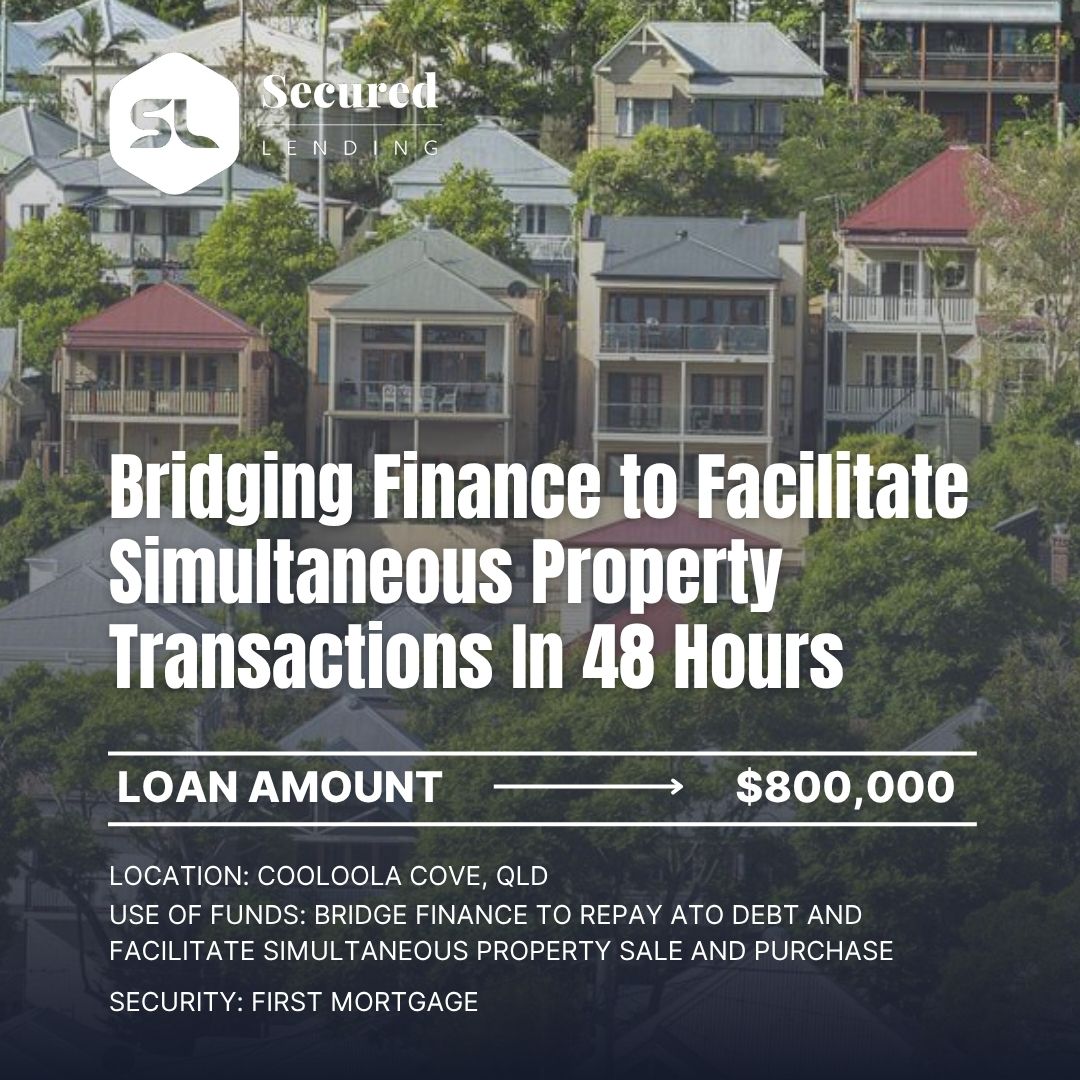
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
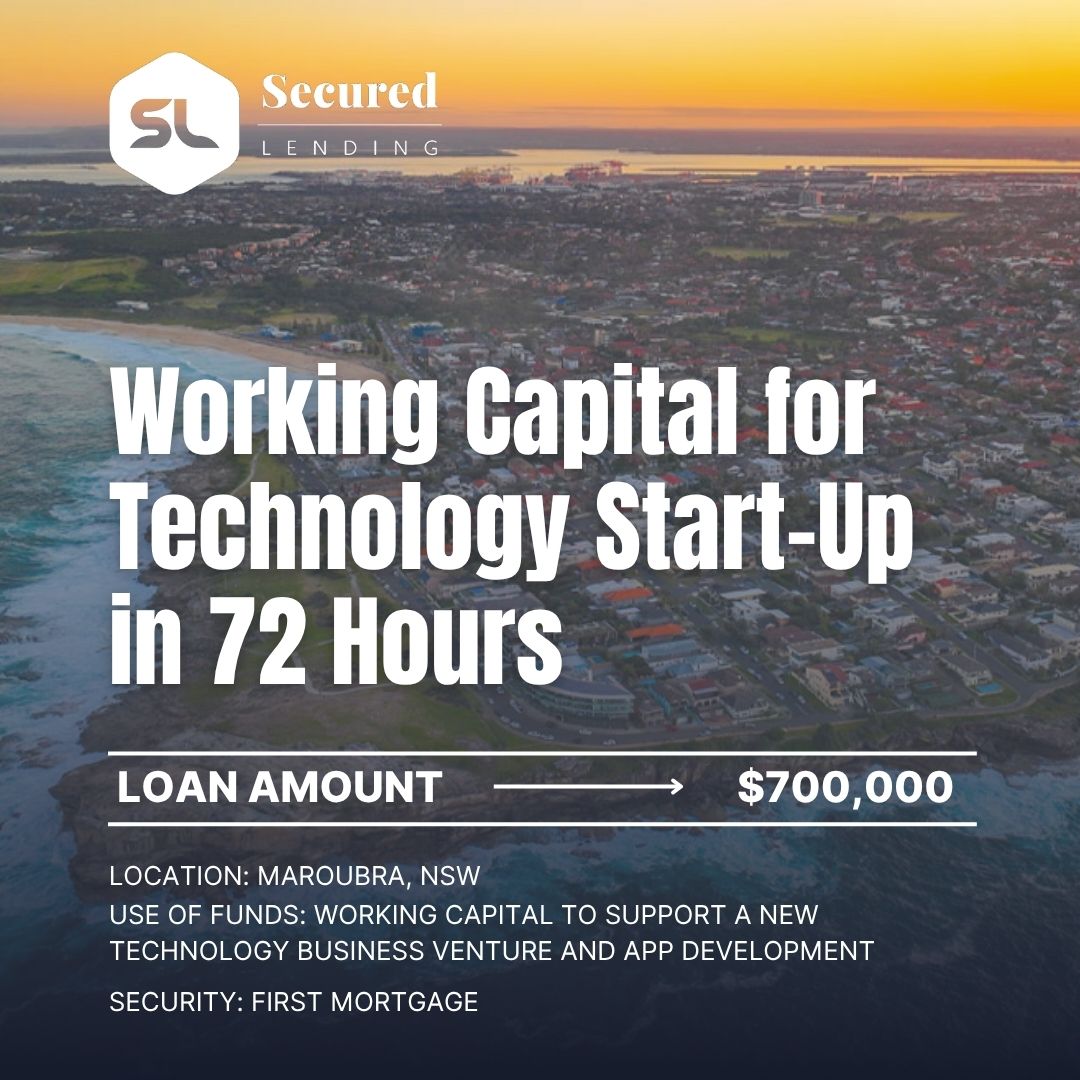
$700K Working Capital for a Technology Start-Up Settled in 72 Hours
$3M Working Capital for IT Business Expansion Settled in 2 Business Days
$1.9M Commercial Property Acquisition for Growing Doggy Daycare Business
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Other Urgent Loans We Fund
Each page covers one deadline: what we fund, what to send us and how quickly we can settle.