Urgent Short Term Loans to Buy Distressed and Mortgagee Sale Property

Buy the mortgagee, receiver or run-down property on the seller's terms, and refinance once it is repaired or leased
Expert
Expert
Expert

Experts in strategic, short-term finance
Aerial view of Sydney Harbour and the CBD
24hrsFast funding solutions
$250K-$10MLoan range
9.7% p.aInterest rates starting from
1-24 monthsShort term funding

ExcellentRated 5 out of 5 on Google

Rated 5 out of 5Jason V

Hands down, the best private lenders in the biz

Gino, Alec and Finn are exceptional at what they do. Top tier communication and transparent service.

Rated 5 out of 5Rhowell Dela Rosa

Every settlement has been smooth

Gino and the team at Secured Lending are our go-to when a deal needs to move fast or fall outside bank criteria.

Rated 5 out of 5Rory Mcgrath

Always my top choice for nearly all private lending scenarios

I run and operate a private lending brokerage and have worked with Mark and the team for years.

Rated 5 out of 5Luke Egan

Speed to market on lending advances second to none

The owner is also one of best commentators on LinkedIn calling out poor lending and recovery practices.

Rated 5 out of 5amal maharaj

True professionals in the non bank lending space

Straight forward application and assessment process with clear communication till loan settlement.

Rated 5 out of 5Sam Algeri

Excellent service, quick approvals and seamless settlements

The team at Secured Lending, particularly Gino and Finn, are fantastic to work with.

Rated 5 out of 5sebastian wright

Speed, reliability, transparency

Exceptional team. Exceptional Service. Loved working with the team at Secured Lending.

Rated 5 out of 5Jordan Thomas

Gino & Finn are the best in the business

Quick and painless to deal with, keep up the great work SL team!

Rated 5 out of 5Wayne McCarthy

Always willing to think outside the box to get deals done

We've had a great experience working with Secured Lending.

Rated 5 out of 5JP G

Quick, responsive and reasonable

With all the shady characters in the private lending market, its refreshing to find good people to deal with.

Rated 5 out of 5Joel Togo

Always thorough on assessment and will give you a prompt answer

With clients that are in time sensitive situations, this is crucial.

Rated 5 out of 5David Pruscino

Always professional and supportive

It's a pleasure dealing with the Secured team.

Rated 5 out of 5Monica Monsigneur

A professional and common sense lender who delivers

Rated 5 out of 5Thomas de Fegely

Great options in the private space

Have been dealing with Finn from Secured Lending, he has been very responsive.

Rated 5 out of 5Andrew Soo

A very reliable funding partner

Highly recommended.

Rated 5 out of 5Phil Boyle

Very efficient, responsive

Finn was a great help to assist in a very timely manner.

Distressed property can offer good value, but the seller usually sets firm terms: a short settlement, no finance clause and the property sold as it is. We can fund the purchase in as little as 24 hours, so you can meet those terms with confidence.

We lend on residential investment, commercial and industrial property bought from mortgagees, receivers, liquidators and motivated sellers across Australia. The loan runs for 1 to 24 months while you repair, lease or resell the property.

Types of distressed purchases we fund

  • •Mortgagee sales, where a lender is selling a borrower's property
  • •Receiver and liquidator sales of company property
  • •Run-down or unfinished buildings a bank will not lend on
  • •Properties with vacancies or rent arrears
  • •Off-market sales from owners who need to sell quickly

Why banks hesitate with distressed property

Banks prefer property in good condition with a steady income. A building that needs repairs, has no tenants or has an unusual history can take weeks to assess, and the seller will not wait. We value the property as it is today, and we look at your plan to repair, lease or sell it.

What the purchase loan includes

  • •The purchase price, or the part a bank will not lend
  • •Stamp duty and settlement costs
  • •Repairs needed to lease or sell the property
  • •Holding costs while the work is done

Meeting the seller's timeline

  1. Before you offer. Send us the listing or contract and the seller's terms. We come back to you with an indicative offer within hours.

  2. Inspection. Our in-house valuers inspect the property in its current condition.

  3. Letter of offer. You receive it as soon as the terms are agreed.

  4. Settlement. We can settle within 24 hours of you signing the letter of offer.

Details that speed up approval

  • •The contract, or the sale terms if you have not signed yet
  • •Any reports on the building's condition
  • •Your plan and budget for repairs or leasing
  • •Details of other property you can offer as security

Our loans for distressed purchases

Distressed purchase loan terms

Loan featureDetail
Loan sizeFrom $250,000, with larger loans assessed case by case
Interest rateFrom 9.7% p.a. on a first mortgage, from 11.95% p.a. on a second mortgage
Term1 to 24 months, interest only. Interest can be capitalised while repairs are done
Maximum LVR70% of the lower of the assessed value and the purchase price
SecurityA first mortgage over the property you are buying, valued in its current condition, plus other property if needed
SettlementFrom 24 hours

How buyers repay us

Most buyers repay us by refinancing to a bank once the property is repaired or leased and can be revalued. Others sell the property after the work is done. We agree the plan before settlement and set the term to allow for the repairs and leasing.

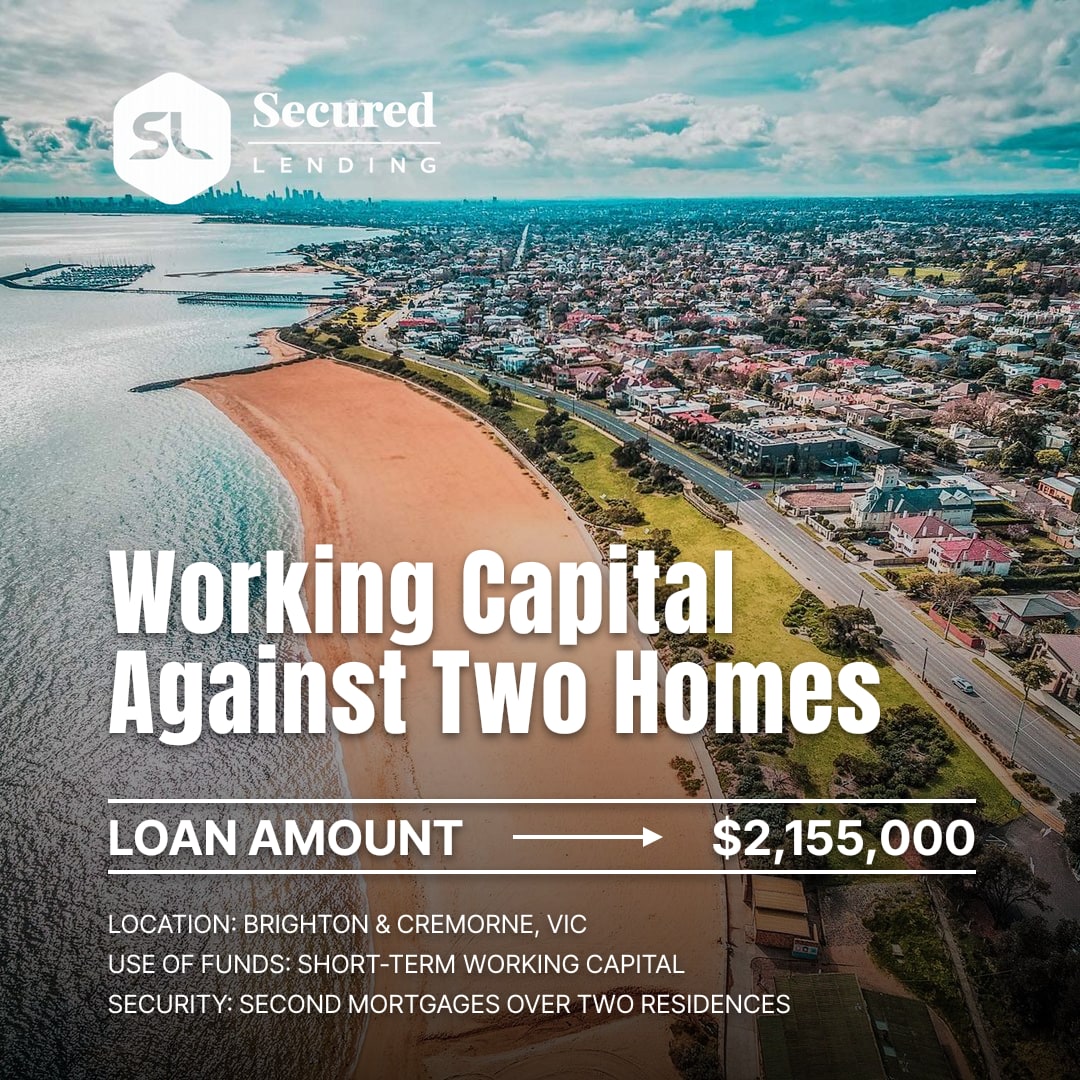
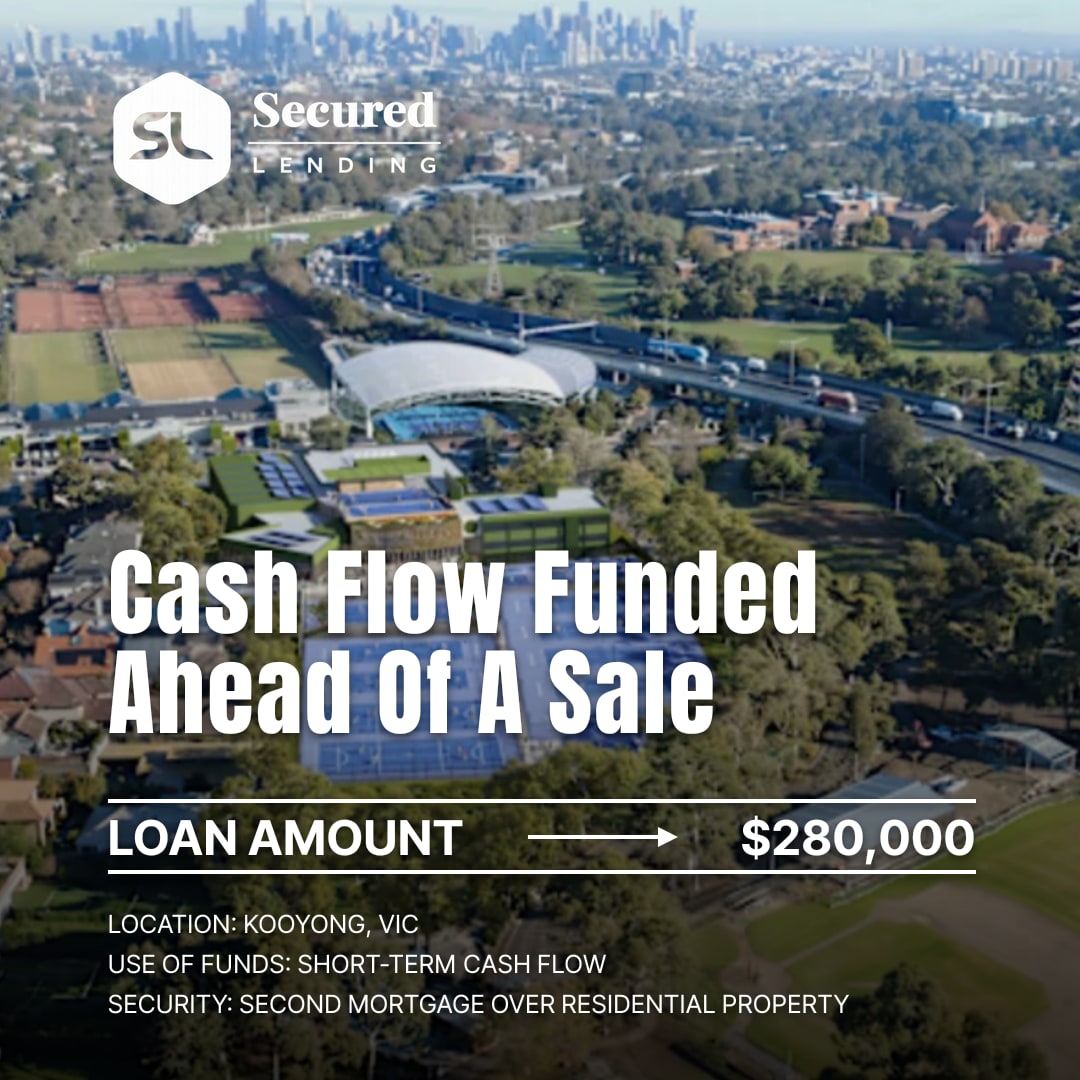
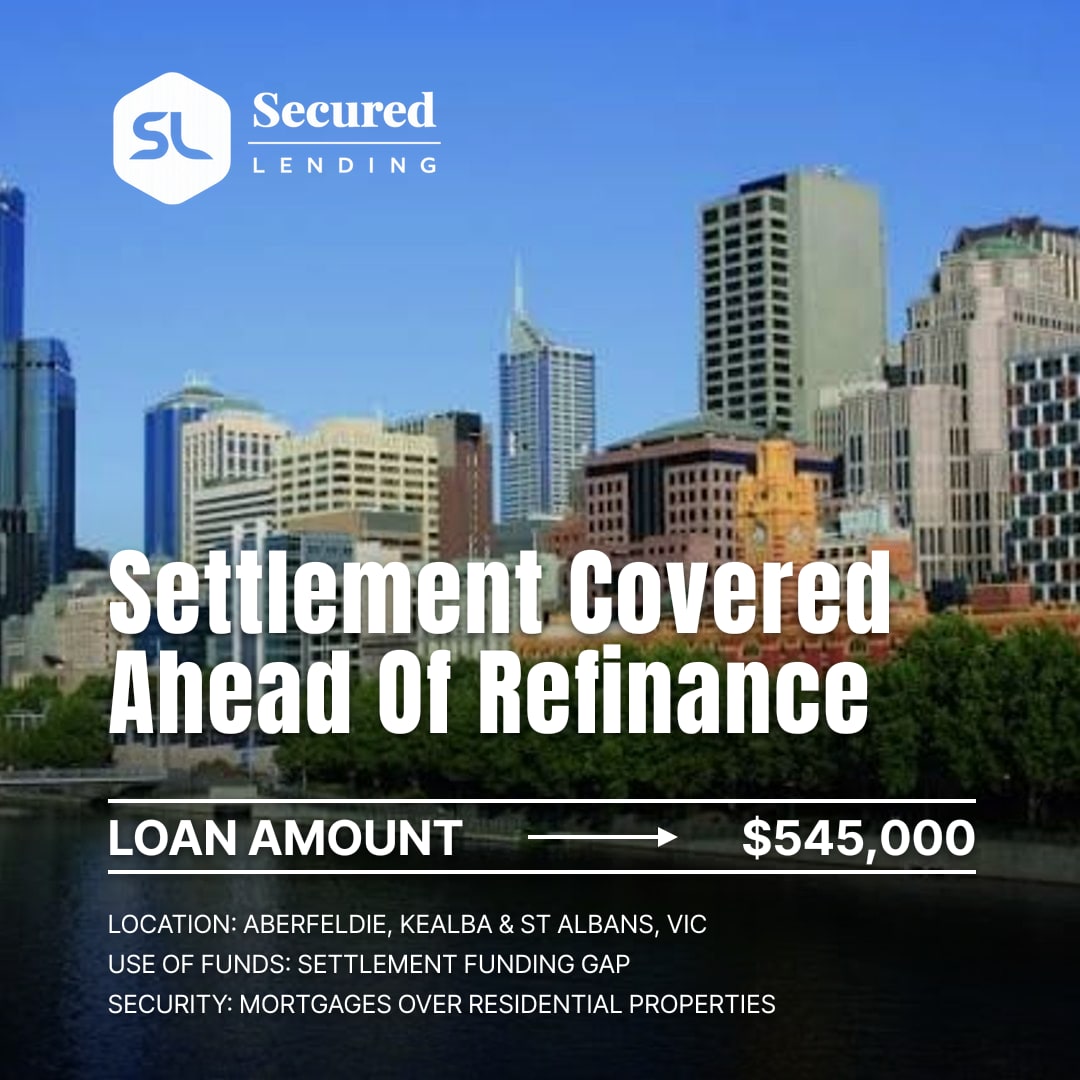
A distressed purchase we funded

“Mortgagee and liquidator sales often come with a fixed settlement date and no room to negotiate. The property may need work, which puts many banks off. We value the property as it stands and look at the buyer's plan for it. If both make sense, we can settle within the seller's timeline.”
Gino Tabila

Gino Tabila

Associate Director

Recently Asked Questions
Have the finance settled before the final contract arrives. Until contracts are exchanged, a receiver's sale can change, and an owner repaying its lender is one way that happens, so the time your company controls is the time it takes to be ready. Send us the draft contract today and arrange valuer access through the agent. Once our valuation is done and the letter of offer is issued, your company can exchange without a finance clause as soon as the final contract is sent. Ask your solicitor whether any of your costs can be recovered if the sale does not go ahead.

Up to $770,000, which is 70% of $1,100,000, if our valuation is at least the price. After the $110,000 deposit, $990,000 is due at settlement, so about $220,000 plus stamp duty and costs has to come from the company's funds or another property it or a director owns. Send us the auction contract and the settlement date today, so our valuer can inspect the house in its current condition well inside the 30 days.

It does not change how we assess the loan. Our valuers inspect the factory and value it as it is, in its current condition. With no warranties, your own checks matter more. Have your solicitor review the title and the contract, get a building report before you sign, and send the report to us so the valuer has it.

The loan is based on the lower figure. If our valuation is $1,300,000, the loan can be up to $910,000, which is 70% of $1,300,000, rather than $1,050,000 on the price, a difference of $140,000. That is why it helps to send us the details before you sign, so you know our valuation while there is still time to negotiate or add another property as security.

About 9 to 12 months allows for the four months of work, a sale campaign and settlement after an exchange. Our terms run from 1 to 24 months, and we agree the repayment plan before settlement. If the sale is slower than planned, tell us early. A refinance once the repairs are done is the usual second option, so keep the repair invoices and photos ready for a valuer.

Yes. Another property you own can be added as security, within 70% across both. The warehouse supports up to $560,000, which is 70% of $800,000 if our valuation meets the price, and the unit adds up to $220,000, because 70% of $600,000 is $420,000 and $200,000 is already owing. That is up to $780,000 in total, secured by a first mortgage over the warehouse property and a second mortgage over the unit.

We cannot promise what a bank will lend, but you can test it before you buy. Ask a bank or broker what share of the value it lends on a leased shop of that type, apply it to the value you expect after the repairs, and compare the answer with our loan. If the bank figure is lower than our loan, plan now for the difference, from savings, another property or a sale. We look at the same plan before settlement.

We need to learn your scenario further. Our valuers inspect the property before we lend, so ask the liquidator's agent for an access time for our valuer before exchange, even a short one. If access is only possible after exchange, we tell you how that affects the settlement timing and the conditions in our offer, so you can decide before you sign.

We can aim to have it valued before Friday. Our in-house valuers usually inspect within a day or two, so send us the tender documents and the receiver's access times today. Once the valuation is done and terms are agreed, the conditions left in our offer are ones you control. If the timing is too tight for a valuation, we tell you plainly what we can confirm before Friday.

Yes. One loan can be secured by a first mortgage over both townhouses, up to 70% of their combined value or the total price, whichever is lower, with loans from $250,000. If you plan to sell one townhouse to repay part of the loan, tell us before settlement, because how the loan is repaid is agreed at the start.

Yes. Your company can be the borrower for a property it buys to repair and sell, because that is a business purpose. The first mortgage is over the house, and a director's property can be added as extra security within 70% if the company needs a larger loan. Send the contract, your repair budget and the sale plan, including who will sell the house and at what expected price.

We can work to most mortgagee and liquidator timelines, and same-day funding is possible depending on your scenario. Send the sale terms before you sign, so our valuer can inspect the property early.

Yes, where the property has value in its current condition. The loan is based on that value, and the repair costs can be included as long as the total stays within 70%. We will want to see your repair budget and plan.

Yes. Receivers and liquidators usually set fixed timelines and sell the property as it is. We have funded purchases from liquidators within days, and we work to their settlement dates.

Yes. Interest can be capitalised, and council rates, insurance and other holding costs can be included, as long as the total stays within 70% of the property value. That means no monthly payments while the property earns no income.

Yes. Buyers of distressed property are often builders, trades or property businesses, and they need cash for materials, labour and holding costs between sales. We lend to construction and real estate businesses for working capital as well as purchases.

No. We lend for business purposes only, such as a property you will rent out, repair and resell, or use for your business.

Our in-house valuers assess what the property would sell for today in its current condition. We do not lend on the value after repairs, but that value helps us understand your repayment plan.

Experience is not essential, but we will ask about it. If you are new to renovating or leasing, tell us who will manage the repairs or leasing and share your budget. A realistic plan and a sensible LVR make a strong application.

Secured Lending team
Expert
Expert
Expert
$500M+ funded

Get an indicative offer within hours, not weeks.

No credit check. No obligation.

Why Secured Lending?

✓Australian private lender, $500M+ funded
✓We use our own funds for fast decisions
✓24-hour settlements, loans from $250k
✓Rates from 9.7% p.a. | Terms 1 to 24 months

Are you a broker? Find out why brokers love working with us.

Success Stories

Case Studies

View all case studies
Expert
Expert
Expert
$500M+ funded

Get an indicative offer within hours, not weeks.

No credit check. No obligation.

Why Secured Lending?

✓Australian private lender, $500M+ funded
✓We use our own funds for fast decisions
✓24-hour settlements, loans from $250k
✓Rates from 9.7% p.a. | Terms 1 to 24 months

Are you a broker? Find out why brokers love working with us.