Urgent Short Term Loans for SMSF Business Premises Settlements
Settle the fund's purchase of business premises on time, then move to a long-term SMSF lender
Experts in strategic, short-term finance
SMSF property purchases have more steps than most: a holding trust, trustee approvals and a lender that understands the rules. When the settlement date is close and a long-term SMSF lender cannot finish in time, we can provide a short term loan to settle, then be repaid once the long-term loan is in place.
Since 10 August 2026, a new limited recourse borrowing arrangement can only be used to buy business real property. We fund SMSF purchases of business premises, such as the building a member's business operates from, and refinances of limited recourse loans that were in place before that date.
What the rules allow
The ATO limits how an SMSF can borrow, and every loan we write for an SMSF follows those limits:
- •The loan must buy a single asset, such as one commercial property
- •New arrangements from 10 August 2026 can only buy business real property, which the ATO describes as land and buildings used wholly and exclusively in a business
- •The borrowed money can pay for repairs and maintenance, but not improvements
- •The property can carry no other mortgage or charge, so a first mortgage is the only option
- •The lender's recourse is limited to the property the fund bought
When SMSF trustees call us
- •The fund has contracted to buy business premises, and the long-term lender will not be ready by settlement
- •The fund's existing limited recourse loan is expiring, or its lender is leaving the SMSF market
- •A member's business needs the fund to own its premises before the current lease ends
- •A related party is selling business real property to the fund at market value on a fixed date
- •The bank's SMSF team has asked for more time than the contract allows
Advice comes first
We are a lender, not a financial adviser, and we cannot advise on whether your fund should buy a property or how the purchase should be structured. The ATO recommends advice from a qualified, licensed professional, and anyone advising on an SMSF must hold an Australian financial services licence or be authorised by a licensee. Please speak to your licensed SMSF adviser first. We work with them to meet the settlement date.
Settling an SMSF purchase with us
Enquiry. Send us the contract, the fund's details and your SMSF adviser's name. We confirm indicative terms within hours.
Structure check. Our solicitors review the holding trust and trustee documents with your adviser. This step adds a few days, so call us as early as you can.
Valuation. Our valuers inspect the premises the fund is buying.
Settlement. An SMSF settlement usually takes around five business days, rather than the 24 hours possible on our other loans.
Documents for an SMSF loan
- •The contract of sale for the business premises
- •The SMSF trust deed and the trustee's details
- •The holding trust deed your adviser has arranged for the purchase
- •The lease between the fund and the business, if a member's business will occupy the premises
- •Your adviser's plan for the long-term loan
The one loan that fits an SMSF purchase
- •First mortgage: over the business premises the fund is buying, because the rules allow no other charge over it
Second mortgages, caveat loans and lines of credit are not available for SMSF purchases, because the rules allow no other charge over the property.
SMSF loan terms
| Loan feature | Detail |
|---|---|
| Loan size | $250,000 to $10,000,000 |
| Interest rate | From 9.7% p.a. on a first mortgage |
| Term | 1 to 24 months, interest only, as a bridge to a long-term SMSF lender |
| Maximum LVR | 70% of the lower of the assessed value and the purchase price |
| Security | A first mortgage over the business real property the fund is buying, held in the holding trust |
| Settlement | Usually around five business days |
Repaying with a long-term SMSF loan
Our loan is short term by design, and SMSF property is usually held for many years. The usual plan is a long-term SMSF lender refinancing our loan, or occasionally the sale of the property. We agree the plan with your adviser before settlement.
“SMSF purchases are one of the few loans where speed depends as much on the paperwork as on the property. The holding trust and the fund's documents need to be right before settlement, and they are hard to fix afterwards. We work with the fund's adviser early, so the settlement date is met and the long-term lender can take over without delays.”
Gino Tabila
Associate Director
Frequently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
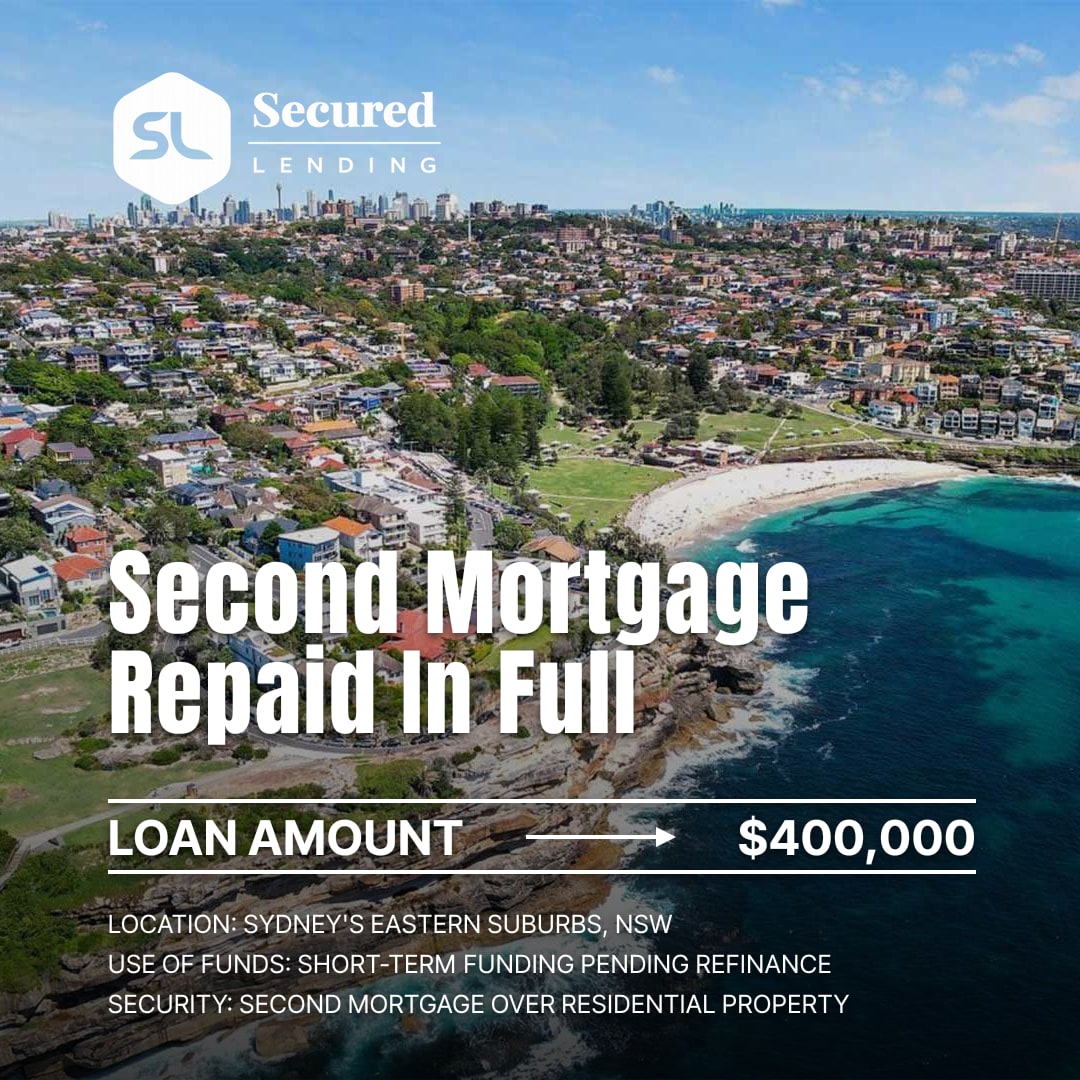
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
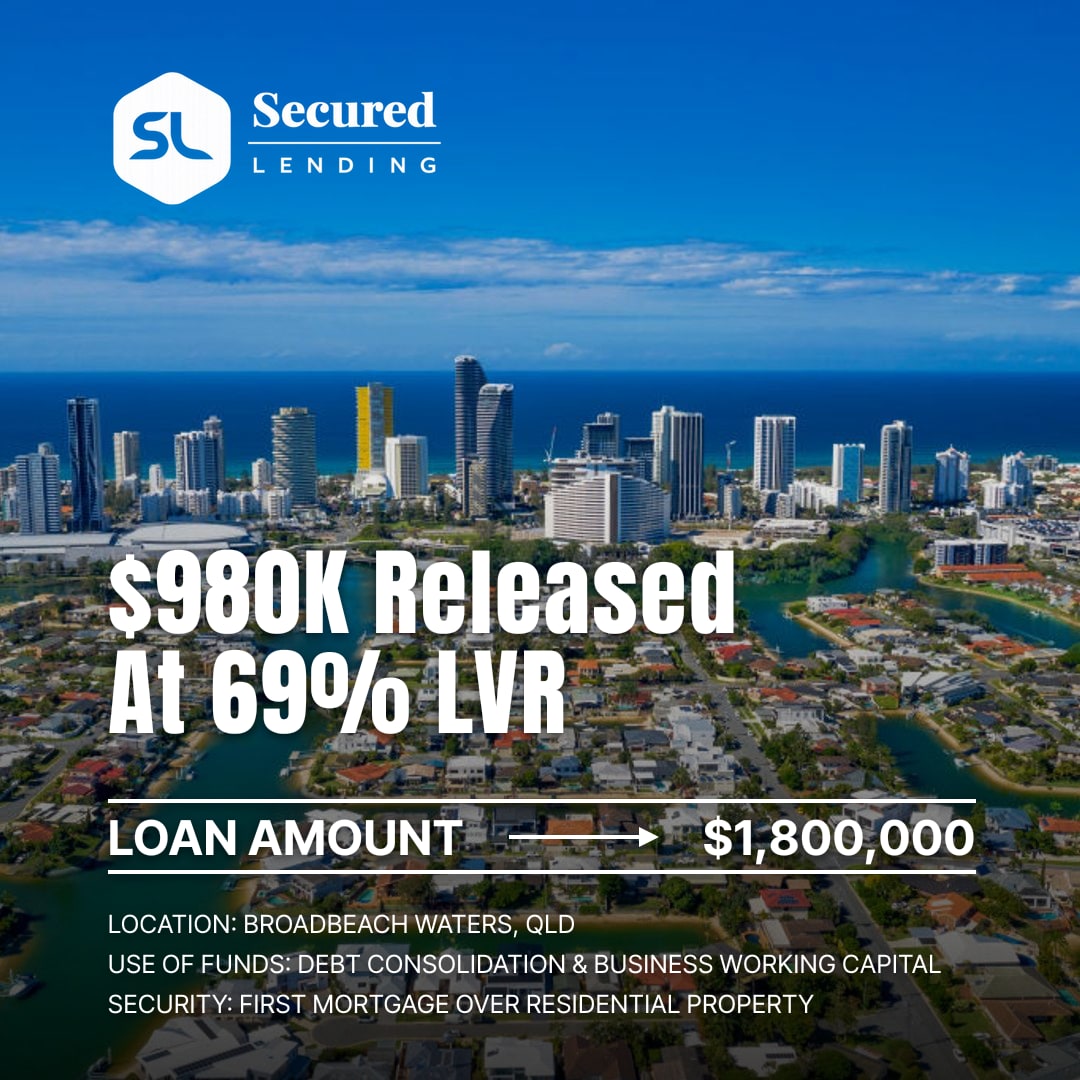
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
$700K Working Capital for a Technology Start-Up Settled in 72 Hours
$3M Working Capital for IT Business Expansion Settled in 2 Business Days
$1.9M Commercial Property Acquisition for Growing Doggy Daycare Business
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Other Urgent Loans We Fund
Each page covers one deadline: what we fund, what to send us and how quickly we can settle.