Stalled Development? Urgent Short Term Finance to Buy or Refinance the Site
Take control of a stalled project, then bring in a new builder and construction lender
Experts in strategic, short-term finance
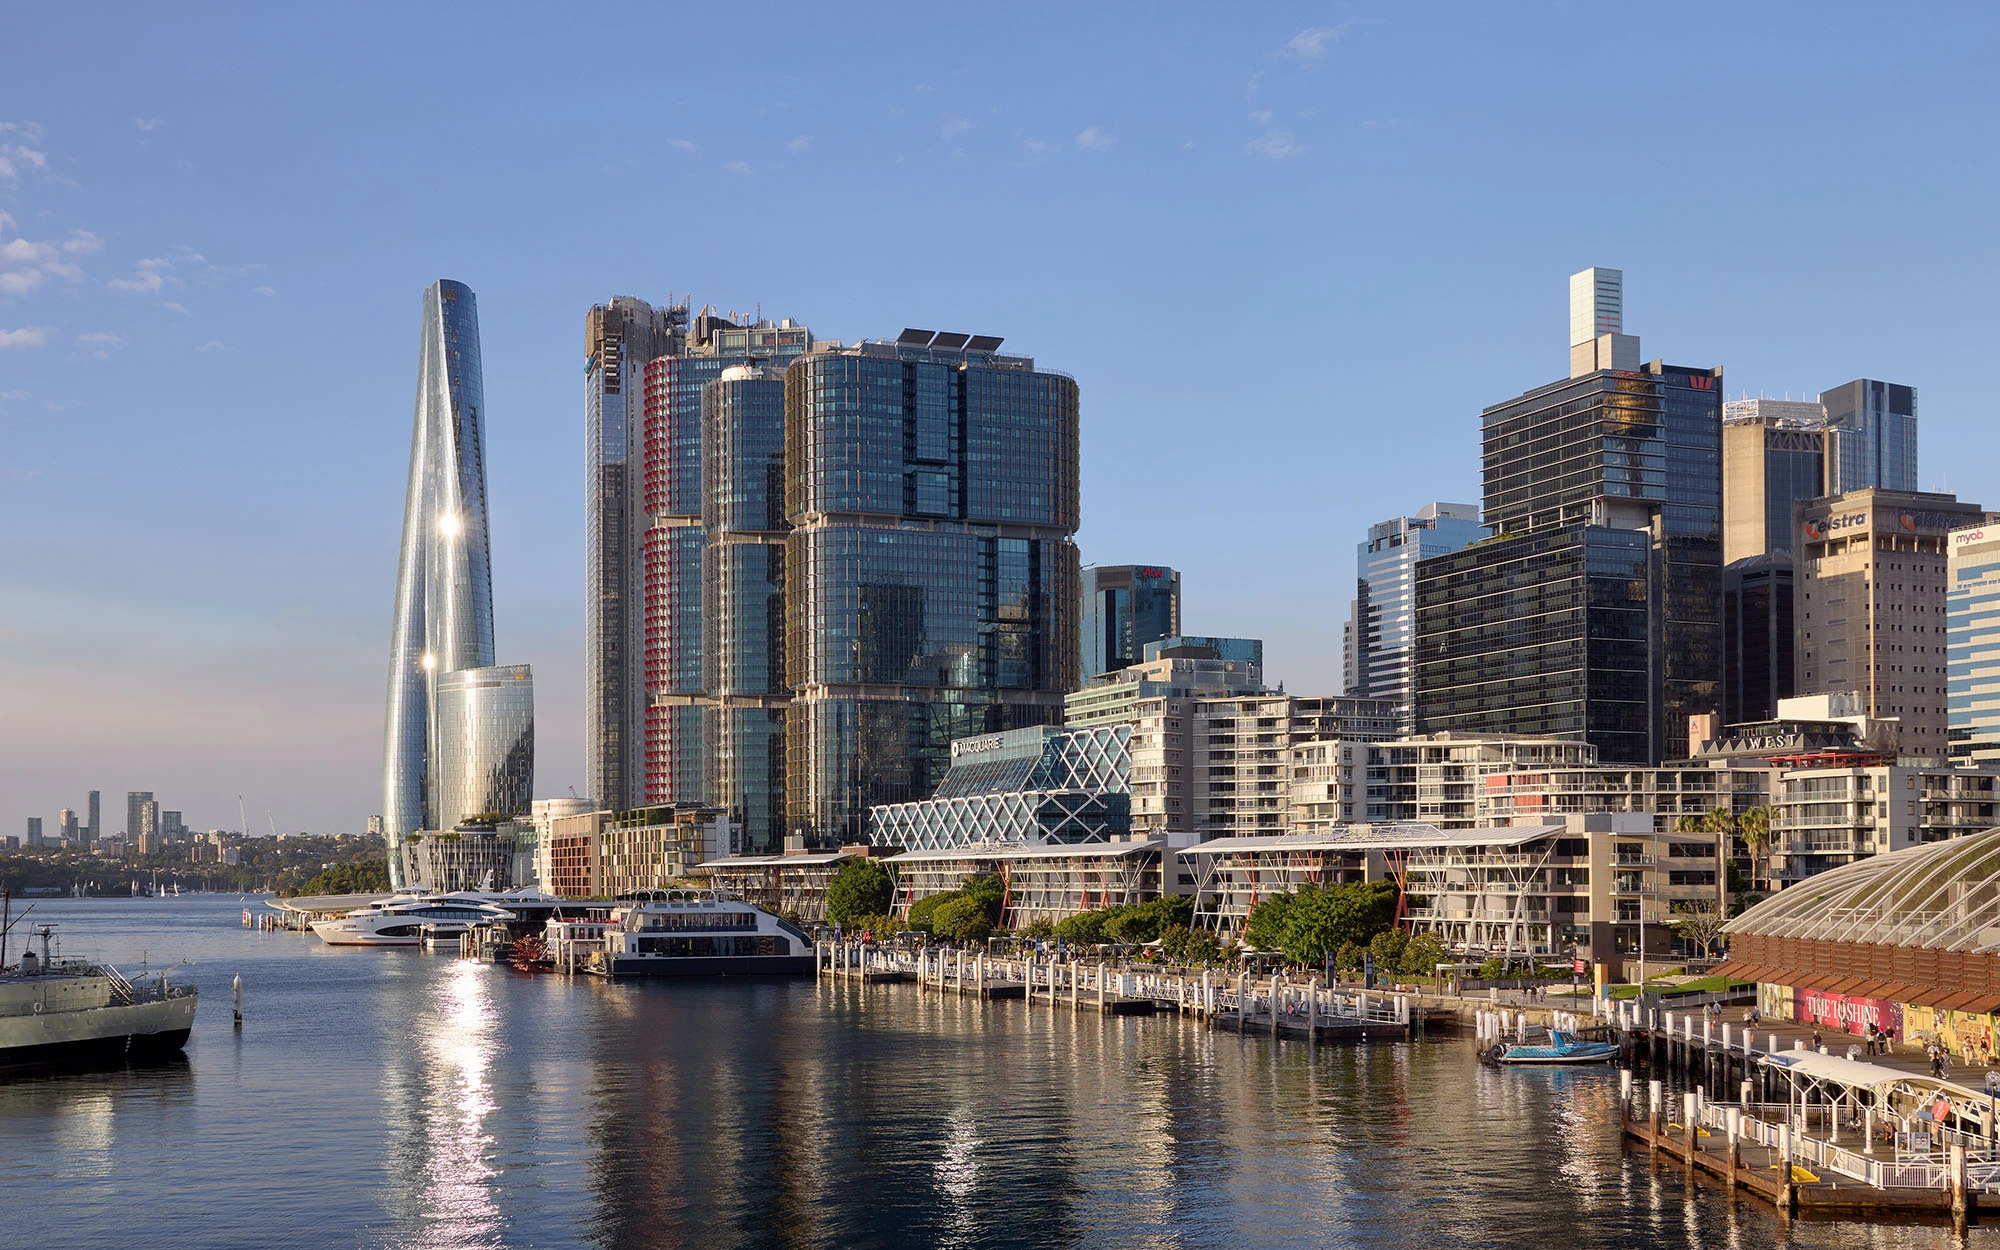
When a builder goes into liquidation or a construction loan expires before the build is finished, the site needs a lender that will value it as it stands. Banks rarely lend on a part-built site, and the existing lender may want to be repaid quickly. We can refinance the site, or fund the purchase of a stalled project, in as little as 24 hours.
We fund the land and the part-built property as they stand. We do not fund the rest of the build: a construction lender does that once a new builder and contract are in place. Our loan gives you the time to arrange it.
Why banks step back from part-built projects
The Reserve Bank has noted that the largest losses on developer lending have historically come from incomplete buildings. A part-built project is hard to value, the cost to finish is uncertain, and off-the-plan contracts move closer to their sunset dates while completion is delayed. Most banks decline these sites.
When developers call us about a stalled site
- •The builder has gone into liquidation and work has stopped
- •The construction loan has expired before completion
- •The construction lender has issued a default or review notice
- •A receiver or mortgagee is selling a part-built site with a short settlement
- •A joint venture partner wants to exit the project
- •Off-the-plan contracts are approaching their sunset dates
What our loan covers
- •Paying out the existing construction lender
- •Buying a stalled site from a receiver, mortgagee or another developer
- •Holding costs while you appoint a new builder
- •Consultant and quantity surveyor fees to price the remaining work
How we value a stalled project
Our in-house team, which includes people with direct development experience, values the site and the work completed as it stands today. We do not lend on the value of the finished project. We also look at what it will cost to finish, because that decides how realistic the repayment plan is.
Getting a stalled site funded
Call us. Tell us what has stopped the project, how far the build has progressed and when you need the funds. Indicative terms follow within hours.
Site inspection. Our team inspects the site and reviews the building contract, the progress claims and any quantity surveyor report.
Letter of offer. Agree the terms, and the letter of offer is issued the same day.
Settlement. We can pay out the existing lender within 24 hours of a signed letter of offer, subject to its discharge process.
Information for a stalled project
- •The title and the existing lender's payout figure
- •The building contract, progress claims and any cost-to-complete report
- •The DA and construction certificate
- •The status of any off-the-plan sales
- •Your plan for finishing the project, including the new builder and lender
Loans for a stalled site
- •First mortgage: to refinance the existing lender or buy the site as it stands
- •Second mortgage: behind a construction lender that keeps its first mortgage, to cover arrears or holding costs
- •Bridging loans: to settle on a mortgagee or receiver sale before another property sells
- •Caveat loans: for a few weeks, such as paying out a caveat on the title so the refinance can settle
Stalled site loan terms
| Loan feature | Detail |
|---|---|
| Loan size | $250,000 to $10,000,000 |
| Interest rate | From 9.7% p.a. on a first mortgage, from 11.95% p.a. on a second mortgage |
| Term | 1 to 24 months, interest only, capitalised if needed |
| Maximum LVR | 70% of the value as it stands, or of the lower of that value and the price on a purchase |
| Security | A first or second mortgage over the site, plus other property you own if needed |
| Settlement | From 24 hours |
How the site loan is repaid
Our loan is usually repaid when a new construction lender funds the rest of the build and pays us out, or takes first position with our loan behind it. Some owners sell the site as it stands instead. We agree the repayment plan with you, and set the term to allow time to appoint a builder and arrange the construction loan.
A development loan we funded
“When a project stalls, the land and the work already done still have value, but the owner needs a new builder and a new construction loan to finish it. We value what is there, look closely at what it will cost to complete, and fund the refinance or purchase. That gives the owner time to bring in a new builder instead of selling the site at a discount.”
Gino Tabila
Associate Director
Frequently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
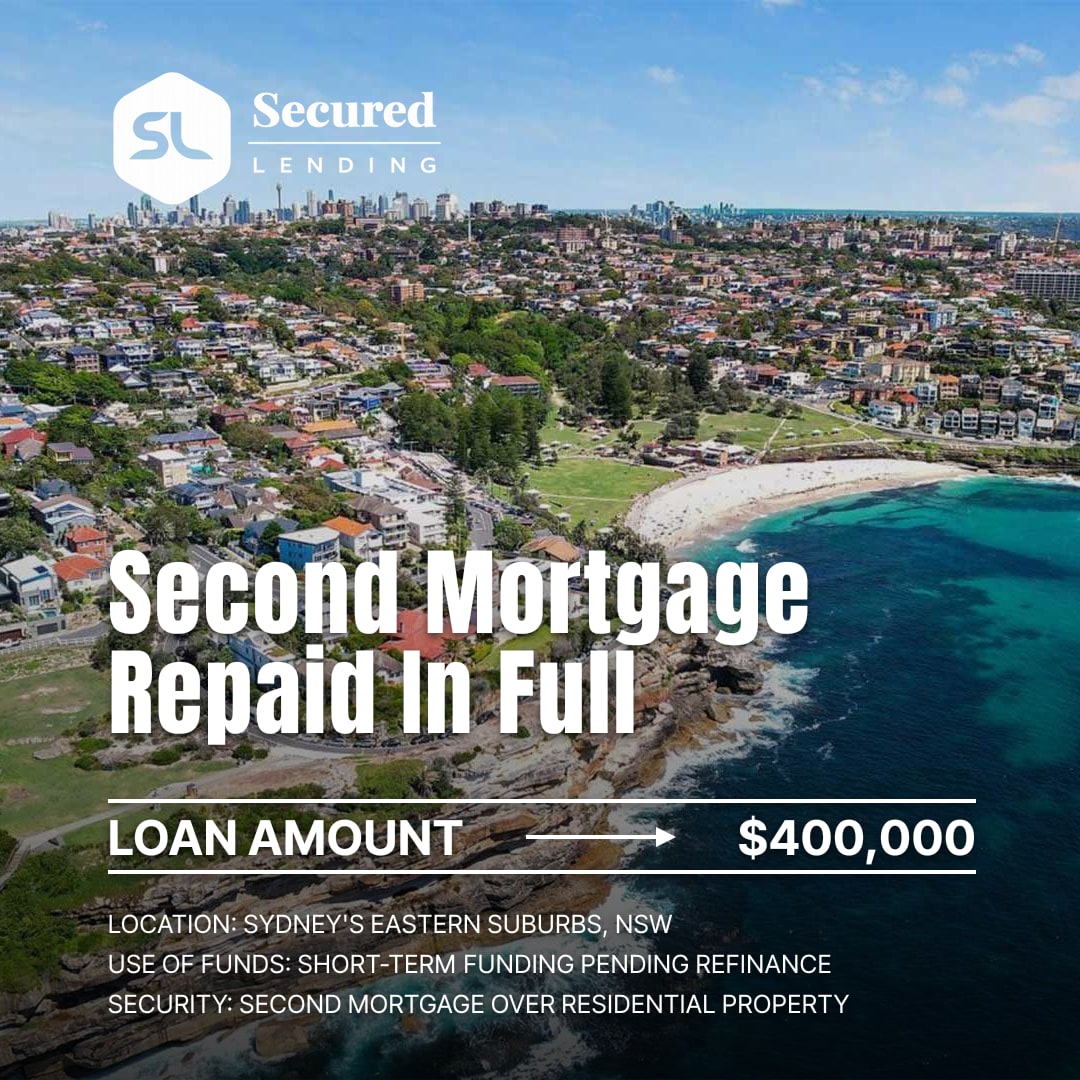
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
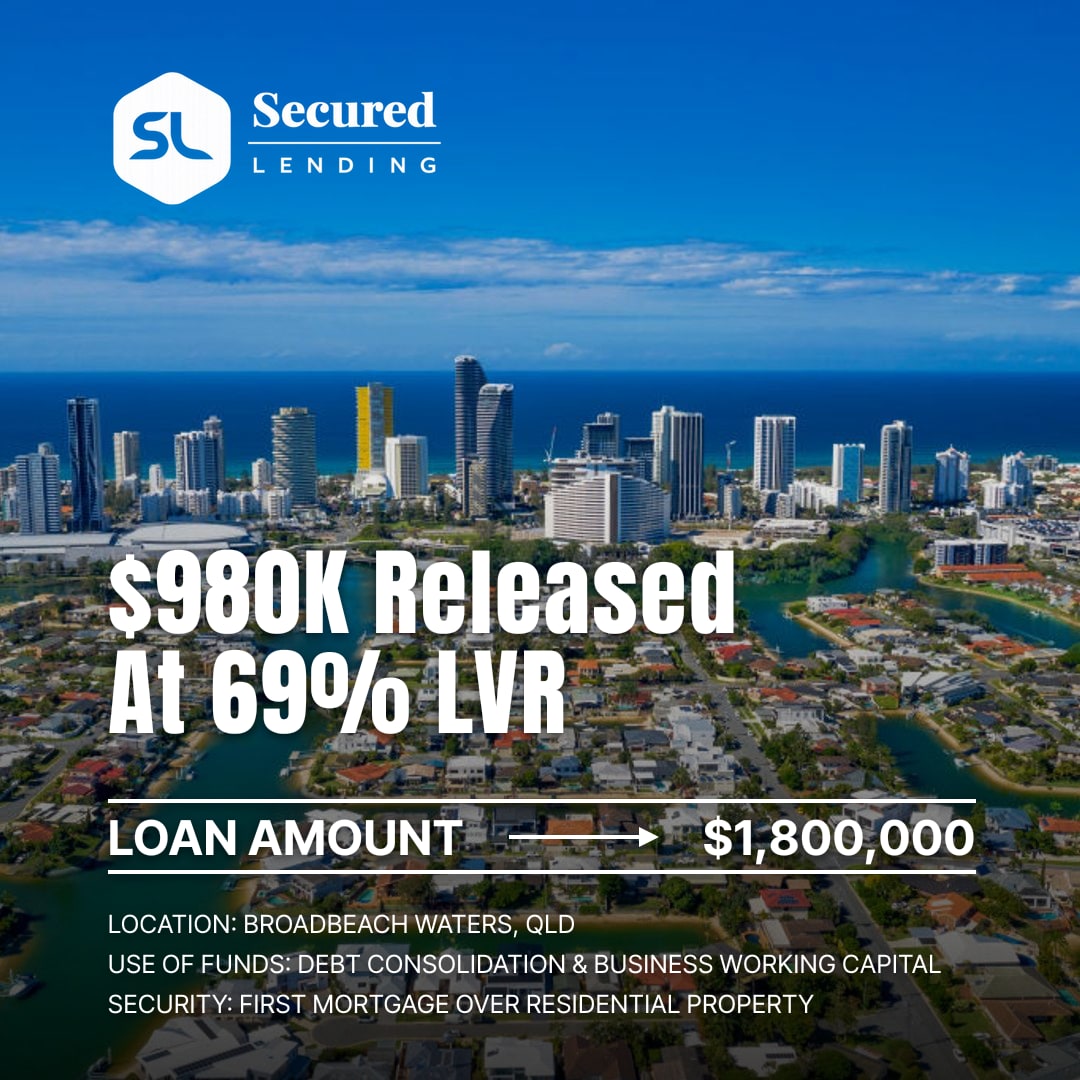
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
$700K Working Capital for a Technology Start-Up Settled in 72 Hours
$3M Working Capital for IT Business Expansion Settled in 2 Business Days
$1.9M Commercial Property Acquisition for Growing Doggy Daycare Business
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Other Urgent Loans We Fund
Each page covers one deadline: what we fund, what to send us and how quickly we can settle.