Bank Finance Fell Through? Settle With an Urgent Short Term Loan
Keep your deposit and your settlement date when a bank approval is withdrawn or delayed
Experts in strategic, short-term finance
When a bank withdraws or delays its approval close to settlement, it is stressful, especially with your deposit at risk. We can fund the purchase in as little as 24 hours, so you settle on the agreed date and arrange long-term finance afterwards.
We fund commercial, industrial and investment property purchases for businesses and investors across Australia. We lend our own funds and use our own valuers, so we do not need to repeat the process the bank has stopped.
Why bank approvals fall through
- •The bank valuation came in below the purchase price
- •The approval expired before the settlement date
- •The bank changed its lending policy, or reassessed your income, after giving conditional approval
- •A condition such as a signed lease or a building report could not be met in time
- •The bank needs more time, and the seller will not move the settlement date
- •A co-buyer or investor withdrew their share of the funds
In many of these cases the property and your equity have not changed. The bank has run out of time, or its policy no longer fits your purchase.
What happens if you do not settle
If you do not settle on the agreed date, the seller can issue a notice to complete, which sets a new, short deadline. If that deadline passes, the seller may be able to end the contract, keep your deposit and claim costs from you. Your solicitor or conveyancer can confirm the exact dates under your contract. Arranging replacement finance as soon as the bank says no gives you the most options.
How we get you to settlement
First call. Tell us the settlement date, the purchase price and what the bank has said. An indicative offer is usually ready within hours.
Valuation. Our own valuers can usually inspect the property within a day. Ask the agent to arrange access while we prepare the offer.
Letter of offer. Once you accept the terms, we issue the letter of offer straight away and work directly with your solicitor or conveyancer.
Settlement. Settlement is possible within 24 hours after the letter of offer is signed.
Documents that speed things up
- •A copy of the contract and the date settlement is due
- •The bank's approval, withdrawal or valuation letter
- •Proof of your deposit and the funds you have available
- •Details of any other property you own, if the purchase needs extra security
- •Your plan to repay us, usually a bank loan once the cause of the delay is fixed, or a sale
Which of our loans can help
- •First mortgage: over the property you are buying, in place of the bank loan
- •Second mortgage: over another property you own, if the valuation came in short
- •Bridging loans: to settle now and refinance or sell later
- •Caveat loans: fast funding from equity in a property you own
Loan terms
| Loan feature | Detail |
|---|---|
| Loan size | $250,000 to $10,000,000 |
| Interest rate | From 9.7% p.a. (first mortgage), from 11.95% p.a. (second mortgage) |
| Term | 1 to 24 months, interest only. Most loans of this kind run for 3 to 6 months |
| Maximum LVR | 70% of the lower of the assessed value and the purchase price |
| Security | A first mortgage over the property you are buying. Another property you own can be added for a larger loan |
| Settlement | From 24 hours |
Moving to a long-term loan
Most buyers repay us by refinancing to a bank once the reason for the delay is fixed. That might be a new valuation, a signed lease or another year of financial statements. We set the term so you have enough time to do this without rushing, and the letter of offer explains the early repayment terms.
Settlements we have saved
“When a bank pulls out a few days before settlement, the buyer usually still has a good property, a deposit paid and a plan for long-term finance. What they need is a lender that can make a decision quickly. We look at the property and how the loan will be repaid, and we can often settle within a day or two of receiving the contract.”
Gino Tabila
Associate Director
Frequently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
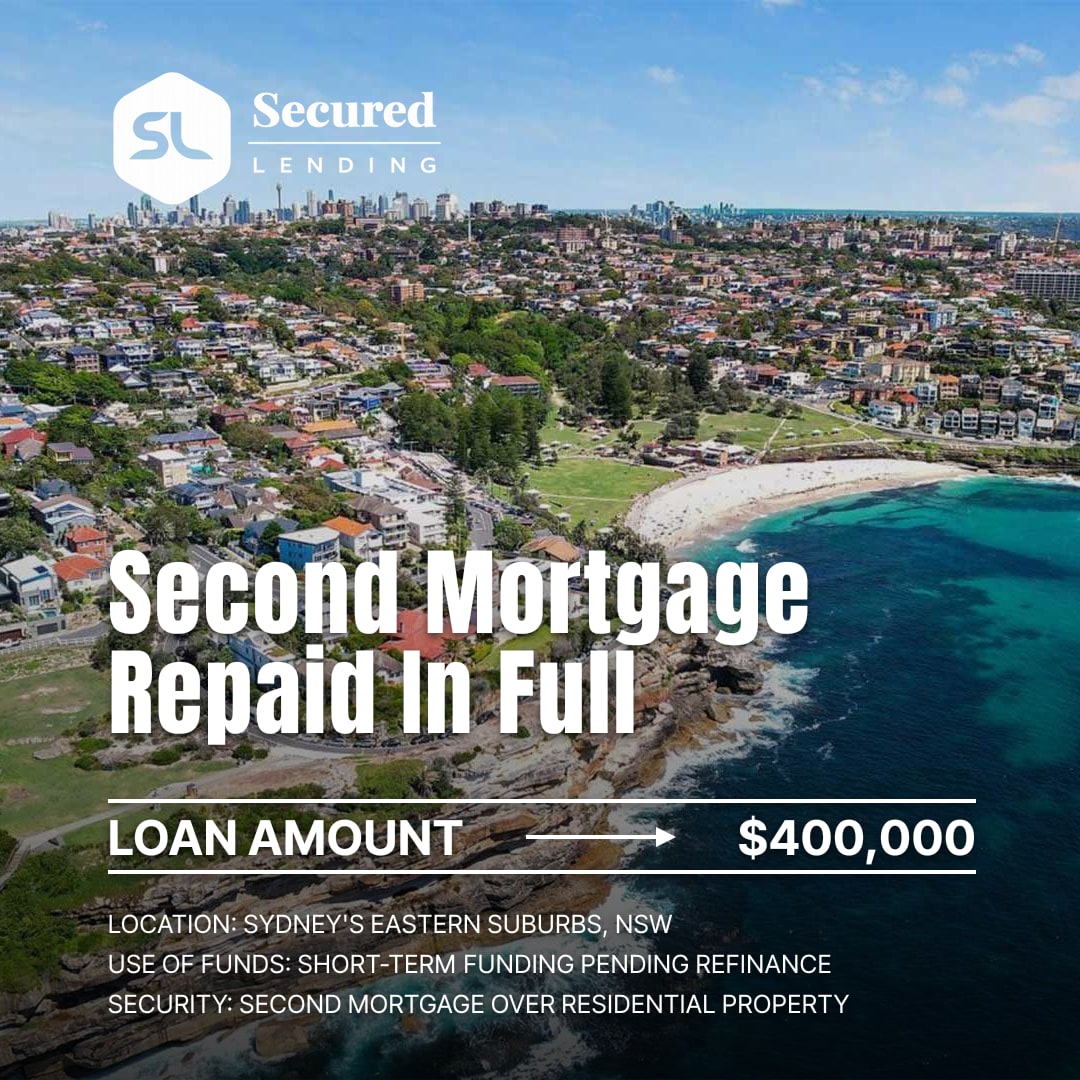
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
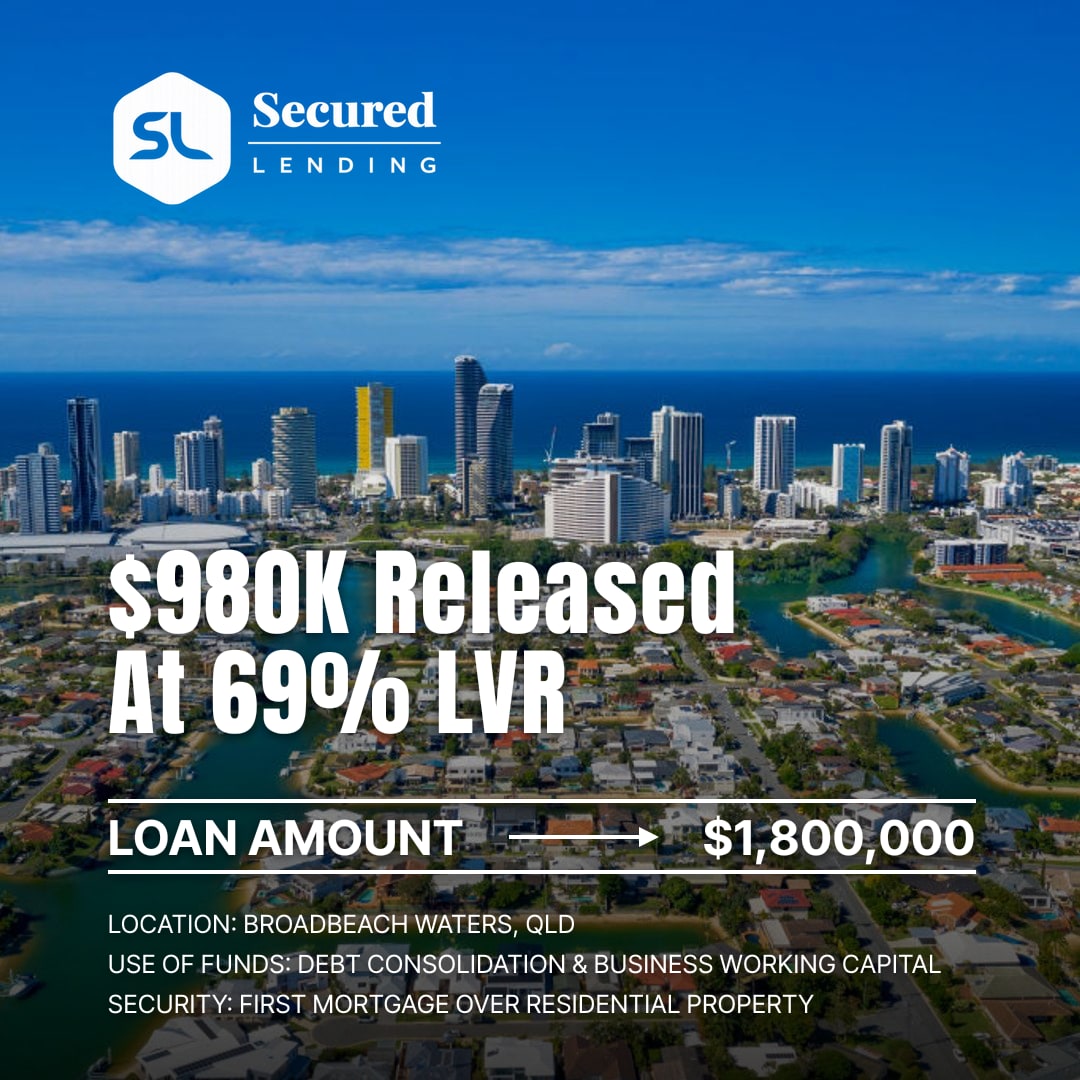
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
$700K Working Capital for a Technology Start-Up Settled in 72 Hours
$3M Working Capital for IT Business Expansion Settled in 2 Business Days
$1.9M Commercial Property Acquisition for Growing Doggy Daycare Business
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Other Urgent Loans We Fund
Each page covers one deadline: what we fund, what to send us and how quickly we can settle.