Urgent Short Term Loans to Settle a Motel or Hotel Purchase

Settle on the freehold accommodation property, then refinance once you are trading
Expert
Expert
Expert

Experts in strategic, short-term finance
Aerial view of Sydney Harbour and the CBD
24hrsFast funding solutions
$250K-$10MLoan range
9.7% p.aInterest rates starting from
1-24 monthsShort term funding

ExcellentRated 5 out of 5 on Google

Rated 5 out of 5Jason V

Hands down, the best private lenders in the biz

Gino, Alec and Finn are exceptional at what they do. Top tier communication and transparent service.

Rated 5 out of 5Rhowell Dela Rosa

Every settlement has been smooth

Gino and the team at Secured Lending are our go-to when a deal needs to move fast or fall outside bank criteria.

Rated 5 out of 5Rory Mcgrath

Always my top choice for nearly all private lending scenarios

I run and operate a private lending brokerage and have worked with Mark and the team for years.

Rated 5 out of 5Luke Egan

Speed to market on lending advances second to none

The owner is also one of best commentators on LinkedIn calling out poor lending and recovery practices.

Rated 5 out of 5amal maharaj

True professionals in the non bank lending space

Straight forward application and assessment process with clear communication till loan settlement.

Rated 5 out of 5Sam Algeri

Excellent service, quick approvals and seamless settlements

The team at Secured Lending, particularly Gino and Finn, are fantastic to work with.

Rated 5 out of 5sebastian wright

Speed, reliability, transparency

Exceptional team. Exceptional Service. Loved working with the team at Secured Lending.

Rated 5 out of 5Jordan Thomas

Gino & Finn are the best in the business

Quick and painless to deal with, keep up the great work SL team!

Rated 5 out of 5Wayne McCarthy

Always willing to think outside the box to get deals done

We've had a great experience working with Secured Lending.

Rated 5 out of 5JP G

Quick, responsive and reasonable

With all the shady characters in the private lending market, its refreshing to find good people to deal with.

Rated 5 out of 5Joel Togo

Always thorough on assessment and will give you a prompt answer

With clients that are in time sensitive situations, this is crucial.

Rated 5 out of 5David Pruscino

Always professional and supportive

It's a pleasure dealing with the Secured team.

Rated 5 out of 5Monica Monsigneur

A professional and common sense lender who delivers

Rated 5 out of 5Thomas de Fegely

Great options in the private space

Have been dealing with Finn from Secured Lending, he has been very responsive.

Rated 5 out of 5Andrew Soo

A very reliable funding partner

Highly recommended.

Rated 5 out of 5Phil Boyle

Very efficient, responsive

Finn was a great help to assist in a very timely manner.

Accommodation properties are specialised, and banks often need a going-concern valuation and several years of occupancy figures before they will lend. When settlement is due before those are ready, we can fund the purchase of the freehold in as little as 24 hours.

We lend on freehold motels, hotels and boutique hotels across Australia, valued on a going-concern basis. The money can pay for the purchase, furniture and fittings, and a refurbishment. The liquor licence, the furniture and the goodwill are never the security.

Why accommodation purchases take longer

  • •A manager's residence and a mix of direct and booking-platform income make the valuation more detailed
  • •Some motels are on strata or leasehold titles, which some banks avoid
  • •A liquor licence transfer runs on its own timetable
  • •Some banks limit their lending on regional or tourism property

Liquor licence transfers in NSW

Liquor & Gaming NSW says a licence transfer does not take effect until provisional approval is given, which usually happens within 10 business days of a complete application, with confirmation usually within 60 days. The business can keep trading while the transfer is assessed, and the owner of the premises can be the licensee for 28 days from becoming entitled to possession. Other states have their own processes.

When accommodation buyers call us

  • •The contract settles before the bank's valuation is complete
  • •The operator's lease has ended, and the freehold owner needs to run the motel
  • •A refurbishment must be finished before the peak season
  • •The adjoining property is for sale
  • •The current loan is expiring and the bank will not renew

Funding a motel or hotel

  1. Day one. Send the contract, the occupancy figures and the settlement date. Indicative terms follow within hours.

  2. Inspection. Our valuers inspect the motel and review the occupancy and trading figures.

  3. Licence timing. Your solicitor lines up settlement with the liquor licence transfer, if the property is licensed.

  4. Settlement. We can settle inside 24 hours of the letter of offer being signed.

Figures to send for a motel

  • •The contract of sale
  • •Occupancy and trading figures for the last two or three years
  • •The liquor licence details, if the property is licensed
  • •Your experience running accommodation, or that of your manager
  • •Your refinance plan

Loan options for motel buyers

Terms for a motel or hotel purchase

Loan featureDetail
Loan sizeFrom $250,000, with larger loans assessed case by case
Interest rateFrom 9.7% p.a. (first mortgage), from 11.95% p.a. (second mortgage)
Term1 to 24 months, interest only
Maximum LVR70% of the lower of the assessed value and the purchase price
SecurityA first mortgage over the freehold property, valued on a going-concern basis. Never the licence, the furniture or the goodwill
SettlementFrom 24 hours

Refinancing once you are trading

Buyers usually refinance to a bank once the motel has traded through a full peak and off-peak season under their ownership. Some sell another property instead.

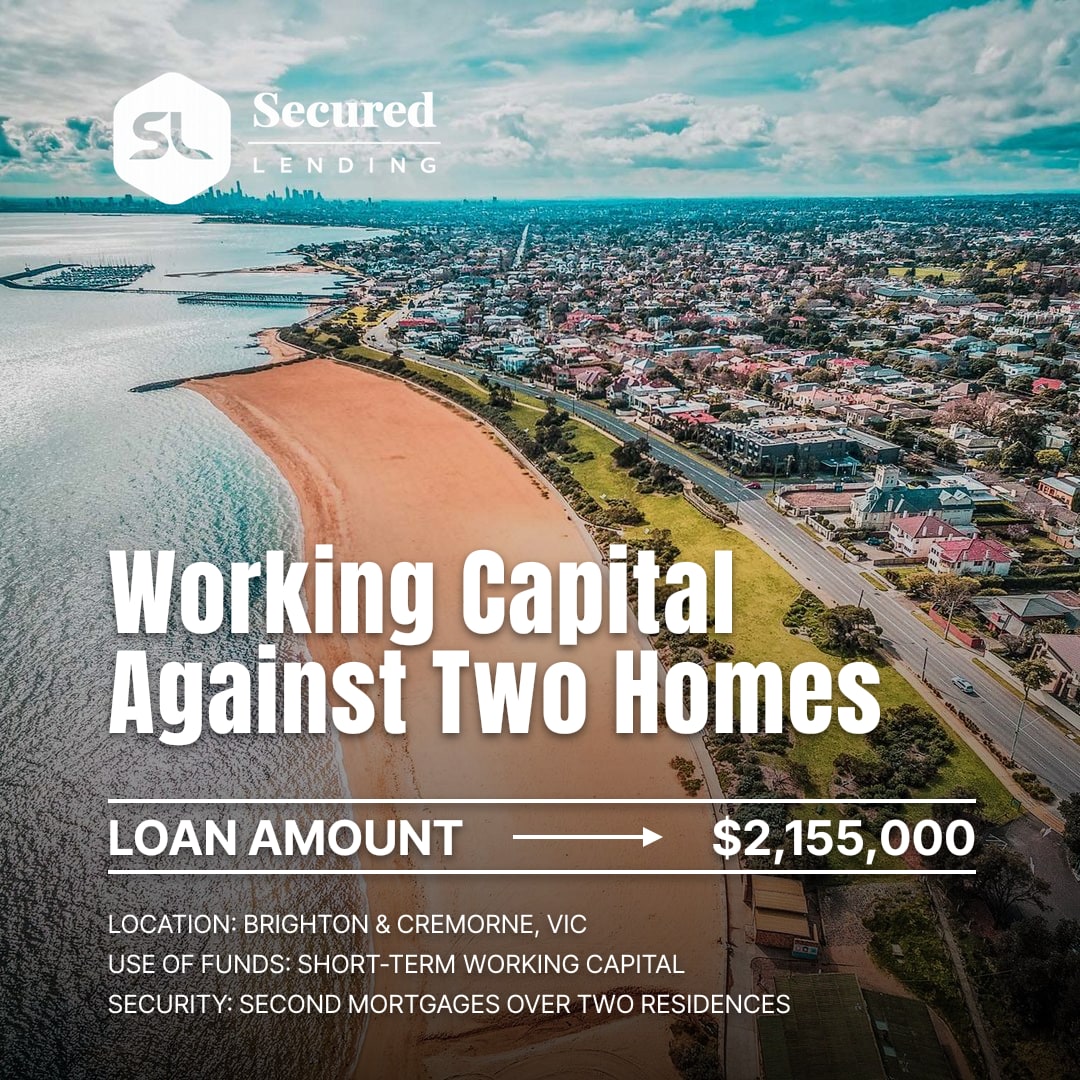
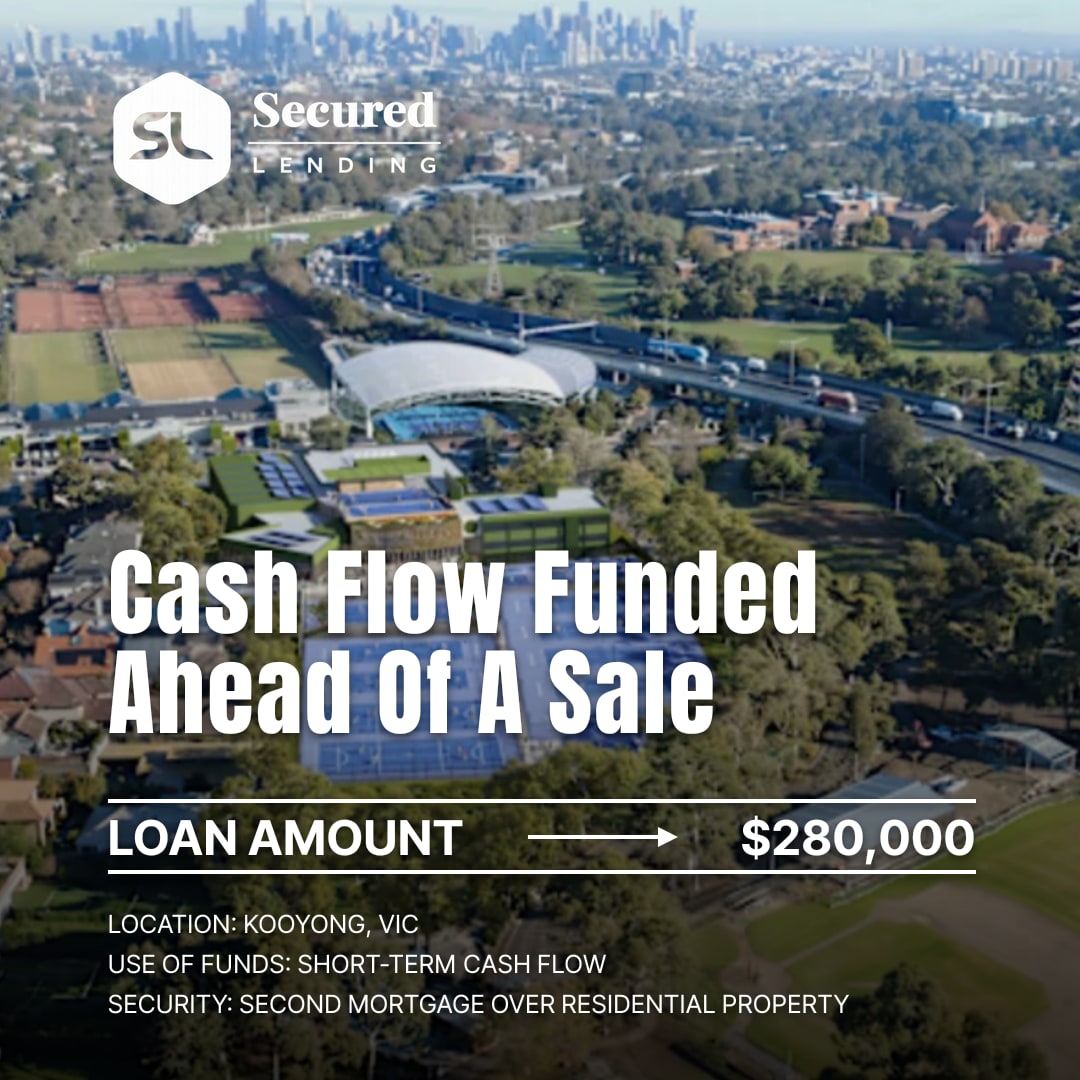
A hospitality loan we funded

“Motels and hotels are valued on their trading figures as well as the land and buildings, and that takes a specialist valuer and several years of occupancy data. The bank often needs weeks for both. We lend on the freehold, valued on a going-concern basis, so the buyer can settle and start trading while the bank completes its assessment. Send us the occupancy figures, and we will give you our view the same day.”
Gino Tabila

Gino Tabila

Associate Director

Recently Asked Questions
We can look at it, where the bank's payout figure fits within 70% of our valuation of the freehold. We assess the freehold and your plan to repay us, such as a sale in the stronger season or a bank refinance once trading recovers. Send us the bank's written payout figure, the last two years of monthly trading figures and that plan. We do not give insolvency advice, but we can connect you with insolvency specialists in our network, who can explain what repaying the bank in full means for the receiver's appointment.

We need to learn your scenario further. Our valuers review the occupancy and trading figures, including where the bookings come from and what the platforms deduct, as part of a going-concern valuation of the freehold. Send a breakdown of direct and platform bookings for the last two or three years, and the bank valuer's report if you have it.

Yes, where another property you own secures the loan. The company buying the business is the borrower. A motel lease and the business are never our security, so the loan is secured by your home, an investment property or other real property, up to 70% of its value. Send us the sale contract and details of the property you can offer.

Up to about $3,010,000 using both properties. On a purchase we lend up to 70% of the lower of the value and the price, so we work from $2.9 million for the motel, and 70% of $4.3 million across the motel and your home is $3,010,000. That leaves about $190,000 of the price, plus stamp duty and costs, to come from your own funds.

No. The loan is for buying the operating motel business and its freehold, which is a business purpose, and the manager's residence is part of the freehold property that secures it. Tell us how the residence is treated in the motel's trading figures, because our valuers include it in the going-concern valuation.

Yes. A bridging loan can be secured by both freeholds, up to 70% of their combined value, and it is repaid from the proceeds when your current motel sells. Tell us when you plan to list and what the agent expects, so the term runs past a realistic sale date.

Yes. An ATO debt on its own is not a reason we decline, and $350,000 is within our range. The loan is secured by the freehold property, valued on a going-concern basis, and the funds are paid to the company, which pays the ATO in full. The loan is then repaid through a defined exit, such as a bank refinance after the peak season.

Yes, where the freehold supports the loan. We lend up to 70% of the freehold's value on a going-concern basis, and terms can come back within hours of your enquiry, which leaves most of the 45 days for the valuation and the documents. Send us the bank's letter, the loan statement and two or three years of occupancy figures.

Yes. Our in-house valuation team assesses unique and non-standard property, and values a boutique hotel on a going-concern basis using its trading figures as well as the building. Send us the contract and three years of trading figures, and we will tell you within hours whether we can proceed.

We need to learn your scenario further. We ask about your experience running accommodation, or your manager's, because it affects how the motel trades and how a bank will view the refinance. Tell us about the manager, their contract and how long they have run this motel.

Yes, as a lump sum paid at settlement. The cost of the works can be included in the loan within 70% of the lower of the value and the price, and it is paid in one amount, not drawn in stages as the work progresses. Send us the order and the contractors' quotes with your enquiry.

In NSW, a transfer takes effect once provisional approval is given, usually within ten business days of a complete application, and the business can keep trading while it is assessed. Your solicitor can time settlement around it, and other states have their own processes.

Yes. The furniture, fittings and booking system are what the money buys, paid as a lump sum at settlement within 70% of the property value. They are never the security.

Yes, as part of the loan at settlement, within 70% of the property value. Tell us the budget and the season you are working towards, and we will set the term to run past the peak season.

Yes. In NSW, the owner of the premises can be the licensee for 28 days from becoming entitled to possession. We can refinance or fund working capital while you run the motel or find a new operator.

The term can change. We set it to run through a full peak and off-peak season if the bank refinance needs one, and seasonal occupancy is already reflected in the going-concern valuation.

Yes. We can fund the purchase of the adjoining property and add it to the security. We do not fund the construction of new rooms.

Same-day funding is possible for a motel purchase, depending on your scenario. Send the occupancy figures with your enquiry, because they are the first thing our valuers review.

Yes. We lend for working capital to motels, hotels, caravan parks and other tourism and hospitality businesses, including staff and supplier payments in the quieter months.

Secured Lending team
Expert
Expert
Expert
$500M+ funded

Get an indicative offer within hours, not weeks.

No credit check. No obligation.

Why Secured Lending?

✓Australian private lender, $500M+ funded
✓We use our own funds for fast decisions
✓24-hour settlements, loans from $250k
✓Rates from 9.7% p.a. | Terms 1 to 24 months

Are you a broker? Find out why brokers love working with us.

Success Stories

Case Studies

View all case studies
Expert
Expert
Expert
$500M+ funded

Get an indicative offer within hours, not weeks.

No credit check. No obligation.

Why Secured Lending?

✓Australian private lender, $500M+ funded
✓We use our own funds for fast decisions
✓24-hour settlements, loans from $250k
✓Rates from 9.7% p.a. | Terms 1 to 24 months

Are you a broker? Find out why brokers love working with us.