Urgent Short Term Loans to Cover a Settlement Shortfall
Cover the difference between your funds and the settlement figure, and settle on the agreed date
Experts in strategic, short-term finance
Finding out close to settlement that your funds will fall short is worrying, but it is a common problem and one we can usually solve quickly. We lend the difference, often in as little as 24 hours, so you can settle on the agreed date.
We cover shortfalls on commercial, industrial and investment property purchases across Australia, from $250,000 up to $10 million. The loan usually runs for a few months, until the money you were waiting for arrives or a bank refinance is in place.
Why settlement shortfalls happen
- •The bank valuation came in below the purchase price, so the bank reduced its loan
- •The sale of another property has been delayed, and its proceeds will not arrive in time
- •A co-buyer or investor has withdrawn their share
- •Stamp duty or GST is higher than you budgeted for
- •Funds you expected from a business or another settlement have been delayed
What the loan covers
- •The difference between your bank loan and the settlement figure
- •Stamp duty, registration fees and adjustments due at settlement
- •The balance of a deposit that was only partly paid on exchange
- •The whole purchase, where it is simpler for us to fund it and your bank to refinance later
How much you can borrow for the gap
The combined borrowing across all the property we hold as security can be up to 70% of its value. If you already own another property with equity, a second mortgage over it is often the quickest way to cover the gap, because your bank loan on the purchase stays as it is. Where the purchase has enough value on its own, we can take a first mortgage over it and fund the whole amount.
From call to settlement
Call us. Tell us the settlement date, the amount you are short and which property you can offer. We reply with an indicative offer, usually within hours.
Valuation. Our in-house valuers assess the property, usually within a day.
Letter of offer. We issue it as soon as you accept our terms, and our solicitors work with your solicitor and your bank.
Settlement. Our funds are paid at settlement alongside your bank's, in as little as 24 hours from a signed letter of offer.
What we will ask for
- •The contract of sale and the settlement figures from your solicitor
- •Your bank's loan approval, showing the amount it will lend
- •The address and current mortgage balance of the property you are offering
- •How the shortfall loan will be repaid, for example a property sale or a refinance
Loans that can cover the shortfall
- •Second mortgage: over another property you own, behind your existing bank loan
- •Caveat loans: the fastest option for a short gap, registered on a property you own
- •First mortgage: over an unencumbered property, or over the purchase if we fund all of it
- •Bridging loans: where the gap will be repaid by the sale of another property
Shortfall loan terms
| Loan feature | Detail |
|---|---|
| Loan size | $250,000 to $10,000,000 |
| Interest rate | From 9.7% p.a. on a first mortgage, from 11.95% p.a. on a second mortgage |
| Term | 1 to 24 months, interest only. Most shortfall loans run for 3 to 6 months |
| Maximum LVR | 70% across all the property we hold as security, including existing mortgages |
| Security | A first or second mortgage, or a caveat, over residential, commercial or industrial property |
| Settlement | From 24 hours |
Repaying the shortfall loan
Most shortfall loans are repaid when the delayed money arrives: the sale of another property, a bank increasing its loan after a new valuation, or funds from a business. We agree the repayment plan before settlement and set the term with time to spare, so a short delay does not cause a problem.
Shortfalls we have covered
“Most buyers with a shortfall have enough equity. The problem is that it is held in another property, or their sale settles after their purchase. We look at the property they can offer and when the loan will be repaid, and with those answers we can usually lend the difference within a day or two.”
Gino Tabila
Associate Director
Frequently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
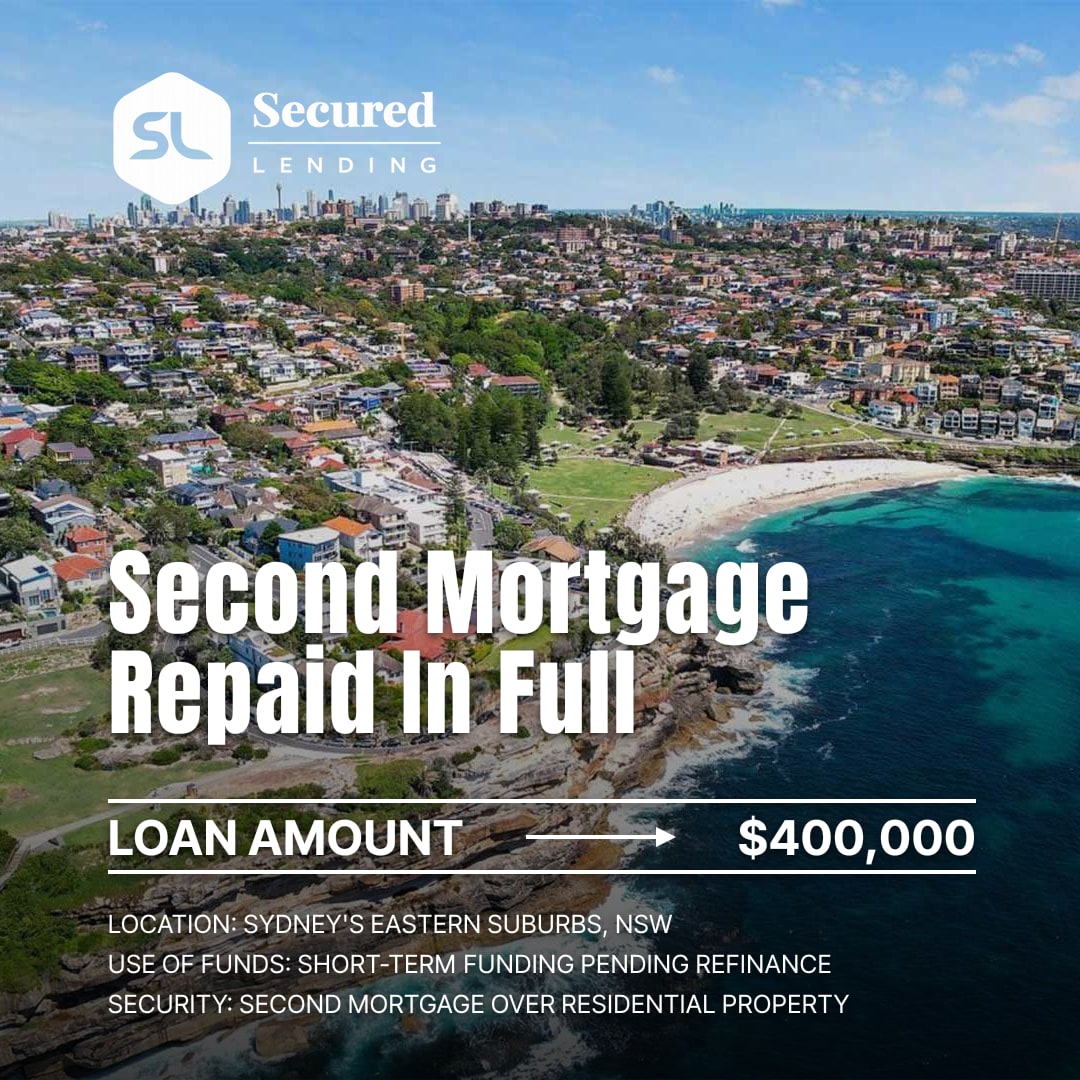
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
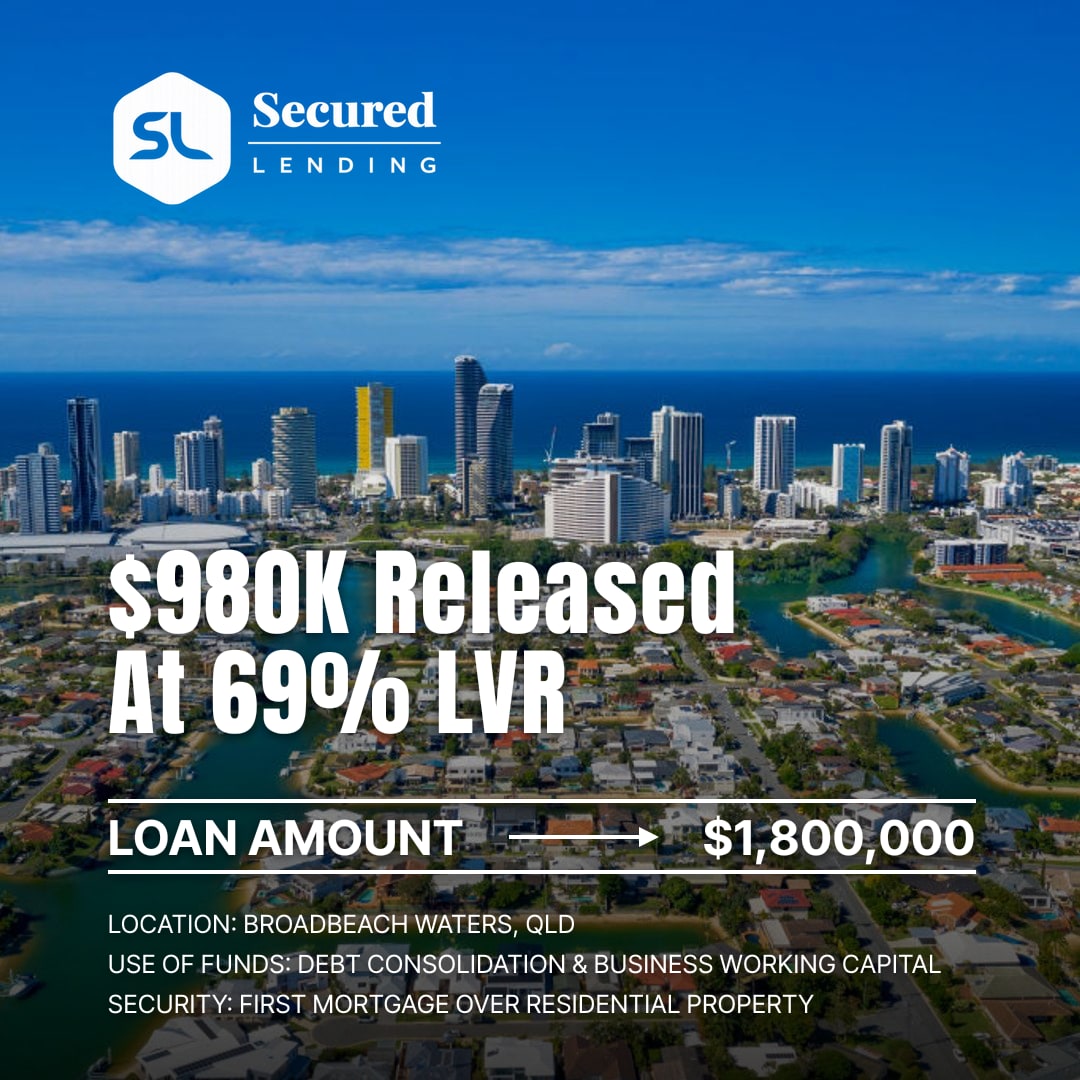
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
$700K Working Capital for a Technology Start-Up Settled in 72 Hours
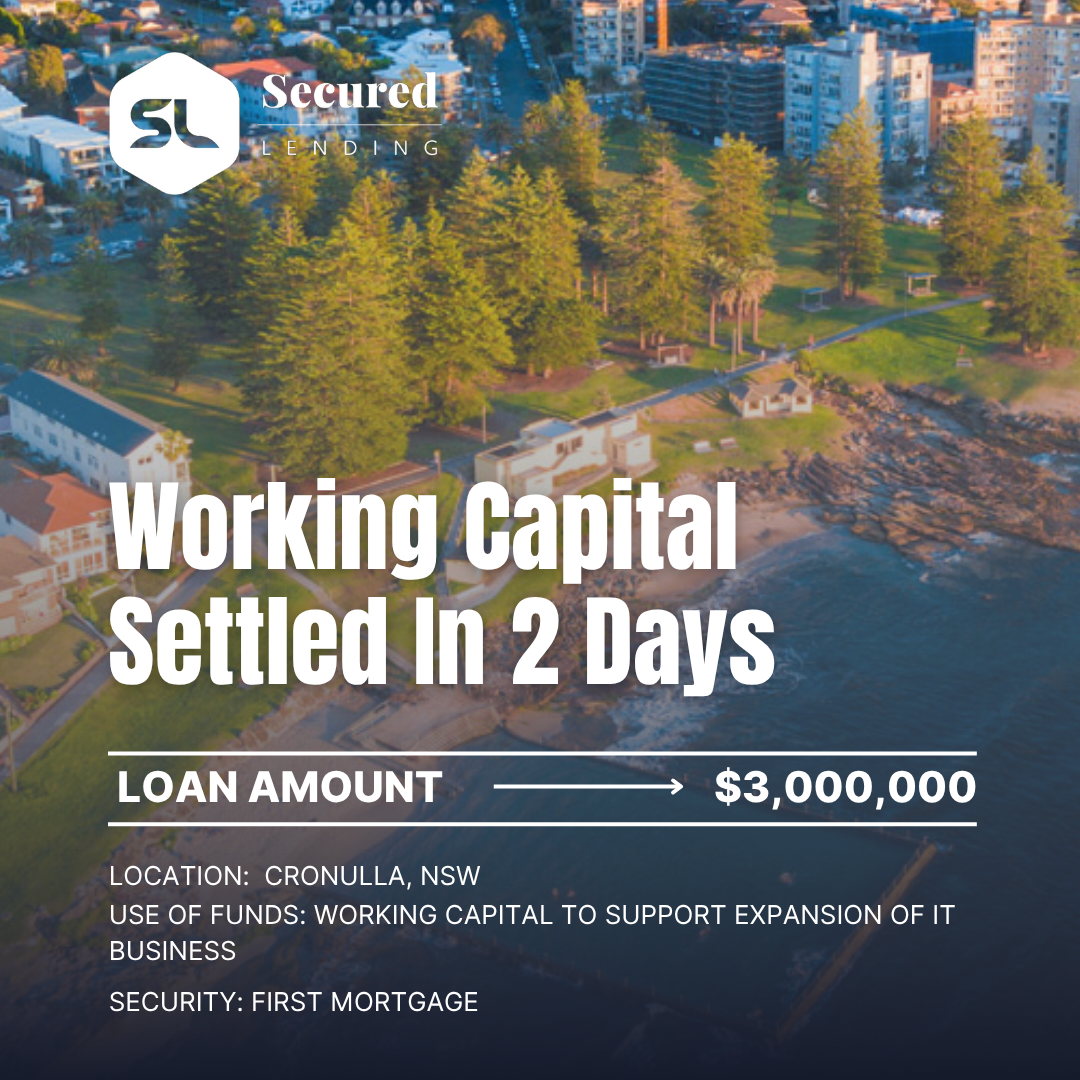
$3M Working Capital for IT Business Expansion Settled in 2 Business Days
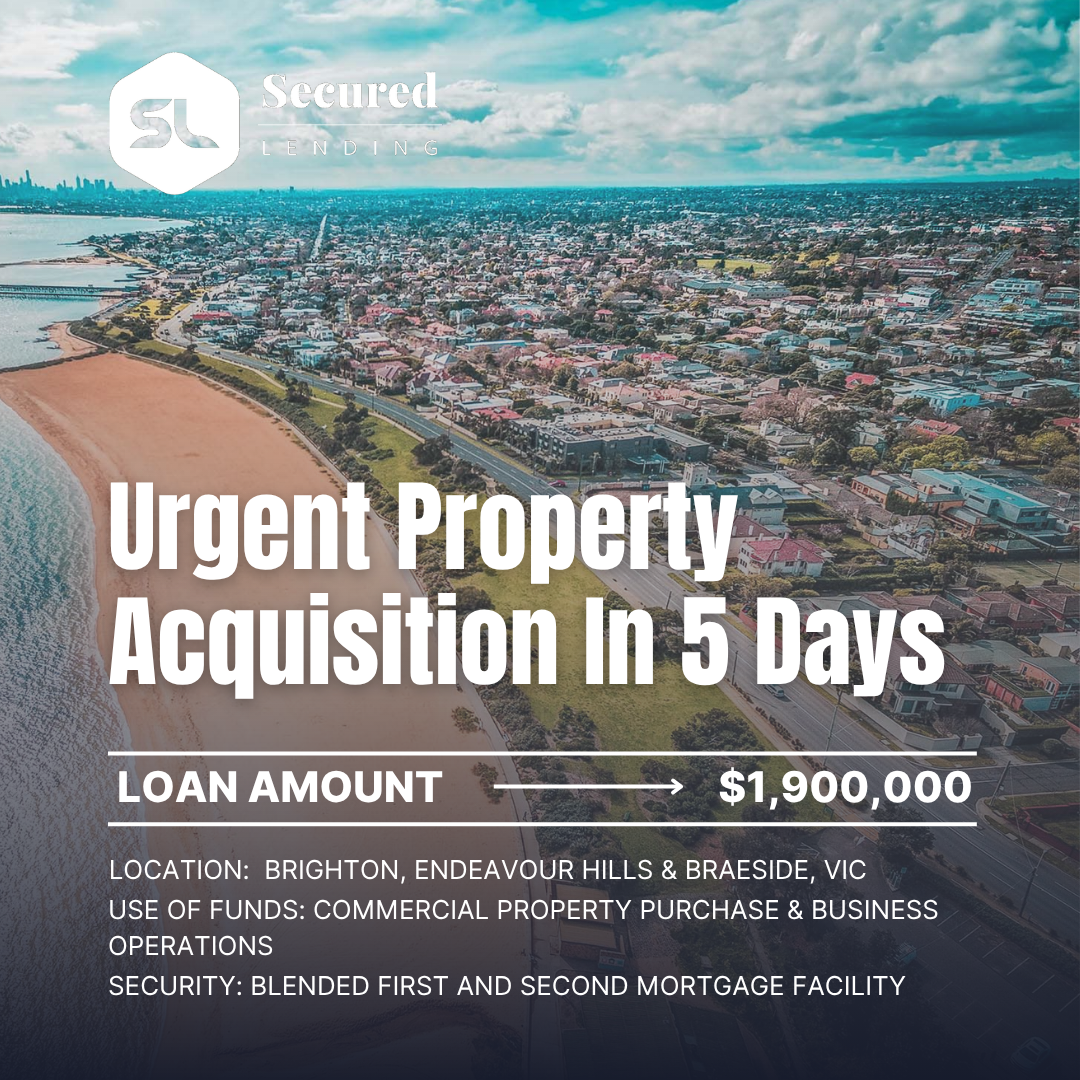
$1.9M Commercial Property Acquisition for Growing Doggy Daycare Business
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Other Urgent Loans We Fund
Each page covers one deadline: what we fund, what to send us and how quickly we can settle.