Refinance Before a Mortgagee Sale With Urgent Short Term Finance
Pay out the enforcing lender, then sell or refinance on your own timetable
Experts in strategic, short-term finance
When a lender takes possession of a property, the lender decides how and when it is sold. A refinance that pays the lender out in full, before a sale contract is signed, can return that decision to you. We can fund it in as little as 24 hours.
We lend for business and investment purposes on residential, commercial and industrial property across Australia. We do not give legal advice, so ask your solicitor to check the notice and the stage the lender has reached. If the owner is a company that may not be able to pay its debts, we can connect you with insolvency specialists in our network before you borrow.
The stages of enforcement
- •Missed repayments, or a loan that has passed its maturity date
- •A default notice giving time to fix the default: 30 days in Queensland, and set by each state's law elsewhere
- •A demand for the full debt once the notice period ends
- •Possession of the property, or the appointment of a receiver
- •An agent appointed, the property listed and a sale campaign started
- •A contract of sale signed by the lender
Once the lender has signed a contract to sell, a refinance may no longer stop the sale, and your solicitor can confirm whether it still can.
How much you will need to borrow
The lender in possession sets the payout figure. It usually includes the arrears, the loan balance, default interest and the lender's enforcement costs, such as legal fees, agent's fees and the cost of taking possession. Our loan has to cover that figure within 70% of the property value, so an up-to-date written payout figure is the first thing to ask for.
Selling on your own terms
Many owners want to sell the property themselves, with their own agent and a normal campaign. In Queensland, a lender that sells must take reasonable care to sell at market value. With a refinance, you choose the agent, the campaign and the timing, and the sale repays our loan.
Paying out the lender
Enquiry. Send us the default notice, any possession notice and the lender's payout figure. We tell you within hours whether the numbers work.
Valuation. We value the property, with access arranged through you or the agent.
Letter of offer. Accept the terms and sign the letter of offer.
Settlement. We pay out the lender at settlement, within 24 hours of signing, subject to its discharge.
Documents for a payout loan
- •The loan contract and every notice from the lender
- •The lender's written payout figure
- •Any agency agreement or listing the lender has arranged
- •Your plan: a sale on your own terms, or a bank refinance
Loans that can pay out an enforcing lender
- •First mortgage: to pay out the enforcing first mortgagee in full
- •Second mortgage: to pay the arrears, where the first lender agrees to reinstate the loan instead of requiring full payment
- •Bridging loans: where your own sale of the property will repay us
- •Caveat loans: over another property you own, for a short period until a sale or refinance settles
Payout loan terms
| Loan feature | Detail |
|---|---|
| Loan size | $250,000 to $10,000,000 |
| Interest rate | From 9.7% p.a. (first mortgage), from 11.95% p.a. (second mortgage) |
| Term | 1 to 24 months, interest only |
| Maximum LVR | 70% of the property value, covering the full payout figure |
| Security | A first or second mortgage over the property, or a caveat over other property you own |
| Settlement | From 24 hours |
Repaying the payout loan
A payout loan is repaid by a sale the owner controls, or by a bank refinance once the arrears are cleared and repayments have been made on time for a period. The repayment plan is agreed with you before we settle.
A payout we funded
“By the time a lender takes possession, the owner has usually been dealing with arrears or an expired loan for months, and enforcement costs grow every week. We look at the property and the payout figure, and if the numbers work we pay the lender out. The owner can then sell with their own agent or refinance, instead of the lender running the sale.”
Gino Tabila
Associate Director
Frequently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
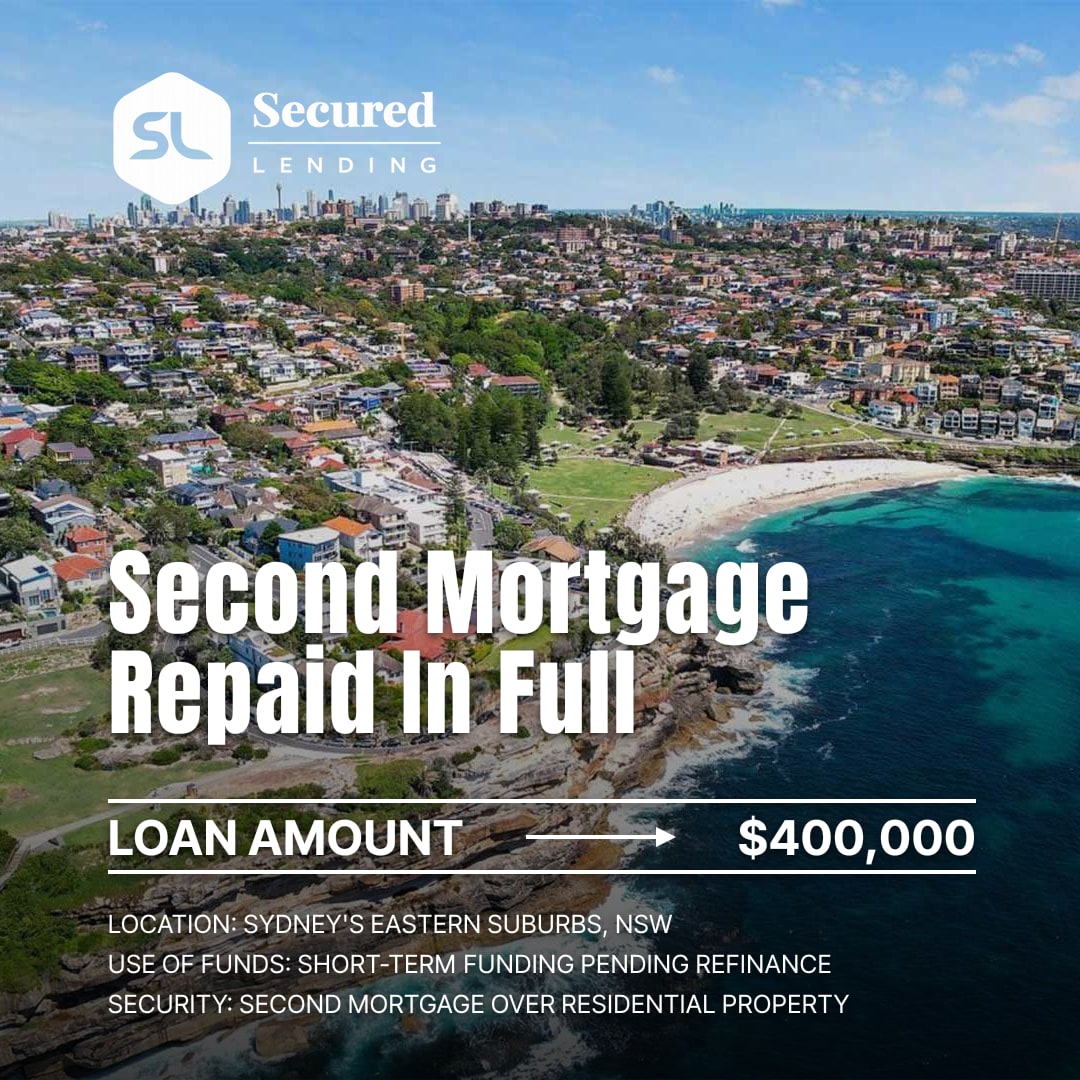
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
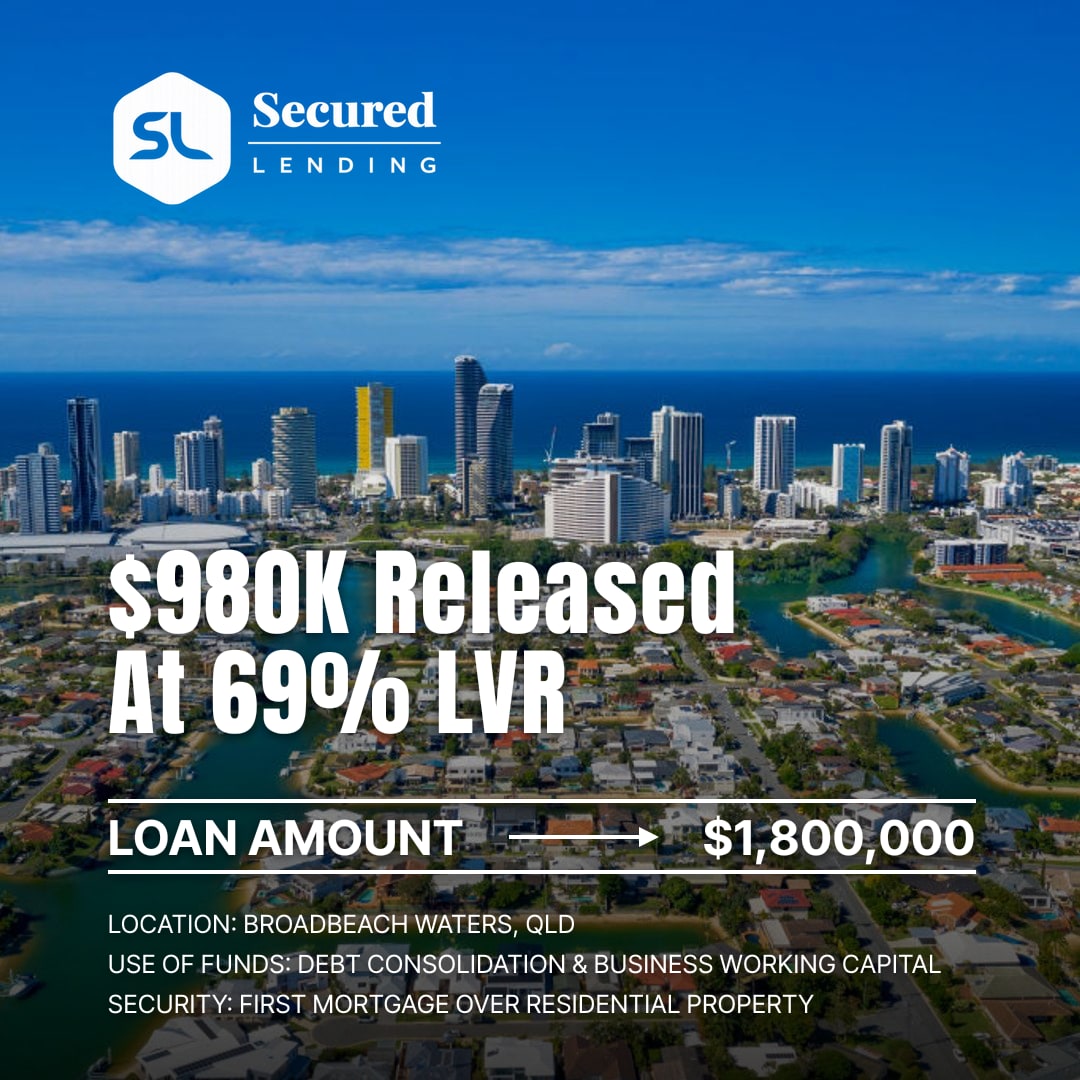
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
$700K Working Capital for a Technology Start-Up Settled in 72 Hours
$3M Working Capital for IT Business Expansion Settled in 2 Business Days
$1.9M Commercial Property Acquisition for Growing Doggy Daycare Business
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Other Urgent Loans We Fund
Each page covers one deadline: what we fund, what to send us and how quickly we can settle.