Urgent Short Term Loans to Repay a Construction Loan on Unsold Units
Repay your construction lender, then sell the remaining units at the right price
Experts in strategic, short-term finance
Construction lenders usually want to be repaid soon after practical completion, but selling the last units can take months. If your construction loan is due and some units are still unsold, we can refinance it in as little as 24 hours, so you can sell at a fair price instead of discounting to meet the lender's date.
We lend on completed apartments, townhouses and houses across Australia. The loan runs for 1 to 24 months, and each unit can be released as it sells.
Why developers are left holding completed units
- •Sales slow after completion, and the construction loan matures first
- •Off-the-plan buyers fail to settle because their bank valuation came in low
- •The construction lender adds default interest or a higher margin after maturity
- •Land tax, strata levies and marketing costs continue on every unsold unit
- •The next project needs a deposit, and the capital is tied up in the unsold units
The Reserve Bank has noted that a small share of new apartments fail to settle even when market conditions are supportive, and that buyers' borrowing depends on the bank valuation at completion.
What we fund
- •Repaying the construction lender in full
- •Covering the shortfall left by buyers who did not settle
- •Holding costs while the remaining units sell
- •Releasing equity from unsold units to start your next project
Unit releases as each sale settles
Before settlement, we agree a release amount for each unit. When a unit sells, part of the sale proceeds repays that amount and the unit is released from our mortgage, so the sale can settle. You can sell units one at a time, on your own timetable.
Refinancing a maturing construction loan
Call. Send us the list of unsold units, recent sale prices and the construction loan maturity date. Indicative terms reach you within hours.
Valuation. Our valuers assess each unsold unit on its own, as completed property.
Letter of offer. After you accept, the letter of offer is sent the same day, with the release amount for each unit.
Settlement. We repay the construction lender at settlement, within 24 hours of the letter of offer being signed.
Information about your units
- •A schedule of unsold units with titles and asking prices
- •Recent sales in the project, including any that failed to settle
- •The construction lender's payout figure and maturity date
- •Your sales plan, including the agent's marketing campaign
Loans for unsold completed units
- •First mortgage: over the completed units, to repay the construction lender
- •Second mortgage: behind a construction lender that agrees to stay, to cover a shortfall
- •Bridging loans: for a set sell-down period with a clear end date
- •Secured business line of credit: for strata levies, land tax and marketing costs during the sell-down
Residual stock loan terms
| Loan feature | Detail |
|---|---|
| Loan size | $250,000 to $10,000,000 |
| Interest rate | From 9.7% p.a. (first mortgage), from 11.95% p.a. (second mortgage) |
| Term | 1 to 24 months, interest only. Interest can be capitalised until units sell |
| Maximum LVR | 70% of the assessed value of the completed units, not the list price |
| Security | A first or second mortgage over the completed, unsold units |
| Releases | An agreed release amount for each unit as it sells |
| Settlement | From 24 hours |
Selling down and repaying
The loan is usually repaid as the units sell, through the release amounts agreed at the start. Some developers keep a few units as rentals and refinance them to a bank, or sell the remaining units to one investor. We agree the plan with you and set the term to allow for a realistic sales campaign.
“Completed units are finished property with a clear value, and they usually sell. The difficulty is timing: the construction lender wants to be repaid before the last units are sold. We repay the construction lender, agree a release amount for each unit, and give the developer time to sell without discounting.”
Gino Tabila
Associate Director
Frequently Asked Questions
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Case Studies
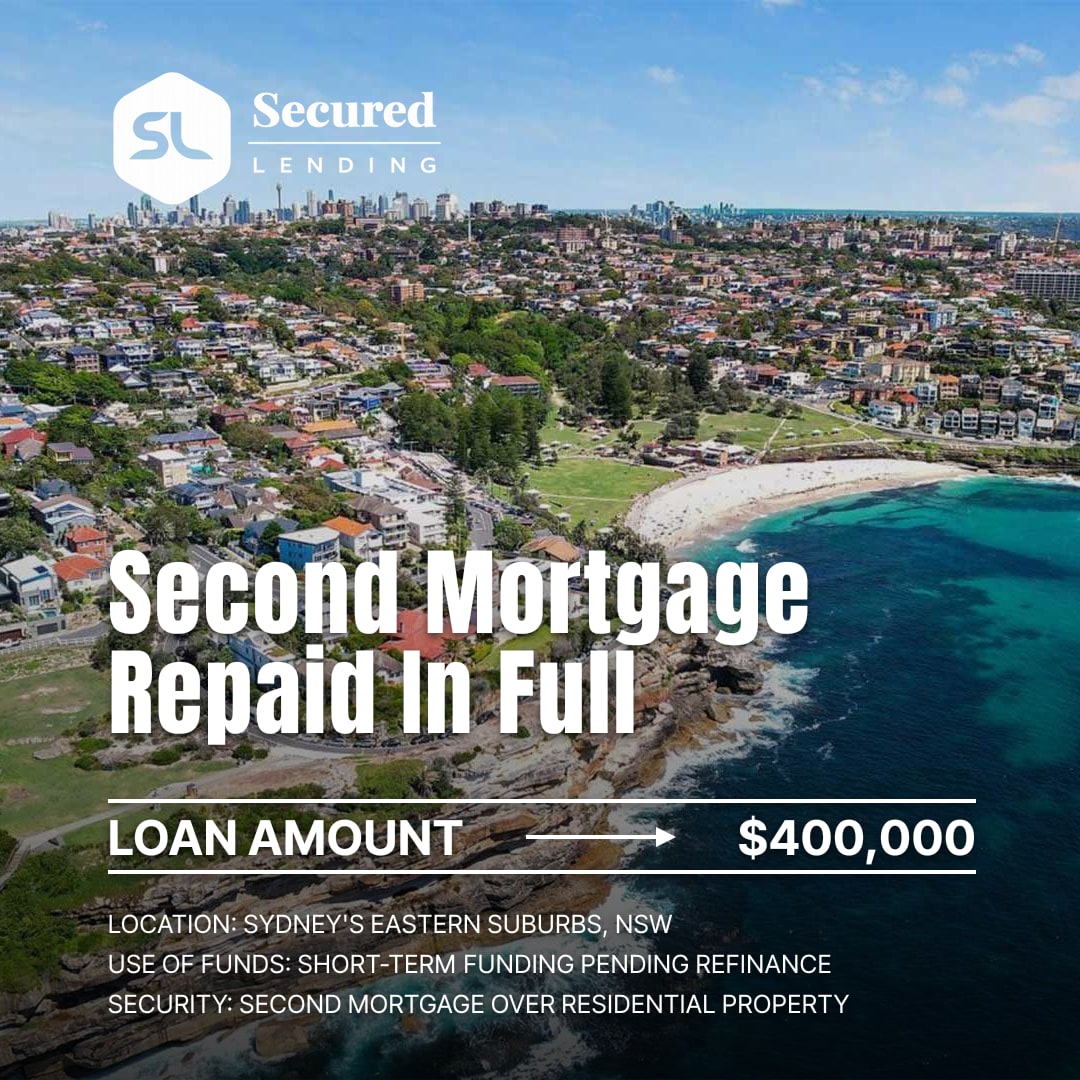
$400K Second Mortgage Repaid in Full After a Flexible Two-Month Extension
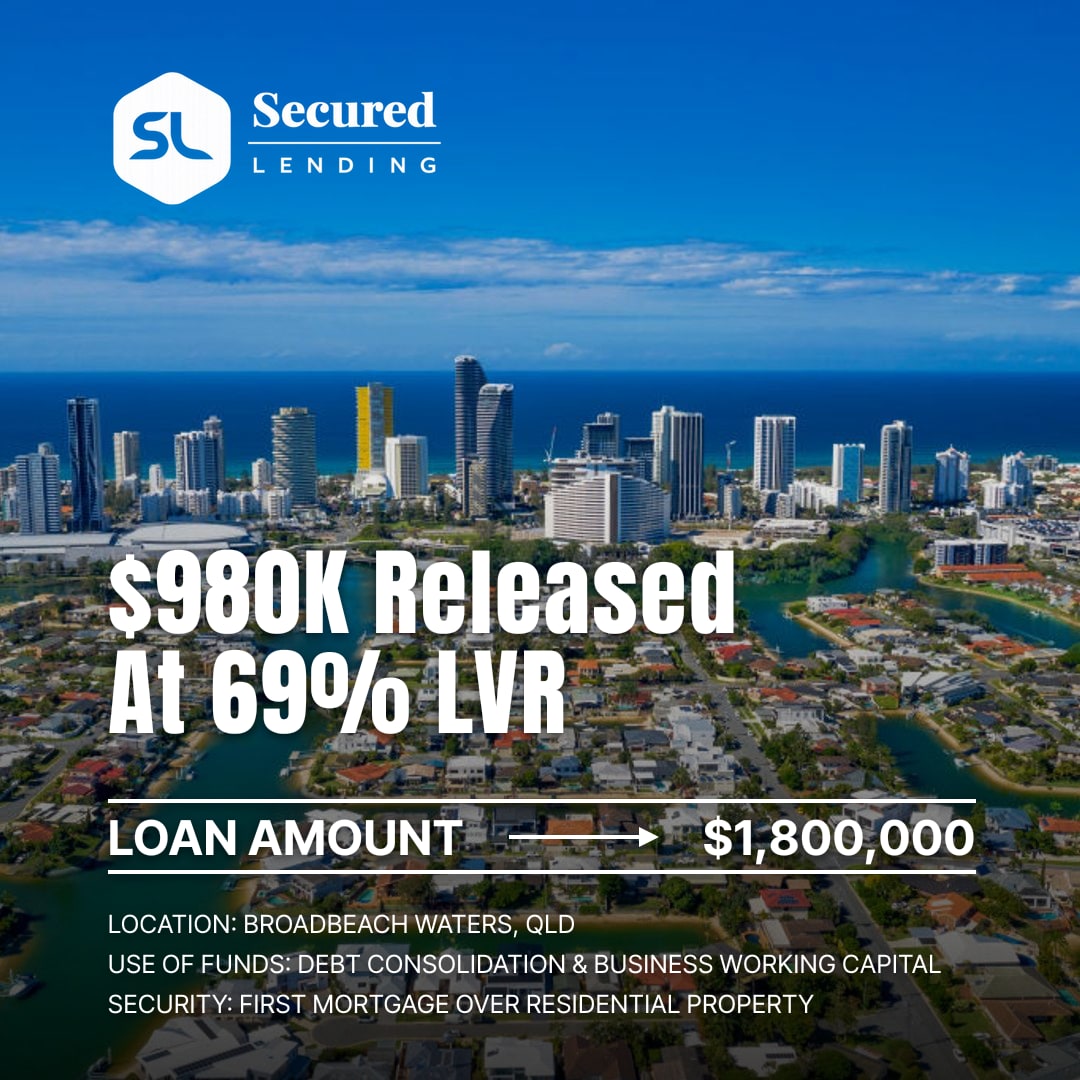
$1.8M First Mortgage Releases $980K of Working Capital for a Solar Business
$2.3M Second Mortgage Refinances an 18% Facility for a Glass Manufacturer
$800K Bridging Finance for Simultaneous Property Transactions in 48 Hours
$300K Second Mortgage for Dental Practice Working Capital in 5 Days
$700K Working Capital for a Technology Start-Up Settled in 72 Hours
$3M Working Capital for IT Business Expansion Settled in 2 Business Days
$1.9M Commercial Property Acquisition for Growing Doggy Daycare Business
Get an indicative offer within hours, not weeks.
No credit check. No obligation.
Why Secured Lending?
Are you a broker? Find out why brokers love working with us.
Other Urgent Loans We Fund
Each page covers one deadline: what we fund, what to send us and how quickly we can settle.