Key takeaways
- •When your bank moves your business loan to its recoveries team, it means the bank wants to reduce what it has lent to your business, even if no repayment has been missed.
- •The recoveries team will usually ask for your latest management accounts and a cash flow forecast. The bank may also order a new valuation of your property, or appoint an accountant to review your business.
- •If your business is a small business under the Banking Code of Practice, the bank must generally give at least 30 days' notice of a missed payment before it demands repayment of the whole loan.
- •The best time to refinance your bank is before it issues a default notice. At that point, the amount needed to repay the bank in full is usually close to the loan balance.
- •A private loan from Secured Lending, from $250,000 and secured by property, can repay your bank in full at settlement, and we can settle within 24 hours on qualifying loans.
- •We can still refinance your bank after a default notice, a letter of demand or a receiver's appointment, but each of those steps can add default interest and the bank's costs to the amount needed to repay it.
If your bank has told you that your business loan is moving from your relationship manager to a team called recoveries, business restructuring, credit management or something similar, it means the bank has decided the loan needs closer management and wants its exposure reduced. Often no default notice has been issued at this point, and the loan contract has not changed. What has changed is the goal of the person managing your file: to have the loan reduced, more heavily secured, or repaid.
That is unsettling news, and it is also the best time to act. Before a default notice, the amount needed to repay the bank is close to the loan balance, and your business still chooses the date. If your business or a director owns property, we would be glad to look at refinancing the bank now.
A private loan suits this problem because we assess something different from the bank. The recoveries team looks at trading, forecasts and covenants. We lend against real property, a first or second mortgage over residential, commercial or industrial property, and we look at the property's value, a loan within 70% of it, and how the loan will be repaid. We lend our own funds, make decisions within hours, and can settle within 24 hours on qualifying loans.
What it means when your loan moves to the recoveries team
Banks give these teams different names, but their job is the same: to reduce the bank's risk on loans it is no longer comfortable holding. Your relationship manager's job was to keep and grow your business as a customer. The new team's job is to get the bank's money back, either by having the loan reduced, by taking more security, or by having the loan repaid and the business move to another lender.
A file is usually moved after something specific. Common reasons include:
- •an annual facility review where the accounts showed weaker trading
- •a letter saying a covenant in the facility agreement has been breached
- •a new valuation of the property that came in lower than the last one
- •repayments that have fallen behind
- •a loan that has passed its expiry date without being renewed
- •a debt to the Australian Taxation Office that the bank found during a review
On the first day, the move changes who manages your loan, not the terms of the loan. Your repayments, interest rate and expiry date usually stay as they are until the bank takes a formal step such as a default notice, a letter of demand or a decision not to renew. Until the bank takes one of those steps, your business has time to act, and how much time depends on which step comes next.
What the recoveries team will usually ask for
The new contact will usually ask for a meeting and for the latest management accounts, a cash flow forecast, and an explanation of how the business plans to trade through the next few months. The bank may also order a new valuation of the property, ask for more security or a lower facility limit, or appoint an investigating accountant to review the business.
Answer these requests promptly and accurately. The Banking Code of Practice lists materially incorrect or misleading information given to the bank as a default the bank can act on.
If your business is a small business under the Code, two of its commitments apply here:
- •Valuations. Where the bank has received a valuation of a commercial property that your business paid for, it will give you a copy of the valuation and the instructions given to the valuer, except where enforcement proceedings have already started.
- •Investigating accountants. The bank will act fairly when it uses investigating accountants, and if the relationship between you and the accountant becomes unworkable, it will consider appointing a different practitioner. If you are concerned that the accountant could later be appointed as receiver, paragraph 99 of the Code says: "We will require additional internal oversight of the appointment of investigating accountants as receivers, to ensure that the decision is necessary and to review the circumstances leading to the appointment."
Whether your business has to agree to any particular request depends on your facility agreement. Your solicitor can read it with you.
How much notice the bank has to give you
The Banking Code of Practice gives extra protections to a business that counts as a small business. That means a business that, with its business group where it has one, had annual turnover of less than $10 million in the previous financial year, has fewer than 100 full-time equivalent employees, and owes less than $5 million in total to all credit providers, counting undrawn limits. The Code applies to banks that have adopted it, and the Australian Banking Association lists them.
For a small business, the main protections are these:
- •A missed payment. Paragraph 82 says the bank will give "no less than 30 Days’ notice of the payment failure before we make a demand for full repayment or take Enforcement Proceedings in relation to your Loan(s)". If the overdue amount, and any later missed payment, is paid within that period, the bank will not demand the whole loan or take enforcement proceedings for non-payment.
- •Other defaults. The bank can act on a default other than a missed payment only if it is one of the events the Code lists, such as insolvency, incorrect information, or a change in ownership without the bank's consent, and only if the event is material. For those events, the bank must tell you the grounds and give at least 30 days to fix the default where it can be fixed.
- •Covenants. In a standard form small business loan, financial indicator covenants can be a trigger for action on a default only in specialised loans, such as loans for property development and construction finance. The contract also cannot include a default for an unspecified material adverse change.
- •Non-renewal. Where your business is not in default and the loan balance is due in one amount at the end of its term, rather than paid down by regular repayments, the bank will give at least 3 months' notice of a decision not to extend the loan.
The bank can give shorter notice, or none, if the business or a guarantor is insolvent, or if shorter notice is reasonable to manage a material and immediate risk, including a risk to the value of the security. If your business is above the small business thresholds, the Code's small business protections do not apply, and the facility agreement sets the notice periods. In either case, your solicitor can tell you which rules apply to your loan. We are a lender, and we do not give legal advice.
Refinancing the bank while your loan is in recoveries
A refinance repays the bank in full, which is the result the recoveries team is there to reach, and it does so on a date your business chooses.
Another bank will usually look at the same figures that sent your file to recoveries. Under the Code, a bank deciding whether a small business can repay a new loan considers its financial position or account conduct, and may take its projected cash flows into account. We look at different things: the value of the property, a loan within 70% of that value, and how the loan will be repaid. A business whose trading has weakened can still repay its bank, as long as the property and the exit support the loan.
This is how a refinance of a business loan with us works:
- •The borrower. The loan is made to your company. We lend to companies, never to individuals.
- •The security. A first or second mortgage over property your company owns, or over a director's home or investment property. Total borrowing on each property, including any loan that stays in place, sits within 70% of its value.
- •The payout. The loan funds are paid to your company and repay the bank in full at settlement, and the bank then discharges its mortgage.
- •Working capital. Where there is room within the 70% limit across all loans on the property, the loan can include working capital on top of the payout figure.
- •The term and rate. Terms run from 1 to 24 months, most are 3 to 6 months, and rates start from 9.7% p.a. on a first mortgage and 11.95% p.a. on a second.
- •The exit. Your company repays us through a defined exit agreed before settlement, such as a refinance to a bank once trading has recovered, or the sale of a property.
The timing matters because of the payout figure. Before a default notice, the figure is usually the loan balance plus interest to the payout date. Once a default notice is issued, the facility agreement may allow the bank to add default interest and its enforcement and legal costs, and the figure grows for each week the loan stays in default. A smaller payout figure also leaves more room within 70% of the property's value.
If the bank's new valuation has put the loan above 70% of the property's value, our in-house valuers value the property themselves. Where one property does not cover the payout, a second property can be added as security within the same 70% limit. If that is a director's home with a home loan on it, our loan can sit behind the home loan as a second mortgage, with the combined borrowing within 70% of the home's value.
Many business loans are also secured by a general security agreement over the whole business. That does not stop a property-only refinance. Our loan is secured only by real property, and when the bank is repaid in full it is asked to release its mortgage and its general security agreement. Ask the bank for a list of every security it holds, and your solicitor can check that each one is released at settlement.
What to send us in the first week
You do not need a formal application to find out whether a refinance works. If you would like us to look at it, these are the documents that let us give you an answer quickly:
- •the bank's letters, including the one that moved your file and any covenant or review letters, with their dates
- •a written payout figure from the bank, with the date it is valid to
- •a current title search for each property that could secure the loan
- •an estimate of each property's value and any other loan on it
- •the list of securities the bank holds, such as mortgages, a general security agreement and guarantees
- •how your company plans to repay our loan, and roughly when
A payout figure is not a commitment to repay. It tells us the amount to work to, and asking for one now saves a step later.
If the bank has already gone further
If the bank has issued a default notice, sent a letter of demand, or appointed a receiver, we can still refinance the bank. We refinance a lender before or after a default notice, and before or after a receiver is appointed. We can still refinance after a receiver has signed a conditional contract with a buyer, although whether that contract can be ended is a question for your solicitor and the receiver. Where it is needed, we can work with the receiver directly, for example to arrange access to the property for our valuation.
At these later stages, the payout figure is larger and the bank sets the dates, so the earlier you call, the more time your business has. Our page on refinancing a lender that is moving to enforce covers each stage in more detail. What a refinance means for a receiver's appointment is a question for insolvency specialists. We do not give insolvency advice, and we can connect you with insolvency specialists in our network.
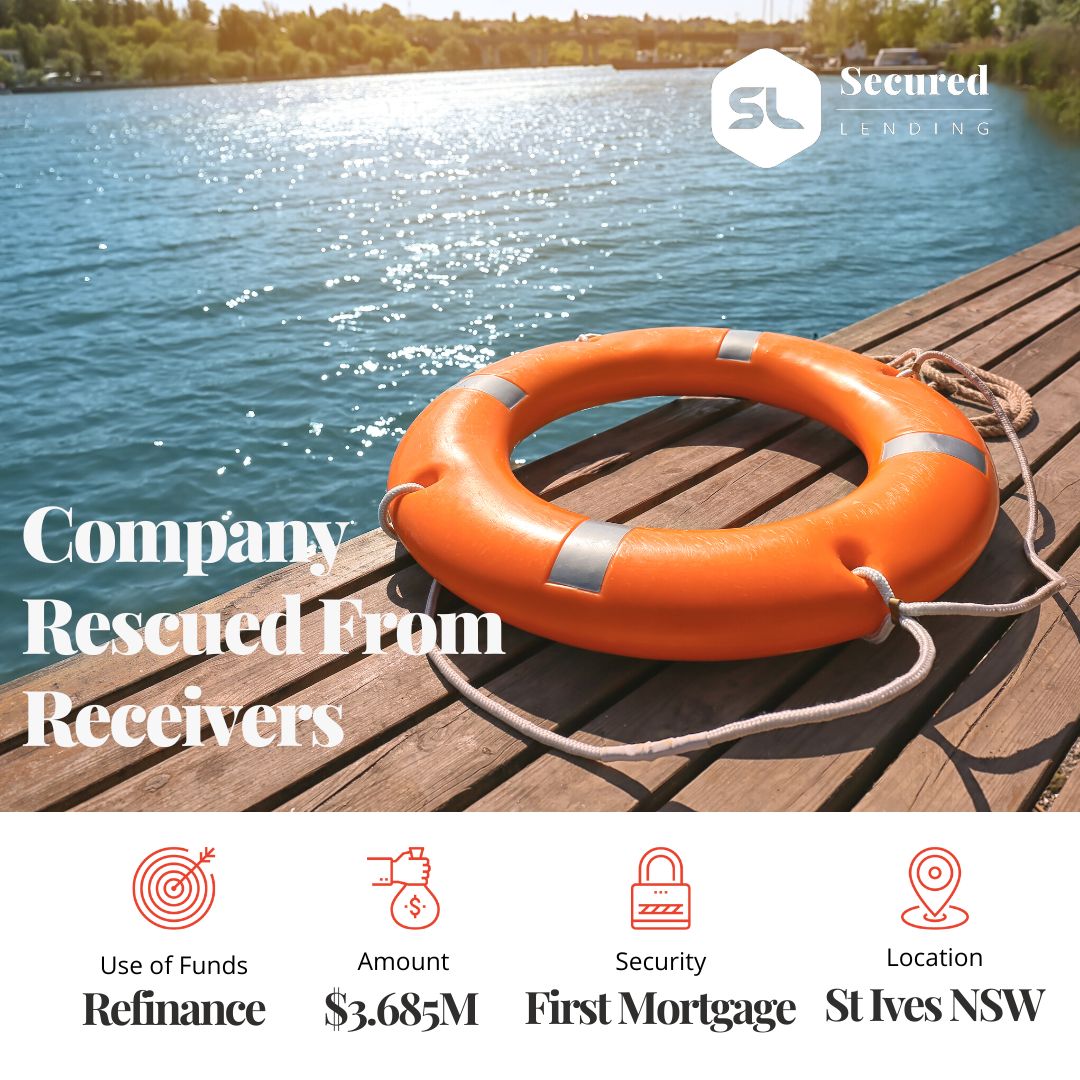
Case study: $3.685 million to pay out a mortgagee after a receiver was appointed
A borrower came to us after a receiver had been appointed, with interest and costs being added to the debt quickly. The borrower needed the existing mortgagee paid out with speed and certainty.
We provided a $3.685 million loan secured against a property in St Ives, New South Wales. The loan funded the payout of the existing mortgagee, which gave the borrower time to sell the St Ives property itself, on its own terms.
A loan in recoveries has not reached that stage. A refinance arranged before a default notice repays a smaller figure, and your business chooses the settlement date.
Frequently asked questions
Our loan moved to recoveries after the bank's new valuation came in lower. Can you still refinance it?
Yes, where the payout figure fits within 70% of the property's value. Our in-house valuers value the property themselves, and if one property does not cover the payout, a second property owned by your company or a director can be added as security within the same limit.
The bank wants to appoint an investigating accountant. Should we refinance before that happens?
That is your decision, and we can move quickly if you decide to refinance. A refinance repays the bank in full, and our assessment does not depend on an investigating accountant's report. Whether your business must agree to the appointment depends on your facility agreement, which your solicitor can read with you.
Our bank holds a general security agreement as well as a mortgage. Can a loan secured only by property repay it?
Yes. When the bank is repaid in full at settlement, it is asked to release its mortgage and its general security agreement. Ask the bank for a list of every security it holds, so your solicitor can check that each one is released.
Can my home secure a refinance of my company's loan while the bank's recoveries team has the file?
Yes, with your company as the borrower. A director's home or investment property can secure the company's loan within our 70% maximum loan-to-value ratio. If the home already has a home loan, our loan can sit behind it as a second mortgage.
How does my business get back to a bank after a private refinance?
Our loan runs from 1 to 24 months, and the term is set to the exit you plan. For example, your business can use the term to show a period of steady trading and then refinance to a bank, or repay us from the sale of a property. The exit is agreed before settlement.
How Secured Lending Can Help
We would be glad to help your business repay its bank while your business still chooses the settlement date. A move to the recoveries team usually comes before any default notice, so the payout figure is at its smallest and the bank has not yet set a deadline. Our loan is made to your company, repays the bank in full at settlement, and can include working capital where the property allows. Your company then repays us through a defined exit, such as a bank refinance once trading has recovered, or a property sale.
A private loan suits this problem because we look at the property and the exit rather than the trading figures the bank is reviewing. We lend our own funds, our in-house team values the property, we make decisions within hours, we issue a letter of offer as soon as terms are agreed, and we can settle within 24 hours on qualifying loans. Loans start from $250,000, and rates start from 9.7% p.a.
If you would like us to look at your situation, it helps to have the bank's letters, a payout figure and the details of the property to hand. You are welcome to call us on 1300 795 175 to talk it through, or send the details through and we will come back to you. In most cases, we can tell you within hours whether a refinance can repay your bank.